



PW Consulting: Robot Joint Precision Reducers Market to Reach $11.46B by 2032 at 15.81% CAGR

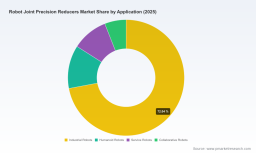
Robot Joint Precision Reducers Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
As companies position for the next wave of robotics-driven automation, precision reducers for robot joints have emerged from a specialist component category into a strategic fulcrum for competitive differentiation. Our market study shows a sustained, high-growth trajectory: the market has more than doubled since 2020 and reached a multi‑billion USD scale by 2025, with a projected compound annual growth rate of approximately 15.8% across the 2026–2032 forecast horizon. For executives making capital allocation, sourcing, product and partnership decisions in 2026, understanding the commercial, technical and supply‑chain inflection points in this market is now table stakes.
Robot Joint Precision Reducers Market
Why this study matters for 2026 strategic choices
-
Timing of scale: With growth accelerating, decisions taken in 2026 about capacity, vertical integration and supplier contracts will determine who captures the next wave of volume and margin. The report quantifies market momentum and models breakpoints where scale begins to unlock step-change unit economics.
Robot Joint Precision Reducers Market -
Technology differentiation: Robot joint reducers are no longer interchangeable commodity items. Variations in backlash, torque density, rigidity, size and lifetime reliability affect system-level performance, cycle time and total cost of ownership. Our analysis connects component attributes to end‑user KPIs so R&D and product teams can prioritize the next feature set that drives OEM selection.
Robot Joint Precision Reducers Market -
Risk management: Raw material and capacity dynamics create asymmetric risks. The report synthesizes recent material cost moves, capacity expansions and regulatory trends into actionable hedging and supplier diversification tactics tailored for 2026 procurement windows.
What this report delivers — the practical toolkit
-
Market sizing and growth scenarios: A top‑down and bottom‑up valuation of the addressable market for precision reducers from 2020 through 2032, with sensitivity cases that reflect varying adoption rates across robot archetypes and industrial cycles.
-
Demand-driver mapping: Clear linkage between macro drivers (factory automation, semiconductor and automotive investments, service and humanoid robotics growth) and component demand, with demand models that allow users to stress-test their volume and revenue plans under alternative adoption curves.
-
Competitive benchmarking and playbooks: Standardized scorecards that evaluate suppliers across product performance, quality footprint, vertical integration, pricing strategy and route-to-market. These are designed for rapid supplier selection and negotiation playbooks.
-
Supply‑chain stress tests: Scenarios and mitigation strategies for raw material volatility, single-source exposures, and logistics constraints—translated into procurement lead‑time policies and safety‑stock guidelines.
-
Technology and product roadmaps: Comparative analysis of RV, harmonic and precision planetary solutions (without granular segment disclosures in this preview), highlighting where innovation is creating new value levers for robot integrators and OEMs.
-
M&A and partnership screening: A prioritized list of target profiles, valuation heuristics and integration checklists for buyers seeking inorganic growth or component-level differentiation.
-
Regulatory and standards impact: Assessment of Industry 4.0, smart factory requirements, and how tightening uptime and precision standards shift procurement preferences.
Competitive landscape — what to watch in 2026
The supplier base combines long-established specialists from Japan and Europe with high‑volume manufacturers emerging from China and Central Europe. In this study we evaluate each firm across engineering depth, manufacturing capacity, after‑sales footprint and channel reach—profiling market leaders and fast followers to show where competitive advantage concentrates.
-
Nabtesco Corporation (Tokyo, Japan) : A leading name in RV cycloidal reducers for robot joints, widely specified by major industrial robot OEMs. Recent investments in Japanese capacity underline a strategy to meet semiconductor, automotive and humanoid demand—an important tactical detail for OEMs considering long-term supply assurances.
-
Harmonic Drive Systems Inc. (Tokyo, Japan) : The pioneer in strain‑wave reducers, with a product portfolio focused on zero‑backlash, compact high‑precision gearing. Ongoing product refreshes point to renewed emphasis on smaller-form-factor joints and collaborative robot niches.
-
Sumitomo Heavy Industries (Tokyo, Japan) : Offers high‑precision cycloidal lines that emphasize speed, vibration control and energy efficiency—attributes that matter in high‑throughput manufacturing and semiconductor handling robots.
-
Wittenstein SE (Igersheim, Germany) : Known for high‑precision planetary and cycloidal solutions suited to high‑performance automation in Europe, with engineering partnerships that favor premium OEM positions.
-
SPINEA (Haniska, Slovakia) : A European specialist in TwinSpin cycloidal reducers and DriveSpin actuators; their 2025 catalogue update signals a focused push into integrated actuator solutions for robotics applications.
-
Chinese and regional manufacturers : Several firms from China and other regions have scaled production and are targeting domestic and export channels with competitively priced harmonic and RV solutions. Their strategies focus on high‑volume supply and localized integration support.
Recent industry developments that drive 2026 urgency
-
Product refreshes and miniaturization: Leading suppliers launched compact, higher‑rigidity product lines and new series tailored to smaller joints and humanoid applications—an inflection that allows integrators to rethink actuator architectures.
-
Trade‑show and product catalog activity: High visibility at major events and catalogue refreshes from multiple suppliers signals accelerating market competition and a faster product cycle—impacting time‑to‑design‑win strategies.
-
Capacity movements: Major investments into new or expanded production capacity have been announced by incumbents; these moves have direct implications for lead times, qualification cycles and the bargaining power balance between buyers and suppliers.
-
Material cost pressures: Early‑2026 movements in hot‑rolled coil prices and modest global steel demand rebounds are already influencing component manufacturing costs—forcing procurement teams to reassess contract tenor and indexation clauses.
Operational implications and recommended actions for 2026
-
Procurement: Lock frame agreements with tiered volume discounts and indexation clauses tied to raw material benchmarks; create a dual‑sourcing plan for critical reducer families to reduce single‑source risk.
-
Product & R&D: Re-prioritize development roadmaps to capture gains from compact, zero‑backlash architectures and integrated actuator solutions. Consider co‑development or licensing with specialist suppliers to compress time‑to‑market.
-
Manufacturing & capacity planning: Align production ramp plans with the market’s high growth profile. Use the report’s scenario matrix to size buffer inventories and tool up for potential step changes in demand.
-
Strategy & M&A: Deploy the report’s target screening to identify acquisition candidates that fill technology gaps (e.g., compact harmonic expertise) or expand capacity in strategically important geographies.
-
Commercial & go‑to‑market: Tailor product bundles and service agreements that highlight total cost of ownership benefits—buyers increasingly compare lifecycle performance, not just unit price.
Key uncertainties and how the report helps you hedge them
We flag three principal uncertainties for 2026 decision-makers: input cost volatility, technology substitution across reducer architectures, and the pace of adoption in nascent segments such as humanoid and service robots. The report provides quantitative sensitivity analyses, supplier risk heatmaps and decision trees that convert those uncertainties into prioritized, executable mitigations.
How to use this preview—and what you won’t find here
This article is a strategic preview designed to surface the most consequential insights for 2026 planning: growth dynamics, competitive moves, technology trends, and operational actions. To preserve the commercial value of the full study we intentionally withhold detailed segment‑level breakdowns, regional and application percentage shares, and proprietary supplier scorecard outputs. The full report contains these granular, actionable datasets and interactive models—essential for tactical execution and financial projections.
Final note — decision calendar for 2026
For executives sizing capital projects, negotiating supplier contracts or evaluating M&A targets, timing is critical. Our analysis shows that choices made in the first and second quarters of 2026 on supplier qualification, capacity reservations and co‑development agreements will disproportionately influence 2027 outcomes. The report maps a practical decision calendar keyed to procurement cycles, trade shows and product launch windows to help teams convert strategic intent into measurable results.
Next step
Access the full PW Consulting Robot Joint Precision Reducers Market study for the proprietary models, supplier scorecards and executable playbooks that turn 2026 market trends into competitive advantage. The full deliverable equips strategy, procurement and product teams with the data and templates needed to act with confidence in a rapidly evolving market.
For detailed analysis of this topic, please visit the official page: Robot Joint Precision Reducers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


