



PW Consulting: Biomass Power Market poised for 6.89% CAGR through 2032

Biomass for Power Generation: Strategic Imperatives for 2026 Decision‑Makers
Executive summary
As the energy transition pivots from proof‑of‑concept projects to large‑scale deployment, biomass for power generation is reasserting itself as a commercially mature, policy‑sensitive segment of the low‑carbon electricity mix. Our latest market model—anchored on 2025 as the base year—shows the global biomass power market expanding at a compound annual growth rate of 6.89% through the 2026–2032 forecast window, moving from a 2025 market size of USD 111.8 Billion toward a materially larger global opportunity by 2032. This growth trajectory reflects persistent policy support, ongoing coal‑to‑biomass conversions, decarbonisation market signals, and incremental technology improvements that together make 2026 a pivotal planning year for developers, utilities, equipment vendors and financiers.
Biomass For Power Generation Market
Why this research matters for 2026 strategic decisions
- Timing capital allocation: With a robust near‑term growth profile, 2026 will be a key year to commit capital to projects that can leverage existing permitting windows, grid access and established supply chains.
- Policy arbitrage and incentives: Recent regulatory developments—especially in the United States—change the calculus for both greenfield projects and retrofits. Qualifying for technology‑neutral clean production credits or investment credits based on lifecycle emissions profiles materially alters project IRRs.
- Supply‑chain and feedstock risk management: Feedstock markets are tightening in some corridors even as densified biomass trade remains global. Buyers and project sponsors must move from spot purchasing to contractual security and blended sourcing strategies to protect margins.
- M&A and consolidation strategy: The sector’s low headline concentration (CR3 ~18.5%; CR5 ~24.2%) signals a fragmented competitive landscape—creating a prime window for scale‑seeking consolidation, vertical integration, or bolt‑on acquisitions to secure offtake and feedstock.
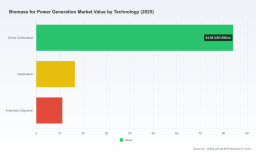
- Technology selection and decarbonisation strategy: With options spanning direct combustion, gasification, anaerobic digestion and CCUS integration, selecting the correct technology stack for a given feedstock and market will be a decisive value driver.
What this PW Consulting report delivers (practical, actionable content)
- Transparent market-sizing and scenario forecasts (2026–2032) with sensitivity runs for price, feedstock availability and permitting delays.
- Project‑level economics templates and LCOE benchmarking tailored to common plant sizes and technology pathways, enabling rapid financial triage of opportunities.
- Feedstock supply‑chain playbooks: procurement strategies, logistics optimisation, densification economics and certification risk maps.
- Regulatory and incentives compendium, including tax credit eligibility criteria and scenario assessments for policy shifts in major markets.
- Competitor intelligence dossiers covering strategic positioning, asset footprints, vertical integration, and likely M&A targets.
- Technology risk matrices and vendor shortlists for EPC, boiler and emissions control equipment, as well as CCUS retrofitting feasibility analyses.
- Deal structuring and financing templates highlighting optimal covenant structures, offtake contracts and sponsor equity profiles for 2026 market realities.
Competitive landscape — reading the tea leaves
The sector’s strategic map is composed of several archetypes that matter for how 2026 plays out:
Biomass For Power Generation Market
- Vertically integrated incumbents: Companies that pair large biopower fleets with captive fuel production or long‑term pellet supply arrangements are positioned to defend margins as feedstock cost volatility increases. Their playbook emphasizes scale, contract discipline and control of densification or pellet logistics.
- Utilities and major energy groups: Large utilities are converging on biomass as a dispatchable renewable to complement intermittent resources, with a focus on coal‑to‑biomass conversions and CHP integrations. These players bring balance‑sheet capacity but face reputational and sustainability scrutiny that requires robust lifecycle accounting.
- EPC and equipment specialists: Technology suppliers and engineering houses are moving up the value chain to offer performance guarantees, emissions compliance packages and retrofit pathways—critical for projects that aim to retrofit coal assets or integrate CCUS.
- Regional developers and integrators: Local champions in Asia, Latin America and Europe are executing projects that reflect local feedstock profiles and permitting realities. Their advantage is speed to market and local stakeholder networks.
- Feedstock specialists: Dedicated pellet and densified fuel producers are strategic partners or acquisition targets for sponsors seeking to secure long‑term feedstock and manage quality variation across supply sources.
Illustrative recent developments accentuate these themes: in 2025–2026 several notable deployments and capacity additions—from large new plant commissionings in Japan and Vietnam to the commissioning of new PKS processing capacity in Malaysia—show developers and equipment suppliers translating strategic commitments into operating assets. These moves underline the sector’s operational momentum and the immediate availability of projects for investors willing to move in 2026.
Biomass For Power Generation Market
Market dynamics to watch in 2026
- Feedstock pricing and logistics: Recent market data shows material spreads between domestic and export densified fuel prices, and localized gate costs for mixed mill and forest residues that should be modelled into project bids. Sponsors must incorporate these real‑world inputs when stress‑testing their fuel procurement strategies.
- Availability of policy credits: In several jurisdictions, qualifying for production or investment tax credits now depends on lifecycle GHG performance or emerging interpretations of carbon‑removal credits—creating a bifurcation in project economics between ‘credit‑qualified’ and ‘market‑only’ assets.
- Carbon policy expansion: Legislative developments proposing broader eligibility for carbon‑capture incentives to include forest residue products change the downstream economics of bioenergy‑with‑carbon‑removal options and wildfire‑mitigation projects.
- Project finance appetite: Appropriations and government support in 2026 are nudging banks and institutional lenders to view biomass as a policy‑aligned, financing‑worthy asset—provided developers can demonstrate robust sustainability credentials and supply‑chain traceability.
- Technology convergence: CCUS readiness, hybridisation with gas or hydrogen, and modular gasification are cross‑cutting trends that will separate near‑term winners from laggards.
How to use the PW Consulting intelligence in 2026 — recommended playbook
- Run rapid portfolio triage against our scenario set: Re‑score opportunities for policy sensitivity, feedstock security and technology fit to prioritise the top 20% of projects for capital allocation in 2026.
- Pursue vertical hedges: Evaluate selective backward integration—either via offtake‑anchored pellet contracts, equity stakes in feedstock processing, or long‑term tolling arrangements—to stabilise input costs.
- Structure incentives capture: Align project designs and lifecycle models to meet eligibility thresholds for production and investment credits where available; treat tax‑credit qualification as a determinant of project staging.
- Design modular and retrofit‑friendly technical approaches: For coal‑to‑biomass conversions and distributed CHP, prefer modularity and CCUS‑compatible layouts that preserve future upside optionality.
- Prepare for consolidation: Use the market’s fragmentation to pursue targeted M&A—accretive acquisitions of regional developers, pellet capacity, or EPC capabilities can accelerate scale and improve negotiating leverage.
- Operationalise sustainability and traceability: Embed third‑party certification, supply‑chain traceability and lifecycle GHG accounting into contracts to preserve access to both public incentives and private corporate offtakers.
Conclusion — the decision horizon for 2026
2026 represents a convergence year where policy windows, feedstock market developments and capital market appetite create asymmetric opportunities for sponsors who come prepared with deep technical, commercial and regulatory playbooks. Our market forecast and scenario analyses quantify a clear growth pathway, but the outcome for individual projects will hinge on policy eligibility, fuel procurement structures, and the ability to deploy scalable technologies that can be financed under tightened sustainability screens.
Next steps
PW Consulting’s full Biomass for Power Generation Market report provides the granular segmentation, regional and technology forecasts, a searchable project database and downloadable financial models you need to execute in 2026. The executive preview above highlights the strategic vantage points; the complete dataset contains the compartmentalised market splits, asset‑level economics and supplier scorecards that operational teams and C‑suite decision‑makers will use to convert strategy into deployed capital.
For detailed analysis of this topic, please visit the official page: Biomass For Power Generation Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


