



PW Consulting: P Series Glycol Ether Market to Reach USD 4,950M in 2025; 2026–32 CAGR 4.85%

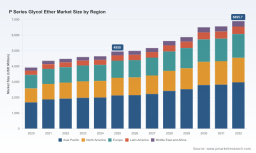
P Series Glycol Ether Market: Strategic Intelligence for Decision-Makers in 2026
Executive snapshot
In 2025 the global P Series glycol ether market reached an estimated USD 4,950 million (base year 2025). Our analysis projects a steady compound annual growth rate (CAGR) of 4.85% across the 2026–2032 forecast window, driving the market toward roughly USD 6.9 billion by 2032 under the central-case scenario. For leadership teams planning capital allocation, supply-chain adjustments, product portfolio moves, or M&A activity in 2026, these topline dynamics provide a quantitative framework that balances near-term volatility with multi-year structural growth.
P Series Glycol Ether Market
Why this study matters for 2026 decisions
-
Actionable timing: The short-term market environment is increasingly event-driven — operational disruptions, commodity swings and regulatory signals now exert outsized influence on margin, availability and pricing. Executives who align tactical moves (spot procurement, hedging, interim sourcing) with a clear multi-year strategy can preserve margin and optionality without sacrificing long-term growth exposure.
P Series Glycol Ether Market -
Portfolio prioritization: P Series glycol ethers remain essential solvents across coatings, electronics, cleaners and specialty industrial applications. Our study decodes where industrial demand will concentrate and where customers will prioritize performance, low-VOC/safety profiles and supply security — inputs that should govern capex and innovation budgets in 2026.
P Series Glycol Ether Market -
Risk-managed growth: The market’s mid-single-digit CAGR masks episodic supply tightness and feedstock swings. Companies that adopt scenario-driven capacity planning and layered procurement strategies will be best positioned to convert volatility into profitable share gains.
Market dynamics shaping 2026 strategy
-
Supply shocks and short-cycle price signals: Early 2026 saw material industry events that underline operational risk. A major Bayport facility fire prompted a force majeure declaration from a leading producer in March 2026, while at the same time another global producer announced price increases for P Series products. These twin developments illustrate how single-site incidents and coordinated pricing moves can rapidly tighten regional availability and push spot prices upward. Procurement teams must therefore build contingency playbooks to bridge weeks-to-months of disruption without cascading downstream outages.
-
Feedstock volatility: Propylene oxide (PO) is the primary upstream feedstock for P Series glycol ethers, produced by addition of PO to alcohols. Price behaviour in PO markets has been bifurcated; late-2025 indices showed Q4 weakness in some regions, while early-2026 benchmarks reflected a rebound (North American PO was reported near USD 1.14/kg in March 2026, up from December levels). The implication for buyers and producers is clear — margin sensitivity to PO must be modeled across rolling price scenarios, and where feasible, contracts should include transparent cost-pass-through mechanisms.
-
Regulatory inflection: Regulatory scrutiny has intensified. In late 2025 the EPA proposed Significant New Use Rules (SNURs) under TSCA for certain glycol-ether–related substances, signaling potential restrictions or new testing requirements. This creates near-term compliance costs and medium-term formulation risk for product lines that rely on legacy glycols. R&D and regulatory affairs budgets should be calibrated to accelerate safer-substitute development, defensible exposure assessments and expanded compliance monitoring in 2026.
-
Geographic production footprint: Western Europe retains an outsized role both as a producer and consumer region for P Series glycol ethers. That position influences global logistics, export flows and substitution levers; companies with flexible regional hubs will be better able to respond to demand shifts and regional policy changes.
Competitive landscape: implications for industry players
The P Series market remains moderately concentrated at the top, with the three largest producers accounting for a meaningful share and the top five amplifying that concentration further. This structure creates both competitive pressure and cooperative dynamics: leading producers exert price leadership and can mobilize capacity redeployment in response to disruptions, while midsize and regional players win via agility, niche product quality or localized service models.
-
Global majors: Dow, BASF, LyondellBasell, Eastman and Shell represent the classical integrated, scale-oriented competitors. Their advantage is breadth of production capacity, global distribution networks and ability to offer coordinated cost-pass-through or supply guarantees to large customers. The March 2026 price moves and force majeure event demonstrate how these players can influence short-term market mechanics — a strategic reality buyers and smaller suppliers must monitor closely.
-
Regional specialists and niche suppliers: Companies such as INEOS Oxide, KH Neochem, Chang Chun Group, Sasol and Solventis operate with regional depth, formulation know-how, or specialized grades tailored to electronics, inks or high-performance coatings. These players often win in customers’ development cycles where technical compatibility and regulatory compliance trump unit-cost advantages.
-
Strategic playbook by firm type: Scale players should prioritize resilient asset maintenance, forward hedging and selective premiumization of specialty grades. Regional/niche players should double down on technical services, co-development agreements and supply continuity guarantees to displace incumbent suppliers during shocks.
What the full report delivers (practical, non-theoretical)
-
Topline and scenario forecasts: A transparent base-case and two alternate scenarios (tight-supply / policy-constrained) for 2026–2032 with sensitivity tables that map price, feedstock and demand elasticity to revenue outcomes.
-
Supply-chain stress tests: Playbooks for procurement and manufacturing teams that quantify stock buffers, dual-sourcing thresholds and break-even points for spot purchases during capacity outages.
-
Regulatory impact matrix: An actionable roadmap that translates proposed TSCA/SNUR actions and other jurisdictional measures into product-level compliance steps, timelines and potential reformulation costs.
-
Commercial strategies: Segment-targeted go-to-market options (premiumization, reformulation, service/technical partnership models) and tactics to protect margin while chasing growth in targeted end-markets.
-
Competitor dossiers and benchmarking: Summaries of the major producers, their asset footprints, strategic moves, recent public actions and operational risk indicators — designed to support M&A screening and supplier selection without relying on committee-driven anecdotes.
-
Data packages and model templates: Downloadable financial models, procurement calculators and market-sizing workbooks that let internal teams re-run scenarios using client-specific cost structures and sales mixes.
How to convert insight into 2026 decisions
-
Procurement: Immediately stress-test key supplier contracts for force majeure exposure, renegotiate to include clearer cost-pass-through and ramp contingency clauses, and adopt layered sourcing (primary, secondary, emergency) with defined trigger thresholds.
-
Manufacturing and capex: Prioritize reliability investments in critical plants and evaluate modular debottlenecking projects that can be executed in 6–18 months to capture market opportunities created by competitors’ downtime.
-
R&D and compliance: Accelerate screening of low-risk solvent alternatives and invest in toxicology and exposure testing required by evolving regulatory frameworks. Early movers will reduce reformulation friction and retain share among customers who have strict regulatory demands.
-
M&A and portfolio: Use the quantified scenarios in the report to identify targets whose value is asymmetric under supply-constrained cases (e.g., small regional producers whose assets become strategically valuable during tight cycles).
-
Commercial: Implement tiered pricing and service packages that reward long-term contracts and volume commitments, while preserving optionality for spot exposure where margin upside is material.
Risk checklist for 2026 planners
-
Operational risk: Single-site incidents and under-maintained assets can produce outsized market effects; maintain live readiness plans.
-
Commodity risk: Model PO price swings and embed flexible pass-through or hedge instruments where warranted.
-
Regulatory risk: Monitor TSCA/SNUR timelines and prepare rapid-response regulatory dossiers to avoid customer delisting or market access delays.
-
Competitive risk: Track price leadership moves by majors and be ready to defend commercial relationships during supplier-led price adjustments.
Why PW Consulting’s P Series Glycol Ether Market study is a strategic asset
The study combines a disciplined macro-to-micro market-sizing approach with scenario modeling, supplier-risk scoring and executable playbooks geared toward 2026 priorities. We deliberately present high-confidence topline forecasts (base-year and CAGR) while preserving the competitive utility of our proprietary segmentation tables for registered users — the result is a report that gives you enough strategic intelligence to act decisively, but saves the granular tactical levers for the report delivery and client workshops where we can align recommendations to your P&L and operational cadence.
Next steps
For executive teams preparing 2026 budgets or rethinking their supply strategy, the full report and its accompanying data models provide the granular segmentation, supplier-by-supplier profiles, and downloadable templates that turn the scenarios above into executable 90–180 day plans. Contact our P Series practice to arrange a briefing, obtain the complete datasets, or commission a tailored stress-test using your cost and production parameters.
For detailed analysis of this topic, please visit the official page: P Series Glycol Ether Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


