



PW Consulting: Satellite Control Market to Hit USD 35,470M by 2032 at 7.45% CAGR

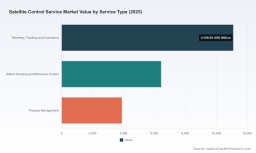
Satellite Control Service Market: Strategic Preview for 2026 Decision‑Makers
As PW Consulting’s Senior Strategy Advisor and Industry Lead, I present an executive preview of our Satellite Control Service Market study — a pragmatic guide designed to orient corporate strategy, procurement, and investment decisions in 2026. The market for satellite control services has moved from niche operations to a core component of commercial space value chains. Our baseline analysis shows the market expanding from roughly USD 15.2 billion in 2020 to about USD 21.45 billion in 2025, and we forecast continued growth to an estimated USD 35.47 billion by 2032 at a compound annual growth rate (CAGR) of approximately 7.45% across the forecast horizon. For leaders planning capital allocation, partner selection, or M&A activity in 2026, the choices made this year will determine who captures durable operational value as this market doubles in scale.
Satellite Control Service Market
Why 2026 Is a Strategic Inflection Point
Several concurrent forces converge in early 2026 to make this a decisive year for satellite control strategies:
Satellite Control Service Market
- Regulatory recalibration: major jurisdictions are moving to simplify licensing, widen spectrum access, and harmonize approvals for satellite infrastructure — creating windows for faster deployments and cross‑border commercial models.
- Operational economics: capital intensity for ground infrastructure remains high, but shared ground-station and GSaaS (Ground Station as a Service) models are rapidly maturing as a cost mitigation pathway for operators and new entrants.
- Technology and mission diversity: multi-orbit architectures and mixed constellations (LEO/MEO/GEO and beyond) increase complexity for telemetry, tracking and command (TT&C), driving demand for integrated ops platforms and resilient network fabrics.
- Competitive consolidation: market concentration metrics show a meaningful presence of scale incumbents alongside a growing cohort of specialist GSaaS providers and defense primes — creating both partner and competitor dynamics that must be navigated deliberately.
Taken together, these dynamics make 2026 the year to pivot from opportunistic experiments to repeatable operating models and resilient supplier strategies.
Satellite Control Service Market
What PW Consulting’s Study Delivers — Practical, Transaction‑Ready Intelligence
This report is built for operators, infrastructure investors, systems integrators, and advanced users of satellite services who need actionable outputs rather than abstract predictions. Key deliverables include:
- Market sizing and growth drivers: rigorous top‑down and bottom‑up models covering the market from 2020 through our 2026–2032 forecast window, with scenario variants reflecting regulatory, spectrum, and technology outcomes.
- Decision frameworks: procurement scorecards, supplier shortlisting criteria, and risk‑weighted TCO models that let you compare GSaaS versus in‑house station builds under multiple mission profiles.
- Operational blueprints: recommended architectures for multi‑orbit control, resilient TT&C routing, and disaster recovery for mission‑critical operations.
- Commercial playbooks: go‑to‑market templates for service bundling, pricing levers, and partnership structures tailored to commercial, government/military, and civil/scientific use cases.
- Vendor diagnostics: structured vendor scorecards and negotiation playbooks to quantify service coverage, latency, security posture, and escalation SLA tradeoffs.
- M&A and investment toolkit: due‑diligence checklists, synergy quantification models, and three stress‑test scenarios to evaluate targets and alliances.
- Regulatory tracker and spectrum impact map: an integrated view of near‑term regulatory proposals and their operational impact on licensing, spectrum availability, and infrastructure approvals.
The study combines quantitative forecasts with hands‑on tools you can adapt directly to purchasing cycles, board deliberations, and program roadmaps.
Competitive Landscape — Who Matters, and How to Position
The market exhibits a mix of incumbent operators, integrated systems houses, and specialized ground‑network providers. Concentration is material but not prohibitive — the largest three players control a meaningful share of market activity while the top five increase that presence further. This creates both power centers and plenty of tactical openings for niche providers and partnerships.
- Global ground‑network specialists (examples include leading regional GSaaS players): these firms anchor multi‑orbit TT&C and data acquisition through dense ground footprints and are advancing capability for lunar and deep‑space missions. Their strategic advantage is reliable, geographically diversified access and operational experience across mission profiles.
- Integrated satellite operators (major fleet operators and commercial broadcasters): these organizations leverage end‑to‑end control capabilities tied to their fleet economics. They trade some flexibility for strong coordination between flight operations and services monetization.
- Defense and prime systems houses (large aerospace and defense firms): these players bring hardened telemetry, security architectures, and mission assurance — a preferred option for government and military programs where compliance and continuity are decisive.
- New‑wave GSaaS and boutique operators : agile providers focus on API‑first access, developer support, and low‑friction on‑ramping for small satellite constellations. They are winning business where speed and integration matter more than legacy scale.
Recent industry moves underline these patterns: a leading GSaaS operator announced continued network expansion in early 2026 to reinforce multi‑orbit TT&C; an integrated operator released a results update reaffirming its global control capabilities; a major managed connectivity vendor secured a five‑year renewal supporting military network operations; and a constellation operator accelerated gateway deployments in late 2025 — all evidence of active investment on both infrastructure and service fronts.
Strategic Plays for 2026 — Practical Steps
- Adopt hybrid GSaaS/in‑house operating models. For most organizations, blended models deliver the best risk/return: outsource routine coverage and burst capacity, retain mission‑critical control and security domains in‑house.
- Lock-in regulatory and spectrum pathways. Prioritize engagements with regulators and spectrum holders now — policy changes in major markets are time‑sensitive and will materially affect deployment timelines and operating economics.
- Design for resilience and cyber‑assurance. Insist on hardened routing, cross‑provider redundancy, and end‑to‑end encryption and key management as preconditions for supplier selection.
- Use supplier scorecards to avoid lock‑in. Scorecards should quantify service diversity (multi‑orbit, multi‑antenna), restoration SLAs, and interoperability with third‑party mission control systems.
- Be opportunistic on M&A and partnerships. Look for acquisitions that add geographic ground coverage, API integration capability, or spectrum access; pursue commercial alliances to accelerate go‑to‑market while minimizing CAPEX.
How to Use This Study in Your 2026 Planning
Use the report as the single source of truth for three critical activities in 2026:
- CapEx and OpEx planning — use our TCO models to evaluate build vs buy under multiple utilization curves and spectrum scenarios.
- Supplier selection and contract design — apply our procurement templates and SLA matrices during RFQs to capture service continuity and upgrade pathways.
- Portfolio and M&A strategy — leverage our scenario analyses and vendor diagnostics to prioritize targets and quantify post‑merger integration risk.
Beyond the executive summary and trend narrative, the full study includes interactive dashboards, downloadable financial models, and a regulatory timeline you can embed into board materials and investment memoranda.
Closing — Where This Preview Leaves You
2026 is not a year to wait. The satellite control services market is scaling predictably and structurally — supported by policy shifts, GSaaS maturation, and mission diversity. Our study synthesizes these dynamics into decision‑ready outputs: models, scorecards, and roadmaps that help you move from strategy to execution without losing optionality.
This preview deliberately surfaces the analysis framework, headline market scale, and strategic recommendations while reserving the granular sub‑segment and regional split data for the full report. To access the segment‑level allocations, regional and service type breakdowns, vendor scorecards, and the interactive scenario models that underpin our recommendations, please consult the full report materials on the PW Consulting research page.
For detailed analysis of this topic, please visit the official page: Satellite Control Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


