



PW Consulting: Trial Process Management Market to Reach USD 6,880.83M by 2032 (13.18% CAGR)

Trial Process Management System Market: Strategic Briefing for 2026 Decision-Makers
As organizations recalibrate clinical development strategies in 2026, Trial Process Management (TPM) systems have shifted from “nice-to-have” operational tools to strategic infrastructure that directly impacts time-to-decision, regulatory risk, and trial economics. This briefing—drawn from PW Consulting’s latest market research—summarizes the high-level market trajectory, competitive dynamics, regulatory forces, and the pragmatic decision framework executive teams should use this year. It is designed to demonstrate the report’s analytical depth while preserving the proprietary segmentation and scoring that unlocks tactical plans in the full study.
Trial Process Management System Market
Market Trajectory: Scale and Growth Expectations
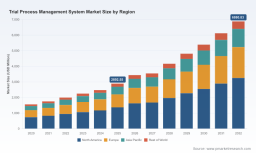
TPM adoption has accelerated through the 2020s. On a macro basis, the global TPM market more than doubled from its early‑decade baseline and reached nearly USD 2.9 billion in 2025 (base year). Looking forward, the market is projected to grow at a compound annual growth rate (CAGR) of around 13.2% over the 2026–2032 forecast window, reaching the mid‑single‑digit billions by the end of the period. That growth is being driven by a combination of platform modernization, cloud migration, regulatory tightening around data protection and electronic records, and the emergence of AI-enabled orchestration layers that promise to compress study build and execution cycles.
Trial Process Management System Market
Why This Matters for 2026 Decisions
- Cost-to-Operate vs. Speed-to-Market: With sponsors and CROs under pressure to shorten development timelines, TPM systems are now a lever both for operational cost control and schedule risk mitigation. The right platform choice influences monitoring frequency, query resolution times, and protocol adherence—metrics that materially affect study economics.
- Regulatory & Cyber Requirements: Emerging regulatory expectations (including tighter HIPAA security requirements and evolving GDPR guidance on data protection by design) make platform security and privacy engineering a board-level procurement criterion. Validation, encryption, and auditability are non‑negotiable.
- Vendor Differentiation through AI and Site Enablement: Vendors that combine core CTMS capabilities with AI for study build, risk-based monitoring, and virtual trial orchestration are moving from feature vendors to strategic partners.
- Integration as a Competitive Filter: Interoperability with EDC, EHR, safety databases, and finance systems determines whether a TPM investment delivers expected efficiency gains or becomes another silo that increases integration cost.
What the Full Report Delivers (Actionable Modules)
- Market sizing and a transparent forecast methodology (historical 2020–2025; forecast 2026–2032; base year 2025; USD, revenues in Millions).
- Segmented demand analysis across deployment modes, end‑user types, and regional markets—presented with scenario modelling and sensitivity to regulatory and technology shocks.
- Vendor landscape and comparative benchmarking: capability matrices, go‑to‑market positioning, integration readiness, product roadmaps, and M&A/partnership tracking.
- Implementation playbooks for sponsors, CROs, and sites: procurement checklists, validation timelines, pilot designs, change management templates, and TCO models that incorporate labor and cloud hosting realities.
- Risk register and compliance checklist aligned to current regulatory expectations (e.g., FDA 21 CFR Part 11, GDPR Art.25, HIPAA Privacy and Security Rule updates), plus recommended vendor contract clauses and BAA considerations.
- Commercial intelligence: pricing models, licensing benchmarks, and recommendations for outcome‑based contracting and vendor consolidation strategies.
Competitive Landscape: Strategic Positions and Near‑Term Moves
The TPM market is characterized by a mix of large platform integrators, specialized CTMS vendors, and service-heavy CROs that bundle TPM capabilities into broader offerings. Leading providers are pursuing distinct strategies that matter to buyers:
Trial Process Management System Market
- Veeva Systems —Continuing its enterprise platform focus, Veeva’s site‑oriented product introductions signal a dual approach: maintain strong sponsor/CRO footprint while enabling site adoption and data flow efficiency. Site-centric offerings that lower site burden can materially influence enrollment and source document timelines.
- Medidata (Dassault Systèmes) —An aggressive AI and orchestration strategy positions Medidata as a hub for study simulation, build automation, and real‑time optimization. Recent strategic partnerships and AI ecosystem announcements demonstrate a push to embed predictive and prescriptive intelligence across lifecycle stages.
- Oracle —With established enterprise implementations and recognized integration strengths, Oracle remains a default choice for organizations prioritizing depth of integration across EHR/EDC and regulatory compliance scaffolding.
- Advarra —Focused on academic and site networks, Advarra’s enhancements emphasize financial management, regulatory automation, and reporting—areas with immediate ROI for institutions that run high volumes of investigator‑initiated and academic trials.
- Parexel, IQVIA, Clario, RealTime, ArisGlobal, MasterControl —Each brings differentiated value: Parexel and IQVIA pair TPM with CRO services and broad data platforms; Clario targets endpoint and device-focused workflows; RealTime and Advarra strengthen site workflows; ArisGlobal and MasterControl cater to compliance‑heavy, regulated environments.
Recent vendor moves—strategic AI partnerships, product launches focused on site enablement, and enhanced analytics—signal a competitive phase where platform orchestration, AI augmentation, and site economics will determine leadership. Buyers should treat vendor roadmaps and AI safety guardrails as procurement deal‑breakers.
Regulatory and Operational Dynamics that Shape Vendor Selection
- Data Protection & Security: Proposed HIPAA Security Rule updates introduce mandatory encryption, routine vulnerability scanning, and annual penetration testing for entities processing ePHI—raising validation and continuous compliance costs for both cloud and hybrid implementations.
- Data Protection by Design: GDPR Article 25 increasingly constrains how TPM vendors manage identifiable health data. Buyers must require documented pseudonymization strategies, access minimization, and built‑in privacy controls in vendor due diligence.
- HIPAA Privacy Requirements: Expect more rigorous expectations around BAAs, minimum‑necessary access, and disclosure documentation when TPM vendors handle data on behalf of covered entities.
- Regulatory Records & Auditability: Standards such as FDA 21 CFR Part 11 and EMA guidelines remain central—platforms must support electronic signatures, secure audit trails, and validated system life‑cycle management.
- Operational Cost Drivers: Primary cost contributors are specialized labor for configuration, validation, and compliance monitoring, alongside cloud hosting fees that scale with data volume and integration complexity. These must be fully captured in TCO and ROI models.
Practical Guidance: Procurement & Implementation Priorities for 2026
- Adopt a risk‑based procurement scorecard that weights interoperability, AI maturity (with auditability), site ergonomics, and regulatory evidence over feature checklists.
- Build validation and compliance costs into budget cycles from Day‑1. Plan for continuous validation activities tied to security patching, AI model updates, and integration changes.
- Pilot for impact: run short, instrumented pilots focused on enrollment speed, query cycle time, and monitoring‑efficiency metrics. Use these to derive evidence for scaling and price negotiations.
- Negotiate outcome‑oriented terms where practical (e.g., migration credits tied to user adoption thresholds, service credits for integration SLAs, or shared savings for workflow automation gains).
- Prioritize vendors that publish explainability and monitoring tools for AI components—regulators and auditors increasingly expect governance artifacts for autonomous decision support.
- For site networks and academic centers, seek site‑friendly licensing and deployment models that minimize administrative burden and support multi‑sponsor collaboration.
Strategic Questions PW Consulting Helps Clients Answer
- Which TPM architecture (cloud‑native, hybrid, or on‑premise) minimizes TCO while satisfying near‑term compliance milestones?
- How to structure a phased rollout that delivers measurable operational wins within the first 12 months?
- What vendor partnership model—best‑of‑breed integrations vs. single‑vendor platforms—best aligns with our portfolio strategy and clinical complexity?
- How to score vendor AI propositions for safety, auditability, and real‑world impact on trial timelines?
- Which contract terms and KPIs should be non‑negotiable in an era of tighter data protection rules?
Our full Trial Process Management System Market report provides granular answers to these questions—complete with segmented demand tables, vendor scorecards, pricing benchmarks, implementation timelines, and downloadable procurement templates. The analysis blends quantitative market projection with qualitative vendor due diligence to support actionable 2026 roadmaps.
Next Steps
For executive teams planning TPM investments in 2026, the immediate priority is to align clinical, IT, privacy, and procurement stakeholders around a single, measurable set of objectives—then use that charter to evaluate vendors against the priorities and risks outlined above. PW Consulting’s full report and advisory engagements are designed to convert those objectives into negotiation strategies, validated implementation plans, and measurable KPIs that preserve study timelines while controlling compliance risk and operational cost.
Contact PW Consulting’s Life Sciences practice to access the complete market study, vendor benchmarks, and tailored advisory services that translate the market’s projected growth and vendor dynamics into a practical 12–36 month execution plan.
For detailed analysis of this topic, please visit the official page: Trial Process Management System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


