



PW Consulting: High-Precision Copper Foil Market — USD 21,167.3M by 2032, 8.64% CAGR

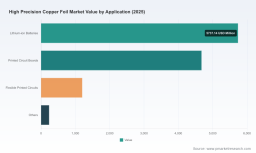
High Precision Copper Foil Market — Strategic Outlook for 2026 Decision‑Makers
Executive snapshot
PW Consulting’s High Precision Copper Foil Market study provides a strategic compass for companies that must make decisive capital, procurement and product choices in 2026. Using 2025 as the base year, our top‑line market model shows an industry that has grown materially through the 2020–2025 historical window and is forecast to continue expanding at a compound annual growth rate (CAGR) of 8.64% across the 2026–2032 horizon. In revenue terms (USD, Million), the market moves from a substantial 2025 base toward a materially larger addressable opportunity by 2032 — underpinning both near‑term tactical choices and multi‑year strategic investments.
High Precision Copper Foil Market
Why this study matters in 2026
-
Demand structuralization: The market is being reshaped by simultaneous secular forces — electrification of mobility, miniaturization and density increases in printed circuit boards, the growth of advanced AI and communications hardware that require ultra‑smooth, low‑roughness foils, and the continuing adoption of lithium‑ion and next‑generation battery formats. These trends are durable and create differentiated value pools for specific foil technologies.
High Precision Copper Foil Market -
Supply fragility and cost volatility: Raw material dynamics—most notably copper feedstock price volatility—are exerting a visible influence on cost structures and commercial behavior across the value chain. Producers have already signaled price adjustments in 2026, and upstream treatment/refining charge swings are introducing asymmetric risk to producers and buyers alike.
High Precision Copper Foil Market -
Regulatory and sustainability pressures: Advanced jurisdictions have tightened environmental requirements, pushing manufacturers to invest in emissions‑reduction measures, renewable energy sourcing and recycled copper usage. Compliance choices now directly affect capital planning, cost competitiveness and market access for certain high‑end applications.
-
Consolidation and niche specialization: The competitive landscape shows a mix of global leaders investing in ultra‑smooth and ultra‑thin technologies alongside regional specialists focusing on battery grade and flexible circuit applications. The market is neither a pure monopoly nor atomized: concentration metrics point to meaningful leadership but with room for differentiated entrants.
What PW Consulting’s report delivers (practical, decision‑ready content)
Our research is designed to be operationally useful to procurement, product leadership, corporate strategy and M&A teams. Key deliverables include:
-
An audited market‑size model (base year 2025) and a point‑by‑point forecast through 2032 with scenario variants tied to copper price paths, EV penetration curves and board design cycles.
-
Cost‑to‑produce and break‑even curves for electrodeposited versus rolled foil pathways, including sensitivity analysis to cathode price swings and energy cost assumptions.
-
Supplier heatmaps and capability matrices highlighting technology differentiators (ultra‑thin foils, ultra‑smooth surfaces, precision thickness control), facility footprints and recent capacity moves.
-
Commercial playbooks for procurement teams: hedging trigger points, contract structures, acceptable lead‑time buffers and escalation clauses to protect against rapid raw material-driven price moves.
-
Regulatory and sustainability impact matrix: capital expenditure implications of emissions requirements, recommended carbon reduction investments and payback estimates under multiple policy regimes.
-
M&A and partnership diagnostic: target profiles, valuation sensitivities and integration checklists for buyers seeking either vertical integration into rolling/electrolytic production or bolt‑on specialty capability.
-
Go‑to‑market playbooks for technology owners: product positioning, co‑development pathways with OEMs (batteries, AI accelerators, HDI boards) and specification negotiation templates.
Competitive landscape — what leading players signal for 2026
The industry map is populated by long‑established materials houses and focused specialty suppliers. Leading firms distinguish themselves through IP in ultra‑smooth and ultra‑thin foil production, control of critical process steps, and targeted capacity investments.
-
Mitsui Mining & Smelting (Mitsui Kinzoku) continues to pursue premium MicroThin and ultra‑smooth product strategies and has signaled commercial price increases in early 2026 while rolling out capacity expansions for its proprietary VSP™ technology. These moves underscore a willingness to defend margins and to scale proprietary, high‑value products.
-
JX Nippon and Furukawa maintain technology‑led positions in both electrodeposited and rolled foils, emphasizing precision thickness control and high‑frequency performance—areas where end‑users are increasingly willing to pay for demonstrable technical advantage.
-
European and regional specialists such as Circuit Foil Luxembourg, Wieland (rolled foil) and Solus are doubling down on tight‑tolerance and ultra‑low roughness niches, supporting high‑frequency and AI accelerator applications where surface quality is a commercial differentiator.
-
Asian manufacturers, including established and emerging Chinese, Korean and Taiwanese firms, are strategically important to global supply given their large manufacturing footprints and accelerating capability upgrades directed at both battery grade and high‑precision electronics segments.
Market concentration metrics indicate a moderate-but-meaningful level of aggregation among the top players. This structure produces competitive dynamics where technology leadership and commercial agility matter as much as scale—creating opportunities for focused entrants to win niche premium positions while larger players protect broadscale OEM relationships.
Recent market signals executives must heed in 2026
-
Price actions by major suppliers in early 2026 reflect immediate margin pressure from raw material and labor costs; commercial teams should expect further supplier‑initiated repricing unless copper feedstock trajectories moderate.
-
Capacity investments announced by technology leaders indicate a deliberate move to capture growing volumes in ultra‑smooth and ultra‑thin segments; late entrants should assess the risk of downward pressure on premium spreads if capacity growth outpaces niche demand.
-
Product portfolio refreshes and updated catalogs point to rapid iteration in tolerance and surface finish specifications—buyers must update qualification processes to avoid supply constraints on next‑generation designs.
Strategic imperatives & recommended actions for 2026
To translate market intelligence into competitive advantage, executive teams should prioritize a mix of defensive and offensive moves:
-
Build a procurement “early warning” system tied to raw material and supplier signals. Define contract escalation clauses and a hedging playbook tied to specific copper price thresholds and supplier liquidity signals.
-
Reassess product roadmaps: accelerate co‑development with foil suppliers on ultra‑thin/ultra‑smooth specifications where willingness‑to‑pay is demonstrable; defer commoditized transitions where margin erosion risk is high.
-
Calibrate capacity investments to scenario outcomes. Use PW Consulting’s demand‑by‑application scenarios to time capacity additions and to size them for premium versus commodity mixes.
-
Pursue supply diversification and dual‑sourcing for critical specifications. Where performance risk is high (AI accelerators, certain battery foils), secure qualification of at least two geographically diverse suppliers.
-
Embed sustainability as a commercial differentiator: investments in recycled copper sourcing and renewable energy not only mitigate regulatory risk but are increasingly requested by OEM procurement teams.
-
Explore targeted M&A to acquire specialty capabilities rather than broadscale volume. The most accretive deals in the near term will be technology or specification plays that shorten time‑to‑market for premium applications.
How to use this study in 90 days
-
Procurement: implement the supplier scorecard and commence renegotiation pilots with top suppliers using the price‑trigger templates in the report.
-
R&D/Product: run a technical gap analysis against the foil technology roadmaps and prioritize two co‑development projects for ultra‑thin/ultra‑smooth foils.
-
Corporate Strategy: model two M&A scenarios using the report’s valuation sensitivities and target lists; commence discreet outreach if criteria match.
Next steps and access to the full intelligence
The analysis above demonstrates the type of strategic depth PW Consulting brings to high precision copper foil decisions in 2026. The full report contains proprietary, transaction‑grade intelligence — including detailed segmentation by application and region, supplier scorecards, precise cost curves, and downloadable scenario models — intentionally withheld here to preserve the commercial utility of our subscription offering.
Reach out to PW Consulting to obtain the full dataset, supplier benchmarking tables, and the model templates you can deploy immediately to stress‑test 2026 investment and procurement decisions.
For detailed analysis of this topic, please visit the official page: High Precision Copper Foil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


