



PW Consulting: Liquid Phenolic Resin Market at USD 7,411.35M in 2025; 5.01% CAGR (2026–2032)

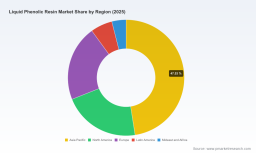
Liquid Phenolic Resin Market 2026: Strategic Compass for Executive Decisions
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present an executive primer on the Liquid Phenolic Resin market that frames the strategic choices facing manufacturers, downstream integrators, investors and policy teams in 2026. This is a forward-looking, decision-focused synopsis designed to show the analytical depth of our full study while preserving the detailed segment tables and proprietary models that drive prescriptive action. Consider this a high-resolution map with the detailed coordinates available in the full report.
Liquid Phenolic Resin Market
Why this market matters to 2026 strategy
Liquid phenolic resins sit at an intersection of durable-goods manufacturing, construction materials, automotive lightweighting and high-temperature industrial processing. Between 2020 and 2025 the global market expanded materially, reflecting recovery in construction and targeted industrial demand. Our base-year sizing indicates a market of USD 7,411.35 Million in 2025. Looking forward, our forecast model projects the market will grow at a compounded annual rate of 5.01% across the 2026–2032 horizon, reaching approximately USD 10,435.47 Million by 2032. That growth trajectory creates a multi-year runway for strategic investment but also raises stakes around feedstock exposure, regulatory compliance and competitive positioning.
Liquid Phenolic Resin Market
Five structural dynamics shaping decision trade-offs
-
Demand diversification vs. concentration risk. End-use demand drivers (construction, insulation, foundry, laminates/coatings and friction materials) are uneven in cyclical sensitivity and margin profile. Firms must balance investments toward higher-growth structural uses—such as advanced composites for automotive lightweighting—with the steady base provided by traditional wood product and refractory markets.
Liquid Phenolic Resin Market -
Raw material volatility and cost pass-through. Phenol is the principal upstream feedstock. Pricing signals through early 2026 demonstrate renewed tightening: Northeast Asia phenol spot prices reached about USD 1.01/kg in March 2026 (an 8.6% increase from December 2025 and a 3.1% monthly rise), pressured by maintenance outages and stronger downstream resin operating rates. These dynamics mean feedstock hedging, bilateral supply agreements and flexible formulation strategies are now core commercial capabilities.
-
Regulatory and sustainability premium. Stricter formaldehyde emission standards and related air quality regulations are elevating compliance costs—our synthesis of region-level regulatory impact models indicates compliance-driven cost increases in the neighborhood of 8–12% for producers of conventional formulations. Concurrently, buyers increasingly prize certified low-emission and circular-material variants, creating a dual imperative: regulatory compliance and product differentiation through sustainability credentials (e.g., ISCC PLUS).
-
Supply-chain fragmentation and geopolitics. The sector shows moderate aggregation at the top: our concentration analysis indicates the market remains neither fully consolidated nor atomized (three-company concentration and five-company concentration metrics point to a moderate-leading-player landscape). Tariff actions, such as U.S. reciprocal measures implemented in 2025 that affected certain resin-related imports, can abruptly shift cost competitiveness and reroute trade flows, incentivizing nearshoring and multi-regional footprints.
-
Product and process innovation as margin lever. Incremental improvements—lower-emission resoles, waterborne systems, and process yields—translate directly into commercial share when paired with robust application development (e.g., adhesives with reduced formaldehyde release for engineered wood). Certification achievements and validated sustainability claims materially accelerate buyer adoption in Europe and premium segments.
Competitive landscape: strategic implications for incumbent and new entrants
The competitive set combines global chemical integrators, regionally specialized producers and technically focused toll manufacturers. Key strategic archetypes we analyzed include:
-
Global integrators: Companies with large-scale, vertically integrated chemical platforms and global distribution capability are positioned to absorb feedstock volatility, invest in low-emission product lines and offer bundled solutions to large OEMs. Their strategic options include selective capacity expansion in growth corridors and value-capture via downstream formulation licensing.
-
Regional specialists: European-focused and Asia-specialized players emphasize proximity to key customers and regulatory competence. Their competitive edge is speed-to-market for region-specific formulations and certification services; their primary strategic vulnerabilities are feedstock import exposure and limited scale when competing for global OEM contracts.
-
Custom and toll producers: Dedicated contract manufacturers and ISO-certified tollers provide flexible small-batch supply and rapid formulation iteration—an attractive route for engineering houses and mid-sized firms seeking lower capital intensity. Scaling these relationships into longer-term partnerships is an underutilized strategy for premium capture.
Representative firm-level observations from our review:
-
Hexion Inc. – Broad resoles capability and global reach make it a natural supply partner for multi-national wood and composites OEMs. Strategy: deepen value-added adhesive platforms and negotiate long-term phenol-offtake arrangements to shield margins.
-
Prefere Resins Holding GmbH – European specialization gives it regulatory fluency; prioritize certification-led differentiation and selective capacity to serve higher-margin construction and insulation segments.
-
Sumitomo Bakelite – The company’s ISCC PLUS certification (achieved in late 2025 for some operations) is a strategic advantage in European sustainability-conscious markets; accelerate certified-supply commercialization and target automotive electronics and coatings customers that value circularity.
-
BASF and DIC – Large-scale integration enables aggressive product development; opportunity lies in leveraging BASF’s downstream formulation assets and DIC’s Asian expansions to capture premium industrial applications.
-
Capital Resin, Georgia-Pacific Chemicals, Bakelite Synthetics, Jinan Shengquan, SI Group – These players represent a mix of contract manufacturing strength, regional volume supply and technical niche expertise. Their strategic move sets include expanding tolling footprint, consolidating regional supply agreements, and aligning product roadmaps with OEM decarbonization goals.
What our full study delivers (practical, transaction-ready content)
The PW Consulting report is structured to convert insight into action. Key operational and strategic deliverables include:
- Validated market sizing and multi-scenario forecasts (base and upside iterations) covering 2020–2032 with our 2025 base year and 2026–2032 projection horizon.
- Feedstock price modeling and sensitivity matrices showing margin exposure across pricing, tariff and regulatory shock scenarios.
- Regulatory impact assessment and compliance-cost playbooks for major jurisdictions—detailing engineering, formulation and certification pathways to meet formaldehyde and related standards.
- Competitive benchmarking with playbook recommendations by strategic archetype (scale integrator, regional specialist, toll manufacturer).
- Deal pipeline: prioritized M&A targets and partnership hypotheses, screening using synergies, capacity fit and regulatory exposure.
- Commercial go-to-market templates for premium positioning (sustainability certification, low-emission claims, co-development with OEMs).
- Operational recommendations on capacity siting, tolling partnerships, and raw material logistics hedging.
Note: This preview deliberately omits granular regional and application-split tables and the proprietary unit economics that underpin our buy/sell recommendations—these are available in the full report and interactive data annex.
Actionable recommendations for 2026 planning cycles
-
Hedge and diversify phenol exposure. Lock incremental phenol volumes through multi-year contracts in tandem with flexible formula options to protect margins during episodic price spikes.
-
Prioritize low-emission formulations and certification. Dedicate R&D and capital to bring ISCC PLUS–compatible and low-formaldehyde product lines to market; certification accelerates market access in Europe and premium OEM segments.
-
Reassess footprint under tariff risk. Evaluate nearshoring or regional manufacturing agreements in response to trade measures that can impose up to meaningful tariff levels; consider tolling partnerships to maintain customer continuity.
-
Use M&A and partnerships to buy capabilities. Acquire or partner for formulation know-how, certification pipelines and local regulatory expertise rather than relying solely on organic development—this shortens time-to-revenue.
-
Implement dynamic pricing linked to feedstock indices. Where contract structures allow, adopt transparent indexation to pass-through material cost swings while preserving customer relationships.
Closing perspective
The liquid phenolic resin market presents a balanced risk-reward profile for 2026 decision-makers: predictable, mid-single-digit growth aggregated at the global level but with concentrated value creation available to players who manage feedstock volatility, regulatory compliance and product differentiation. Our full PW Consulting market study converts the broad opportunities highlighted above into executable strategies, quantified scenarios and a prioritized action plan tailored to your role—supplier, OEM, investor or policy advisor. For the numerical tables, segment-level economics and the interactive decision-support model that power the tactical recommendations in this brief, please consult the full report via PW Consulting’s research portal.
For detailed analysis of this topic, please visit the official page: Liquid Phenolic Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


