



PW Consulting: Residential Solar Market Poised for 14.02% CAGR Through 2032

Residential Solar Power Solution Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
As governments, utilities and homeowners accelerate distributed energy adoption, the residential solar market has moved from niche system installs to a mainstream capital and policy battleground. Our updated market model shows the global residential solar power solutions market nearly doubling from an estimated USD 61.4 Billion in 2020 to USD 128.19 Billion in 2025, and continuing on a robust trajectory under our base-case assumptions. We forecast an average compound annual growth rate of 14.02% into the 2026–2032 period, with a projected market size exceeding USD 320 Billion by 2032. These headline numbers frame why 2026 is a pivotal year for positioning: momentum is clear, but the competitive and regulatory environment is shifting rapidly enough to reshape winners and losers.
Residential Solar Power Solution Market
Why this research matters for boardrooms in 2026
- Timing of strategic moves: With multi-year expansion built into the market, incremental capacity additions alone will not secure sustainable margin expansion. Boards must decide whether to invest in scale, vertical integration, product premiumization, or services-led models—each path requires different near-term capital and partnership choices.
- Regulatory inflection points: Policy changes and trade measures are already altering cost dynamics and supply choices. Our research isolates the commercial impact of recent tax and trade developments and quantifies alternative scenarios so executives can price risks into contracts and capital plans.
- Channel and consumer economics: As rooftop buyers shift expectations (tariff arbitrage, resilience, total cost of ownership), companies that redesign sales funnels and after-sales services will capture disproportionate value. This report provides the decision-grade evidence to prioritize those investments.
Market trajectory and the assumptions that matter
Between 2020 and 2025 the residential solar market more than doubled in revenue terms, a reflection of improving panel and inverter economics, rising homeowner interest in energy independence, and policy-driven deployment in multiple markets. Our projections for 2026–2032 incorporate three linked assumptions: continued module efficiency gains and cost declines, progressive electrification of homes, and a mixed regulatory environment that includes trade remedies and episodic subsidy adjustments. Under these assumptions the market sustains a mid-teens CAGR—translating into a market more than two times its 2025 size by the end of our forecast window.
Residential Solar Power Solution Market
Importantly, our modelling layers in scenario sensitivity for raw-material shocks, subsidy removal, and tariff disruptions—each of which can compress or expand near-term revenue by material margins. For executives, the practical implication is that capital allocation must be flexible and hedged against policy swings and input-price volatility.
Residential Solar Power Solution Market
Key industry dynamics shaping 2026 strategic choices
- Input cost volatility: Polysilicon spot prices rose materially in early 2025, reflecting supply constraints and cyclical demand. The knock-on effect is visible across module pricing and OEM margins—our scenario analysis shows how short-term spikes can reallocate margin pools across the value chain.
- Shifting subsidy and tax landscapes: Notable policy shifts—such as the termination of the U.S. residential tax credit for systems placed in service after December 31, 2025—reconfigure project economics for a significant buyer cohort. Our regulatory impact matrix quantifies which customer segments and geographies suffer most and where commercial models must pivot (e.g., lease-to-own, community-shared models, or bundled storage incentives).
- Trade and duties: Quotas and duty measures, including recent CBP actions and preliminary antidumping determinations affecting certain supply routes, are already influencing procurement strategies. Our procurement playbook outlines how to re-route sourcing, negotiate volume protections, and structure long-term supply contracts under elevated trade risk.
- System cost benchmarks: Recent independent benchmarks indicate U.S. residential system pricing clustered in a narrow band of $3.2–$4.2/Wdc in 2025. When combined with local tariff and cross-border cost impacts, those unit economics translate directly into regional payback windows and finance availability. We model financeable IRRs for a variety of buyer profiles in the full report.
Competitive landscape — who to watch and why
The residential solar ecosystem blends module manufacturers, inverter and power electronics specialists, energy storage integrators, and vertically integrated home-energy brands. Market concentration remains moderate: the top three players control roughly 34.5% of the market by revenue, while the top five account for about 42.8%. This structure produces both opportunities for scale-driven incumbents and niches where differentiated technology or service plays can thrive.
- High-volume module leaders: Firms with massive module shipments and vertically integrated wafer-to-module capabilities are competing aggressively on price and efficiency. Their continued investment in N-type and high-efficiency monocrystalline technology is lowering levelized cost of energy for rooftop systems and imposing pressure on smaller module suppliers.
- Performance and integration players: Companies focused on inverter optimization, microinverters, and integrated storage-plus-control stacks are creating higher-value propositions for homeowners. These firms are winning on customer experience and O&M economics, not just upfront price.
- Premium systems brands: A subset of providers combines differentiated panel tech, branded storage, and a direct-to-consumer sales channel to capture higher margins—appealing to customers prioritizing aesthetics, performance, and integrated software services.
In the detailed company profiles we benchmark product roadmaps, production footprints, channel strength, and balance-sheet resilience. That analysis highlights which suppliers are best positioned to expand share organically, and which present attractive M&A targets for system integrators seeking supply assurance or vertical capability.
What the full PW Consulting report delivers
This research is designed to be operational from day one for corporate strategists, M&A teams, and commercial leaders. Key deliverables include:
- Proprietary market model with annualized revenue estimates from 2020 through 2032 and scenario toggles for raw-material, trade and policy shocks;
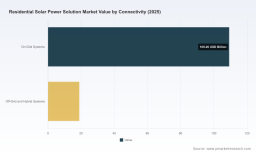
- Actionable segmentation framework by product architecture, connectivity (on-grid vs hybrid/off-grid), and commercial channels with clear implications for pricing and unit economics (note: we intentionally withhold the granular segment tables in this preview);
- Competitive benchmarking covering technology, manufacturing scale, and channel reach for leading module and inverter makers, plus supplier scorecards and supplier risk heatmaps;
- Go-to-market playbooks by region for installers, utilities and new entrants, including customer acquisition cost benchmarks and financing structures optimized for 2026 realities;
- Regulatory and trade impact matrices that translate recent CBP, DOC, and tax policy developments into revenue-at-risk and contingency actions;
- M&A and partnership roadmaps including target archetypes, valuation sensitivities, and integration checklists;
- Operational checklists for procurement, inventory hedging and inventory-to-order conversion strategies under volatile polysilicon and upstream pricing.
Strategic implications and recommended executive actions for 2026
- Hedge supply but prioritize flexibility: Locking in component volumes via long-term agreements can stabilize margins, but overly rigid contracts increase exposure to efficiency improvements and price declines. Structure agreements with price collars, capacity options and pass-through clauses tied to vetted indices.
- Pivot to value beyond modules: Margins are migrating toward system-level integration—software, storage and lifecycle services. Invest selectively in customer-facing software, O&M platforms, and bundled financing to capture lifetime value.
- Adopt a multi-scenario playbook: Given policy volatility, develop at least three go-to-market plans (accelerate, defend, consolidate) calibrated to subsidy and trade outcomes. Each plan should have predefined trigger points tied to regulatory announcements or commodity movements.
- Targeted M&A to fill capability gaps: Use M&A to acquire software, storage, or distribution capabilities rather than duplicating expensive manufacturing scale unless compelling cost synergies exist.
- Customer segmentation by economics, not geography: Prioritize buyer segments with favorable payback periods and financeability. We show how to re-rank territories based on end-customer economics rather than headline install volumes.
How to use this preview
This preview is intentionally selective: it demonstrates the analytical depth and strategic framing PW Consulting provides, while reserving the granular segment tables, detailed company scorecards, and downloadable data models for the full report package. If your 2026 plans depend on precise segment forecasts, supplier risk scores, or deal-level valuation sensitivities, the full dataset and model controls will be required to operationalize the scenarios we outline here.
Next steps and where to find the full intelligence
For executives ready to move from insight to action, PW Consulting offers a suite of advisory options: bespoke scenario workshops, procurement and hedging playbook execution, and diligence-led M&A support. To access the full Residential Solar Power Solution Market report, including downloadable Excel models, segmentation tables, and the complete competitive scorecards, please visit our report page. The full package contains the detailed intelligence necessary to convert the strategic implications above into execution-ready plans for 2026.
For detailed analysis of this topic, please visit the official page: Residential Solar Power Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


