



PW Consulting: 2,5-Dimethyl-2,4-Hexadiene Market to Reach USD 57.83 Million by 2032 at 4.51% CAGR

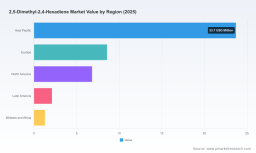
2,5-Dimethyl-2,4-Hexadiene Market — Strategic Preview for 2026 Decision-Making
As companies calibrate strategy for 2026, the 2,5-Dimethyl-2,4-Hexadiene market presents a clear, yet nuanced opportunity set. PW Consulting’s latest market study—anchored on a 2025 base year and projecting through 2032—maps a steady growth trajectory underpinned by specialty chemistry demand, upstream feedstock dynamics, and a concentrated supplier base. This preview synthesizes the strategic implications you need to act in 2026 without disclosing the segmented datapoints reserved for subscribers to the full study.
2,5-Dimethyl-2,4-Hexadiene Market
Market posture and headline metrics
The market has moved from a niche laboratory reagent to a commercially relevant intermediate across several value chains. Our base-year assessment (2025) benchmarks market size and projects expansion to the end of the forecast period (2032) at a compound annual growth rate (CAGR) of 4.51%. This steady expansion reflects the confluence of incremental demand from agrochemical synthesis, selective growth in flavor & fragrance intermediates, and continued use in specialty organic synthesis applications.
2,5-Dimethyl-2,4-Hexadiene Market
Supply-side structure amplifies strategic considerations: the market displays a high degree of concentration — top-three producers account for roughly two-thirds of supply, and the top-five capture more than four-fifths of the market. Such concentration creates both risks (single-source exposure, pricing power) and opportunities (consolidation, partnership, and premiumization strategies).
2,5-Dimethyl-2,4-Hexadiene Market
Why this research matters for 2026 corporate decisions
- Procurement and cost control: The product’s upstream reliance on C4 hydrocarbon derivatives (notably isobutylene and isobutyraldehyde) links its cost structure to petrochemical feedstock cycles. Our report translates feedstock volatility into procurement hedging playbooks and timing guidance that can reduce raw material spend and inventory risk.
- Supply-risk mitigation: Given the market’s concentration and the mix of global specialty distributors and China-based traders/manufacturers, 2026 decisions should prioritize second-source validation, quality audits, and contractual protections. The full study outlines supplier stratification and a staged on-ramp for qualification.
- R&D and product positioning: Purity differentiation is a practical lever. Manufacturers and formulators will need clear purity roadmaps to compete in premium segments (research-grade vs. technical intermediates). Our analysis links purity tiers to end-use economics and margin implications.
- M&A and partnership targeting: Market concentration makes bolt-on acquisitions and strategic alliances efficient routes to quickly expand capability or secure feedstock. The full report identifies candidate profiles and valuation benchmarks aligned to different strategic objectives.
Operationally relevant insights (what the full report delivers)
PW Consulting’s comprehensive study is designed for functional leaders—procurement, business development, R&D, and corporate strategy. Key practical modules include:
- Market sizing and rigorous methodology notes explaining how we reconcile supplier shipment data, distributor flows, and end-use demand models to produce the base-year and forecast totals.
- Scenario-based forecasts (baseline, upside, downside) that translate macro drivers—feedstock pricing, regulatory shifts, and application demand—into quantitative outcome ranges for 2026–2032.
- Supply chain mapping from petrochemical C4 streams through intermediate processing to finished reagent delivery, including lead-time profiles and capacity utilization indicators.
- Purity and formulation segmentation frameworks that connect technical specifications to procurement checklists and quality assurance protocols.
- Commercial playbooks for procurement (contract terms, lot-sizing, safety stock), go-to-market for suppliers (pricing, packaging, regulatory compliance), and growth plans for entrants seeking to scale beyond laboratory volumes.
- Competitive intelligence dossiers on suppliers, including distribution models (lab pack vs bulk), capability assessments, and risk matrices for single-source exposures.
Competitive landscape — practical takeaways
The supplier universe blends established global specialty-chemical distributors with regional manufacturers and traders. Understanding the different commercial archetypes is essential for 2026 strategy:
- Global specialty distributors (trusted brand, controlled supply): Large, certified distributors supply research-grade material in small-package formats and invest in documentation and compliance that many corporate R&D functions require. Examples include well-known Japanese and European firms that position product as stabilized, quality-assured reagents suitable for laboratories and controlled synthesis.
- Regional manufacturers and traders (scale and price competitiveness): Several China-based manufacturers and traders offer higher-purity material and multiple packaging options spanning gram lab packs to industrial drums and bulk. These players compete on cost and scale but vary significantly in documentation, supply chain transparency, and lead time.
- US-based distributors (laboratory-to-industrial bridge): North American speciality chemical distributors provide a blend of quality assurance and logistics convenience for Western buyers, often acting as the bridge when regional manufacturing needs to be scaled or when certification is prioritized.
Strategically, buyers seeking reliability and compliance should prioritize suppliers with robust quality documentation and stable logistics networks, while cost-sensitive scale buyers should evaluate targeted qualification programs with select regional manufacturers. Suppliers looking to capture premium segments should invest in consistent purity guarantees, stabilized formulations, and small-package channels for research customers.
Upstream dynamics and technology considerations
The synthesis pathway of 2,5-Dimethyl-2,4-Hexadiene commonly employed in industrial practice traces back to acid-catalyzed condensations involving C4 feedstocks—historical patents and technical literature continue to inform process chemistry choices. In practice, isobutylene (or tert-butanol) and isobutyraldehyde are the frequent upstream inputs drawn from C4 streams in refining and petrochemical operations.
These upstream linkages mean that refinery throughput, cracker configurations, and C4 stream allocations materially affect availability and cost. For manufacturers, strategies that consider backward integration, strategic off-take contracts, or co-location with petrochemical clusters can produce meaningful margin benefits. For buyers, developing alternative sourcing routes and maintaining agile material specifications (allowing slightly broader purity windows when feasible) can reduce lead-time and cost exposure.
Regulatory and quality risk profile
As a commodity moving between research and industrial use, regulatory compliance, impurity control, and documentation (MSDS, certificates of analysis, residual solvent profiling) are critical. Strategic priorities for 2026 should include:
- Enhanced supplier audits that evaluate not only product purity but also stabilization practices (antioxidants such as BHT), storage, and transport conditions.
- Contract clauses addressing change-of-origin, minimum quality thresholds, and remediation steps for off-spec deliveries.
- Investments by suppliers in traceability and third-party testing to command a premium in regulated or quality-sensitive segments.
Strategic recommendations for 2026
- Adopt a two-tier sourcing strategy: secure a compliance-certified supplier for critical research and regulated applications, and cultivate validated regional supply for scale-intensive operations.
- Pursue limited backward-integration studies where feasible; even partial integration into C4 derivative streams or strategic off-takes can hedge against feedstock volatility.
- Prioritize purity-driven product roadmaps: define clear purity-to-price thresholds and align internal specifications with supplier capabilities to avoid overpaying for unnecessary purity in industrial-use cases.
- Use the market’s concentration to negotiate staged exclusivity or capacity reservation agreements with leading suppliers, while maintaining parallel qualification tracks to avoid single-source dependency.
- For suppliers and investors: evaluate bolt-on acquisitions in regions where logistics or regulatory compliance gaps create barriers to entry—such deals can rapidly expand addressable markets.
Conclusion — the value of deep, operational intelligence
For 2026 decision makers, the choices around sourcing, product development, and commercial positioning in the 2,5-Dimethyl-2,4-Hexadiene market are both time-sensitive and high-impact. PW Consulting’s full report converts market-level growth (2025 base to 2032 forecast at a mid-single-digit CAGR) and concentration dynamics into executable plans: procurement playbooks, supplier scorecards, scenario-modeled forecasts, and prioritized strategic initiatives. This preview highlights the levers; the complete study supplies the segmented analyses, quantitative benchmarks, and supplier-level dossiers you need to operationalize these recommendations.
To access the full set of segmented data, supplier profiles, and step-by-step implementation guides that underpin these insights, please visit the report landing page for subscription and single-purchase options.
For detailed analysis of this topic, please visit the official page: 2,5-Dimethyl-2,4-Hexadiene Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


