



Disposable Hemoperfusion Cartridge Market to Hit USD 1,547.6M by 2032 at 9.02% CAGR

Disposable Hemoperfusion Cartridge Market — Strategic Preview for 2026 Decision‑Makers
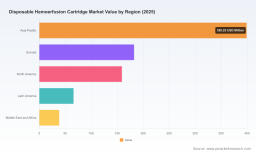
As health systems recalibrate critical care pathways and medtech players seek resilient growth levers, disposable hemoperfusion cartridges are emerging from a niche therapy into a strategically important consumables category. PW Consulting’s market model shows the global disposable hemoperfusion cartridge market at approximately USD 845.5 Million in the 2025 base year, and expanding at a compound annual growth rate (CAGR) of about 9.02% across the 2026–2032 forecast window. By 2032, our baseline scenario projects a market approaching the mid‑billion dollar range—illustrating durable demand driven by broadening clinical use, regulatory momentum, and supply‑side scaling.
Disposable Hemoerfusion Cartridge Market
Why this briefing matters for 2026 strategy
-
Timing for regulatory engagement is critical. Several market leaders are actively pursuing regulatory pathways and expanded indications; early, evidence‑led engagement with regulators materially shortens time‑to‑market for new therapeutic claims and hospital adoption.
Disposable Hemoerfusion Cartridge Market -
Supply chain and capacity decisions made in 2026 will determine who can meet accelerated hospital procurement cycles in 2027–2029. Automated, high‑volume manufacturing creates a durable cost and lead‑time advantage.
Disposable Hemoerfusion Cartridge Market -
Competition is consolidating around a small set of specialized incumbents; understanding competitive positioning and clinical differentiation will inform M&A, licensing, and distribution plays.
What PW Consulting’s report delivers (practical, decision‑ready content)
-
Dynamic market model with year‑by‑year revenue projections (2020–2032) and configurable scenarios for slower/faster clinical adoption curves.
-
Regulatory pathway map (US, EU, Canada, APAC) with decision trees, recommended evidence packages for De Novo/PMA strategies, and timelines tied to recent precedent cases.
-
Commercial playbooks for OEMs, distributors, and hospital procurement teams: go‑to‑market sequencing, pricing frameworks, tender strategies, and contract negotiation checklists.
-
Clinical adoption roadmaps including patient segment prioritization, protocol integrations (CRRT, ECMO, cardiac surgery), and outcomes metrics to drive hospital formulary acceptance.
-
Manufacturing and supply risk analytics: capacity heatmaps, single‑sourcing risk scoring, and capital vs. outsourcing trade‑off models.
-
Competitive scorecards, supplier benchmarking, and an M&A/partnership playbook aligned to technological differentiators (adsorbent chemistry, pore architecture, disposability features).
Note: this introduction highlights strategic takeaways. The full report contains the granular segment breakouts, regional allocations, and per‑application revenue tables required for procurement forecasting and investment memos.
Drivers shaping market expansion through 2032
-
Clinical broadening beyond renal indications. Hemoperfusion is increasingly paired with CRRT and other extracorporeal therapies, extending usage into sepsis, perioperative cardiac care, and targeted toxin/antithrombotic removal. These protocol integrations are a primary demand vector in our FY2026 scenarios.
-
Regulatory momentum and differentiated pathways. Leaders are pursuing both CE and US regulatory routes; recent and ongoing pre‑submission activity with the US FDA underscores a trend toward regulated, label‑based adoption rather than off‑label use.
-
Manufacturing scale and unit economics. Automated production lines and high throughput in ISO clean environments materially reduce per‑unit cost and enable rapid scale‑up. Suppliers with proven high‑volume capability gain both margin and procurement preference.
-
Shift to disposable consumables. Infection control, ease of use, and hospital labor constraints favor single‑use devices over complex reusable systems—an enduring tailwind for disposables.
-
Evidence and reimbursement alignment. As randomized and real‑world evidence accumulates for targeted indications (e.g., cytokine storm management, intraoperative antithrombotic clearance), payers will move from ad hoc coverage to structured reimbursement—unlocking larger hospital purchasing frameworks.
Competitive landscape — concentration and strategic implications
The market exhibits meaningful concentration: the top three players account for a majority share of commercial volumes, and the top five form a dominant competitive tier. This concentration creates both barriers and opportunities: incumbent scale, manufacturing footprint, and clinical partnerships protect share, while regional distributors and nimble innovators can win by targeting under‑served clinical workflows or geography‑specific procurement models.
-
Jafron Biomedical Co., Ltd. — Positioned as a volume leader with an automated manufacturing platform capable of multi‑million annual output. The company’s HA series (multiple pore‑spectrum cartridges) is a commercial reference for toxin and cytokine adsorption; its scale is a competitive moat for supply reliability and price leadership.
-
CytoSorbents Corporation — Differentiated by strong critical care traction, a well‑established clinical footprint (hundreds of thousands of devices used cumulatively), and active regulatory engagement in the US. Recent programmatic actions—multi‑cartridge procedural concepts and De Novo regulatory dialogue—signal an aggressive commercialization roadmap for cardiac and antithrombotic applications.
-
Foshan Biosun Medical Technology and Baihe Medical — Regional innovators emphasizing sterile single‑use designs and combined HD+HP protocols; attractive partners for regional roll‑outs and cost‑sensitive markets.
-
Asahi Kasei / Toray Medical / Kaneka / Baxter / DiaCare — These players bring differentiated technologies (e.g., polymyxin B immobilized fibers, activated carbon solutions) and established distribution or acute‑care relationships, posing competitive pressure in specific clinical corridors (sepsis, endotoxin removal, acute overdose).
Recent developments underscore the strategic shift: notable regulatory and partnership movements have accelerated commercial optionality for several vendors. These tactical plays amplify the importance of early evidentiary programs and distribution exclusivity in 2026.
Risk matrix — what to watch in 2026
-
Regulatory bifurcation: differing classifications and requirements across jurisdictions can complicate global launches. Historical proposals around reclassification and PMA requirements remain relevant when targeting poisoning and hepatic indications.
-
Supply chain concentration: a supplier’s single manufacturing site or narrow supplier base for key polymers or resins increases vulnerability to disruption—mitigation requires dual sourcing or strategic inventory planning.
-
Evidence gaps by indication: while strong data exists in certain critical care uses, payers and hospitals will demand randomized data for broader elective or perioperative adoption; developers without a targeted clinical plan risk limited uptake.
-
Competition on commoditization: as disposables scale, price pressure intensifies. Differentiation through ease‑of‑use, integrated procedural solutions, or claimed indications will preserve margin.
Actionable recommendations for 2026 decision cycles
-
For OEMs and innovators: Prioritize a focused clinical indication set with a tiered evidence plan (early real‑world registries, then randomized pivotal trials for label expansion). Pursue regulatory strategy conversations early—De Novo and PMA pathways require different evidence architecture.
-
For hospital systems and procurement leads: Build total‑cost‑of‑care models comparing integrated hemoperfusion protocols vs. incremental treatment options. Negotiate conditional tenders that link pricing to documented clinical outcomes.
-
For investors and corporate development: Target assets with clear technological differentiation (unique adsorbent chemistry, validated pore architecture, or proprietary cartridge integration). Consider bolt‑on M&A to close clinical‑evidence gaps or to secure regional manufacturing capacity.
-
For distributors and regional players: Secure exclusivity tied to hospital networks and co‑developed training programs. Offer bundled service models (inventory management, on‑site training, clinical data capture) to increase switching costs for hospitals.
Next steps
PW Consulting’s full Disposable Hemoperfusion Cartridge Market report contains the granular revenue matrices, regional and application split tables, supplier scorecards, clinical evidence timelines, and an interactive scenario model used to generate our headline projections. For procurement forecasts, contract modeling, or acquisition due diligence that requires disaggregated segment data and supplier‑level financial proxies, request the full dataset via our report page.
In 2026, strategic advantage belongs to organizations that align regulatory pathways with scalable manufacturing, and who convert emerging clinical signals into reimbursable care pathways. This preview provides the strategic scaffolding; the enclosed full study supplies the granular inputs your 2026 decisions will require.
For detailed analysis of this topic, please visit the official page: Disposable Hemoerfusion Cartridge Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


