



PW Consulting: Invasive Fetal Monitors Market to reach USD 723.55 Million by 2032 at 4.68% CAGR

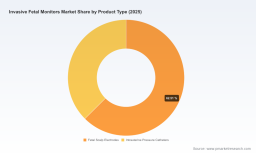
Invasive Fetal Monitors Market — Strategic Briefing for 2026 Decision‑Makers
Executive summary
As obstetric care systems worldwide continue to prioritize maternal‑fetal safety, the invasive fetal monitors market is transitioning from a post‑pandemic recovery phase into a steady growth environment. Our model, built on 2020–2025 historics and a detailed forecast to 2032, positions the global market at roughly USD 525 million in the base year (2025) with a compound annual growth rate (CAGR) of approximately 4.68% through 2032, when the market reaches an estimated USD 723 million. That trajectory conceals important asymmetries — by product architecture, care setting, regulatory regime and procurement channel — which will determine winners and losers in 2026 and beyond.
Invasive Fetal Monitors Market
Why this briefing matters for 2026 planning
-
Capital allocation timing: Companies evaluating new R&D programs, manufacturing capacity expansion, or M&A in 2026 need forward-looking demand curves and scenario analyses to avoid mis‑timed investments. Our forecast clarifies the pace and shape of demand through 2032 to inform three common investment horizons: short (18–24 months), mid (3 years) and long (5+ years).
Invasive Fetal Monitors Market -
Regulatory inflection points: Invasive fetal scalp electrodes and intrauterine pressure catheters (IUPCs) remain regulated devices subject to 510(k) pathways in the U.S. and diverging post‑Brexit conformity requirements in Great Britain (UKCA). Compliance timing and dossier readiness materially affect go‑to‑market calendars.
Invasive Fetal Monitors Market -
Reimbursement and procurement dynamics: Consumables used during labor are commonly bundled into inpatient DRG payments in major markets, which compresses hospital willingness to pay for differentiated disposables unless they unlock measurable clinical or economic benefits. Understanding where value accrues within a birth episode is essential to pricing and contracting strategy.
-
Clinical and sterilization constraints: Single‑use invasive monitors must meet established sterilization standards and face contraindications in specific maternal‑fetal conditions. These clinical boundaries influence adoption rates and training needs across institutions.
Scope and practical utility of the full report
This research is designed to be a tactical asset for commercial, regulatory and corporate development teams. The deliverables include:
-
A calibrated market model (2020–2032) with scenario toggles for adoption, pricing and reimbursement sensitivities.
-
Segmented demand drivers mapped to product architecture (invasive consumables versus monitor platforms), provider type and clinical use cases.
-
Competitive benchmarking and capability matrices for leading suppliers, including platform integrators and pure‑play consumables manufacturers.
-
Reimbursement and regulatory playbooks relevant to 510(k)/EU/UK pathways, sterilization compliance, and hospital procurement processes.
-
An actionable opportunity matrix highlighting white‑space product and geographic plays, go‑to‑market tactics, and ROI thresholds for capital projects.
-
Primary research appendices — interview summaries, procurement tender examples, and a weighted supplier risk heatmap.
To preserve commercial confidentiality and to comply with the “trailer” principle, the public summary above deliberately avoids publishing the granular regional and application splits that underpin the model. Those detailed tables, price curves and hospital‑level adoption matrices are accessible in the full report and datasets.
Competitive landscape — strategic implications
The market structure exhibits moderate to high concentration among incumbent players, creating a competitive environment where platform access, disposable consumable economics, and channel relationships matter as much as product performance. Our concentration metrics indicate that the three largest firms command a substantive share of market value, while the top five control a dominant portion — a fact that shapes tactical choices for both challengers and incumbents.
-
Laborie Medical Technologies (Mississauga): Positioned as a specialist with an IUPC product targeting intrauterine pressure measurement. Its clinical focus and product branding make it an attractive partner for institutions seeking dedicated uterine pressure solutions rather than bundled monitor systems.
-
Utah Medical Products (Midvale): A legacy manufacturer of disposable IUPCs notable for high‑volume, hospital‑grade disposables. Strengths include supply continuity and a lean disposable manufacturing footprint — important where sterilization logistics and single‑use integrity are procurement priorities.
-
Rocket Medical (UK): A key European supplier of disposable fetal scalp electrodes and an IUPC offering. Its disposable expertise and regional regulatory agility provide a platform for expansion into integrated consumable bundles.
-
Philips Healthcare (Amsterdam) and GE HealthCare (Chicago): Platform incumbents whose monitor ecosystems provide powerful lock‑in for consumable adoption. Strategy for challengers: interoperability and demonstrated clinical parity or superiority versus OEM consumables.
-
Arjo (Malmö): Known for fetal monitoring systems under established clinical brands; plays to channel trust with obstetrics teams and can accelerate clinician training programs that favor their consumables.
Strategic inference: market entry and growth require a choice between (a) becoming a trusted consumables supplier to hospitals and groups, (b) integrating with monitor platforms via partnerships or OEM deals, or (c) pursuing niche innovation that offsets the procurement disadvantage of being a new supplier.
Key market dynamics and constraints
-
Regulation: U.S. product classification and 510(k) requirements remain a gating factor for speed‑to‑market. EU and UK regulatory pathways diverge in practical timelines, which can create market access asymmetries across regions.
-
Reimbursement bundling: MS‑DRG bundling of intrapartum consumables in major markets pressures manufacturers to demonstrate per‑episode cost reduction or improved clinical outcomes to secure premium pricing.
-
Clinical constraints: Contraindications for invasive scalp electrode use constrain addressable patient populations in hospitals and complicate training and consent processes.
-
Sterilization & manufacturing: Single‑use devices must meet established SAL and sterilization standards, which drives capital requirements and supplier qualification timelines for contract manufacturers and in‑house production.
Recommended 2026 strategic plays (high‑leverage, practical steps)
-
Prioritize regulatory sequencing — map the 510(k) and UKCA timelines to your launch cadence. If you can secure early clearance for a differentiated consumable, you materially increase negotiation leverage with hospital systems before tender cycles close.
-
Design go‑to‑market around procurement economics — develop hospital‑level total cost of care (TCoC) models that show how your product reduces labor, infection risk, OR time or downstream NICU days. Embed these into value dossiers for contracting teams.
-
Lock in sterilization and CMO partnerships now — long lead times for validated sterilization (EO/gamma) and ISO compliance create a supply barrier that rewards early contracting and dual‑sourcing strategies.
-
Exploit platform interoperability — if you are not an OEM, secure validated compatibility with leading monitor platforms. Co‑marketing and technical letters of compatibility significantly shorten hospital procurement cycles.
-
Target niche clinical segments — focus initial adoption in high‑volume tertiary centers, high‑risk OB units, and private hospital systems where clinical differentiation and faster internal approval processes can create reference sites.
-
Use M&A and licensing selectively — small tactical acquisitions of clinical training tools, sterilization IP or unique electrode designs can leapfrog organic timelines and provide defensible product layers.
Scenario planning and risks
Three economic and policy scenarios should be modeled in 2026 planning: conservative (slower elective volumes and constrained hospital budgets), baseline (steady CAGR aligned with our forecast), and accelerated (faster uptake due to demonstrable clinical outcome improvements or reimbursement carve‑outs). Key risks to track include reimbursement policy shifts that change DRG bundling semantics, sudden regulatory reinterpretations in major markets, supply chain interruptions for sterilization services, and disruptive non‑invasive monitoring technologies that could limit the long‑term total addressable market.
How to use this analysis in your 2026 playbook
-
For commercial teams: use the report’s hospital procurement playbook to prioritize tender targets and shape RFP responses.
-
For regulatory teams: map dossier milestones to launch windows and include contingency for UKCA divergence from EU MDR.
-
For corporate development: apply our valuation sensitivities and opportunistic M&A checklist when screening targets — especially companies with sterilization or platform‑compatibility assets.
-
For operations: use the supply‑chain risk heatmap and CMO qualification checklist to de‑risk single‑use production scale‑up.
Next steps
PW Consulting’s full Invasive Fetal Monitors Market report contains the granular segmentation, regional demand curves, price matrices, tender intelligence and supplier financials required to execute the plays outlined above. The public summary intentionally omits those line‑by‑line splits to preserve commercial sensitivity — clients and subscribers receive the full dataset, Excel model and a two‑hour strategy workshop to convert insights into a 90‑day action plan.
For bespoke analysis — for example, pairing your product portfolio with the monitor ecosystems of dominant OEMs, or creating a tailored regulatory roadmap for a dual‑region launch — PW Consulting can provide hands‑on advisory to accelerate decision‑making in 2026.
For detailed analysis of this topic, please visit the official page: Invasive Fetal Monitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


