



PW Consulting: Fumed & Precipitated Silica Market Poised for 5.48% CAGR to 2032

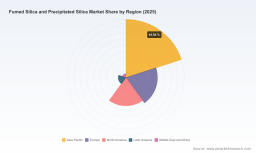
Fumed Silica And Precipitated Silica Market: Strategic Intelligence for 2026 Decision-Making
Executive snapshot
As companies plan capital allocation and go-to-market moves in 2026, the landscape for synthetic amorphous silica (fumed and precipitated) is shifting from volume-driven growth to value-capture centered on specialty grades, sustainability credentials, and regional supply security. Our latest PW Consulting market study—anchored to base year 2025 and projecting through 2032—documents this transition with rigorous market-sizing, supplier mapping, and actionable scenario analysis. The global market reached an estimated USD 7,613.5 Million in 2025 and, under a mid-case trajectory, expands at a compound annual growth rate of approximately 5.48% through 2032, when it approaches USD 11,060.5 Million. These headline metrics frame a market large enough to justify significant upstream and downstream strategic moves, yet sufficiently concentrated (CR3 ≈ 38.4%, CR5 ≈ 51.15%) to reward well-timed investments and commercial differentiation.
Fumed Silica And Precipitated Silica Market
Why this report matters to leaders in 2026
-
Decision-grade forecasting: We combine historical performance (2020–2025) with a granular bottom-up build for 2026–2032 to give CFOs and strategy teams a probabilistic view of revenue pools and margin pressure points over the next business cycle.
Fumed Silica And Precipitated Silica Market -
Portfolio prioritization: With demand bifurcating—volume elastomers vs. higher-margin specialty chemistries—our analysis isolates where incremental EBITDA is most likely to accrue without disclosing proprietary subsegment tables in this teaser.
Fumed Silica And Precipitated Silica Market -
Risk and resilience lens: Our supply-chain stress tests quantify exposure to raw-material swings, regulatory shifts, and trade measures—inputs essential to capital planning, M&A screening, and plant-siting decisions in 2026.
What the full study contains (practical, executable content)
-
Market model and scenarios: A reproducible financial model (base, upside, downside) with sensitivity knobs for energy, feedstock, and tariff outcomes to stress-test investment cases and pricing levers.
-
Go-to-market playbook: Tactical recommendations for commercial teams—segmented by application archetypes—covering product differentiation, channel strategies, and value-based pricing approaches designed to defend margin as commoditization pressures persist.
-
Capex and plant-utilization dashboard: Benchmarks for utilization, brownfield vs. greenfield economics, and payback timelines under multiple feedstock and carbon-cost assumptions.
-
Supplier and counterparty heatmap: A validated roster of producers, capacities, and logistical risk indices to inform procurement negotiation and dual-sourcing plans (note: we withhold the proprietary regional and application-level breakouts here; full matrices are in the report).
-
Regulatory & product stewardship playbook: Practical steps for compliance and downstream labeling (including STOT RE 1 implications), workplace handling protocols, and LCA-ready documentation to support customer requirements for sustainable supply chains.
Competitive landscape — who matters and why
The market is shaped by a mix of integrated multinational chemicals groups, regional specialists, and nimble local producers. Below we summarize the strategic posture of the core competitors profiled in the study; the full report contains more comprehensive capability matrices and sourcing footprints.
-
Evonik Industries AG (Essen, Germany) — A leader across both flame-derived fumed silica and industrial precipitated silicas, Evonik combines branded product lines with integrated feedstock links (including chlorosilanes), positioning it to compete on reliability and specialty-grade innovation (oral care, green tires, pharma-grade applications).
-
Cabot Corporation (Boston, USA) / Cabot Sanmar JV — Strong in fumed silica and related metal-oxide specialties, Cabot’s global footprint and recent brownfield investments target silicone, adhesives, and electronics end-markets where purity and controlled surface chemistry command premiums.
-
Wacker Chemie AG (Munich, Germany) — Known for HDK® pyrogenic silicas, Wacker has strategic capacities in North America and Asia and competes where consistent rheology control and electronic-grade specifications are needed.
-
Tokuyama Corporation (Tokyo, Japan) — Focused on high-purity fumed silicas for advanced applications such as silicones and electronics; its emphasis on product purity and application engineering makes it relevant to customers requiring tight specification control.
-
OCI Company Ltd. (Seoul, South Korea) — A regional heavyweight with targeted capacity and hydrophobic grades geared to silicones and niche high-value users; a candidate for strategic partnerships in Asia-Pacific supply security plays.
-
QEMETICA (Warsaw, Poland) — Emerged as an enlarged precipitated-silica competitor following the 2024 acquisition of PPG’s silicas business. The transaction reallocated North American and European assets and reshaped the competitive map for tire- and battery-related silica supply.
-
Solvay SA (Brussels, Belgium) — Competes on highly dispersible precipitated silicas and is increasingly marketing low-carbon variants to OEMs focused on sustainable tire solutions.
-
W.R. Grace, Tata Chemicals, and key regional players (India, China, Taiwan) — These firms round out a diverse supply base with capabilities across precipitated grades and regional logistical advantages, crucial for buyers seeking local continuity and cost competitiveness.
Recent market moves to watch (implications for 2026)
-
Evonik’s October 2024 Charleston expansion—announced as a 50% increase in precipitated silica capacity with circular-feedstock lines—signals big suppliers’ readiness to lock onto green-tire demand curves; strategic buyers should reassess long-term contract structures and sustainability premiums.
-
QEMETICA’s November 2024 acquisition of PPG’s precipitated silica business has materially shifted asset ownership in Europe and North America; expect increased consolidation-driven rationalization and renewed focus on R&D for battery and tire chemistries.
-
Cabot Sanmar’s April 2026 brownfield expansion in India reveals a parallel strategy among suppliers: strengthen domestic supply to capture fast-growing local specialty markets (pharma, semiconductors) and reduce import dependence.
Supply-chain dynamics and regulatory context
Three dynamics should be core to any 2026 planning discussion:
-
Feedstock volatility: Sodium silicate—primary feedstock for precipitated silica—exhibited regional pricing spreads in early 2026 that materially affect marginal production economics. Buyers and producers must model pass-through scenarios and consider collar-based procurement arrangements or vertical integration where feasible.
-
Upstream technology tailwinds: Silicon tetrachloride demand is growing in adjacent value chains (polysilicon, optical fiber), expanding the strategic value of fumed-silica precursor supply lines. Our supply stress simulations account for competing industrial demand for key precursors through 2032.
-
Regulatory and trade shifts: Synthetic amorphous silicas remain classified separately from crystalline silica under CLP frameworks, but certain forms face labeling and handling implications (STOT RE 1 considerations). Additionally, 2025 US tariff actions altered trade flows for fumed silica, increasing the strategic premium for domestic sourcing in certain end-markets.
Strategic moves recommended for 2026
-
Prioritize specialty and sustainable lines: With headline market expansion into 2032, not all revenue is equally profitable. Reallocate R&D and sales resource to high-margin specialty grades (e.g., HDS, hydrophobic, pharma-grade) and product lines that can credibly demonstrate lower carbon footprints.
-
Secure feedstock optionality: Negotiate multi-year agreements with sodium-silicate and silicon-tetrachloride suppliers, include escalation clauses for energy, and evaluate backward integration where capex IRRs make sense—especially in regions exposed to import tariffs.
-
Calibrate capacity moves to demand signals: Brownfield expansions are lower risk; greenfield should be evaluated under scenario cases that include tariff persistence and carbon cost escalations. Use our plant-utilization dashboard to determine optimal ramp timing.
-
Leverage M&A selectively: Consolidation is concentrated among a few players, but bolt-on acquisitions in targeted regions or application niches can rapidly improve market access and R&D capabilities—use our target-screening criteria to prioritize deals that improve technical differentiation rather than just volume.
-
Embed regulatory and LCA readiness: Invest in product stewardship documentation and LCA methodologies now to minimize customer friction and to capture sustainability premiums in tire and personal-care segments.
How PW Consulting’s study supports your 2026 playbook
This report is designed as a working tool for boards, strategy teams, commercial leaders, and procurement chiefs deciding in 2026. It balances stakeholder needs—financial rigor, commercial tactics, and operational feasibility—without exposing proprietary subsegment tables in this summary. For teams preparing investment memoranda, supplier contracts, or M&A term sheets, the full dataset, model, and playbooks will accelerate time-to-decision and reduce execution risk.
Next steps
Access to the complete study provides the granular regional, application and type-level breakouts, price-mapping, and downloadable Excel models that underpin the strategic recommendations summarized here. For tailored briefings, scenario runs, or a 90-minute executive workshop to convert insights into a 100-day action plan, contact PW Consulting to schedule a facilitated session.
For detailed analysis of this topic, please visit the official page: Fumed Silica And Precipitated Silica Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


