



PW Consulting: High-Performance Defense Fibers to Hit USD 3,644.74M by 2032 at 8.52% CAGR

High-Performance Fibers for Defense Market: A Strategic Preview for 2026 Decision-Makers
As governments and prime contractors accelerate modernization programs, the strategic calculus for sourcing, developing and qualifying high-performance fibers has shifted from tactical procurement to multi-year capability planning. PW Consulting’s latest market study — anchored on a 2025 base and a 2026–2032 forecast horizon — synthesizes five years of historical dynamics (2020–2025) into a forward-looking demand and supply roadmap. The headline: the global defense high-performance fibers market remains on a robust expansion path, growing from roughly USD 1.39 billion in 2020 to about USD 2.06 billion in 2025, and tracking toward approximately USD 3.64 billion by 2032 at a compound annual growth rate (CAGR) of 8.52% (USD, revenue unit: Million). This preview explains how that trajectory should alter executive choices in 2026 and why the full study is a near-term strategic imperative.
High Performance Fibers For Defense Market
Why this study matters for 2026 strategy
- Procurement lead times and qualification cycles now measure in years: material qualification for defense platforms commonly requires 2–5 years of ballistic testing, certification and supplier audits. Decisions taken in 2026 will determine supplier lists and production plans through the remainder of the decade.
- Supply-side rigidity collides with demand acceleration. The market’s mid-single- to high-single-digit CAGR to 2032 implies sustained capacity growth needs — but new capacity is capital- and time-intensive, particularly for gel-spun UHMWPE and specialty para-aramid processes.
- Concentration matters: the market exhibits moderate consolidation (CR3 ≈ 48.6%, CR5 ≈ 62.35%), which shapes negotiation leverage, qualification bottlenecks and strategic partnership dynamics.
What PW Consulting’s report equips you to do
The full study is built as a pragmatic decision-support tool rather than an academic exercise. It bundles a transparent market model with strategic playbooks and executable recommendations, including:
High Performance Fibers For Defense Market
- Validated demand forecasts across 2026–2032 aligned to defense procurement cycles, platform roadmaps and aftermarket replacement windows.
- Supplier and technology benchmarking with capability matrices (certifications, ballistic performance, production footprint and qualification track records).
- Plant-level manufacturing economics and an input-cost sensitivity engine (capturing petrochemical precursor price exposure and solvent-recovery capex for UHMWPE production).
- Regulatory and trade-risk overlays — export control scenarios and mitigation pathways for restricted cross-border supply chains.
- Strategic options: three go-to-market playbooks for incumbents, new entrants and integrators (organic growth, capacity partnerships, M&A and licensing).
- Actionable negotiation templates for multi-year supply agreements, and a diligence checklist for due diligence and certification acceleration programs.
Data-driven signals shaping the market trajectory
The market’s projected CAGR of 8.52% through 2032 is not an isolated statistic — it is the summation of converging demand drivers and material-specific dynamics. Persistent modernization spending, adoption of lightweight composite architectures in aircraft and ground vehicles, and an expanding set of mission profiles that require improved survivability are primary demand engines. On the supply side, technology-led differentiation (new fiber grades with higher modulus or energy absorption) and recent commercial moves — long-term supply agreements and product launches from leading fiber producers — validate the market’s upward momentum.
High Performance Fibers For Defense Market
However, growth is asymmetric. Certain fiber technologies and manufacturing routes require disproportionate capital and specialized skills (for example, gel-spinning for UHMWPE or high-modulus carbon fiber lines), which creates strategic windows for vertically integrated players and well-capitalized entrants who can internalize qualification timelines and downstream supply integration.
Competitive dynamics — what to watch in 2026
The market’s competitive map blends legacy material specialists and composite systems suppliers. Leading global participants include polymer-origin innovators, UHMWPE specialists and carbon-fiber manufacturers. Several consistent strategic postures are visible:
- Technology stewardship: legacy para-aramid producers maintain leadership through decades of ballistic validation and brand equity in protective applications. Portfolio expansions that introduce new grades or variants are used to defend program qualifications.
- Material specialization: UHMWPE producers compete on areal density and processing economics; product differentiation often hinges on improvements in gel-spinning efficiency and solvent-recovery economics.
- Composite integration: carbon fiber and prepreg specialists focus on structural defense use-cases (airframes, missiles, armor panels) where weight and stiffness trade-offs drive material selection.
- Strategic partnerships and supply agreements: multi-year contracts and localized capacity investments (e.g., expanded North American production commitments) are common defenses against export controls and demand volatility.
Recent industry moves are illustrative: global supply agreements and capacity commitments by carbon-fiber producers, introductions of higher performance continuous carbon grades, and portfolio expansions by para-aramid incumbents all signal suppliers positioning for increased defense content across platforms. For decision-makers, these developments highlight two priorities: secure multi-year supply with clear qualification pathways, and map supplier roadmaps against program timelines to avoid late-stage substitution risk.
Supply chain realities, raw-material exposure and manufacturing economics
Two underappreciated constraints deserve emphasis. First, para-aramid production is tethered to petrochemical precursors (e.g., PPD, TPC), making margins and marginal-cost decisions sensitive to benzene and xylene derivative cycles. Second, UHMWPE ballistic-grade production requires high-capital gel-spinning lines with solvent recovery systems — a combination that increases both the cost of entry and the exposure to feedstock and environmental regulations.
These characteristics imply practical mitigation levers: forward raw-material contracts, strategic inventory buffers, localizing critical production to reduce trade-risk, and investment in solvent-recovery technologies to reduce upstream price volatility. Procurement strategies that mix volume guarantees with indexed pricing and clause-based flexibility (to cover qualification-led delays) will materially reduce program risk.
Where the growth pockets (and hazards) lie — a risk-adjusted view
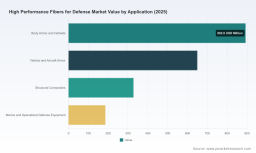
Demand opportunities exist across protective equipment, vehicle and aircraft armor, structural composites and maritime defense systems. Each end-market carries distinct procurement rhythms, qualification rigor and aftermarket dynamics. The smart strategic posture depends on your starting point:
- Incumbent suppliers should prioritize technology upgrades that shorten qualification time or provide performance differentiation, defend key program relationships with bundled support (testing, certification assistance), and consider capacity hedges in politically stable jurisdictions.
- New entrants or non-traditional materials players should focus on niche defense subsystems or aftermarket replacements where qualification pathways are shorter, or pursue co-development with primes to gain dual-use credibility.
- Prime contractors and defense integrators must balance supplier consolidation benefits against single-source risk; layered sourcing strategies with qualified second-source pathways will be essential.
Risk factors to model explicitly in any 2026 plan include raw material price shocks, export-control escalations, protracted qualification delays, and an acceleration of substitute technologies (e.g., hybrid composite-metal architectures) that could alter fiber demand mixes.
Practical recommendations for 2026 decision cycles
- Align R&D and product roadmap timelines to the 2–5 year qualification cycle — start earlier, and plan staged performance demonstrations tied to procurement milestones.
- Negotiate supply agreements with graduated volume commitments and shared investment clauses to support localized capacity or process upgrades when needed.
- Prioritize supplier scorecards that include certification history, production traceability, and raw-material sourcing transparency to comply with both military standards and export regimes.
- Run scenario-based capacity planning with sensitivity to an 8.52% CAGR baseline and downside scenarios that assume qualification slippage or trade-restriction shocks.
- Consider M&A or capacity partnerships to accelerate market entry — especially for firms seeking to capture structural composites demand or to vertically integrate ballistic material production.
The strategic value of the full PW Consulting study
This preview is intentionally selective. Our full analysis contains the granular inputs that enable executable decisions: a bottoms-up demand model by year (2026–2032) and channel, supplier-level capability scoring, plant-level cost models, price and margin forecasts, primary-interview validation with program managers and procurement leads, and a downloadable sensitivity dashboard that allows executives to stress-test CAPEX and contract strategies against multiple geopolitical and commodity scenarios.
We purposely withhold detailed segment-level splits and proprietary supplier intelligence from this summary to preserve the competitive utility of the full deliverable — and to ensure readers engage the source report for the precise levers needed to act immediately. If your 2026 planning calendar includes supplier qualification, procurement campaign design, or M&A screening in the defense fibers space, the intelligence gap filled by the full report will be consequential.
Next steps
- Schedule a strategy briefing to align forecast scenarios with your program timelines.
- Request a tailored executive snapshot that maps our demand and supplier model to your current contracts and planned solicitations.
- Use the PW Consulting sensitivity dashboard to quantify the cost of delayed qualification or a raw-material price shock on planned build rates and procurement budgets.
In a market forecasted to expand materially through 2032, the practical difference between winning and losing key defense programs will be set by decisions made in 2026. PW Consulting’s full report delivers the market-intelligence, supplier insight, and scenario tooling to translate that forward growth into executable advantage. Contact our engagements team to access the complete study and the interactive models that underpin these conclusions.
For detailed analysis of this topic, please visit the official page: High Performance Fibers For Defense Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


