



PW Consulting: Harmonic Reducer Market for Humanoid Robots to Reach USD 15.7B by 2032 at 58.9% CAGR

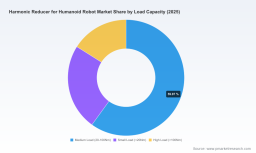
Harmonic Reducer for Humanoid Robot Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting’s latest market introduction synthesizes the rapid commercialisation of humanoid robotics and the unique role harmonic reducers play in enabling compact, high‑precision joints. Between 2025 and 2032 the market undergoes an extraordinary expansion — our base-case model projects growth from an estimated USD 482.5 million in 2025 to roughly USD 15.7 billion by 2032 at a compounded annual growth rate of about 58.9%. For executives facing procurement, product roadmap, or M&A choices in 2026, this research converts macro momentum into actionable strategic positions.
Harmonic Reducer For Humanoid Robot Market
Why this research matters for 2026
-
Timing is critical: A hyper‑growth market compresses product development and sourcing cycles. Decisions taken in 2026 will define supplier mixes and platform architectures that remain locked in across several robot generations.
Harmonic Reducer For Humanoid Robot Market -
Precision components as strategic assets: Harmonic reducers are not commodity gearboxes — they materially affect joint dynamics, energy efficiency, safety certification, and total system cost.
Harmonic Reducer For Humanoid Robot Market -
Competitive concentration: The industry displays high top‑tier share concentration, which creates both supply leverage for incumbents and attractive acquisition targets for vertical integrators.
-
Regulatory and materials inflection points: Emerging material options (e.g., PEEK composites) and safety standards adoption accelerate differentiation for suppliers that can meet aerospace‑grade processes and functional safety demands.
What the market trajectory means in practical terms
The projected multi‑billion dollar market by 2032 is driven by three compounding trends: proliferating humanoid prototypes entering pilot and early production stages, the push for lighter/faster joint architectures (including integrated motor/encoder/gearbox units), and broader acceptance of humanoids in logistics, customer interaction, and industrial support. High reduction ratios, near‑zero backlash and high positional repeatability remain the primary technical requirements — but buyers increasingly demand lifecycle documentation, functional safety support, and supply chain traceability.
Operationally, this means procurement teams must extend evaluation beyond torque and ratio specs to include certification roadmaps (Category 3 / PLe / SIL3 where applicable), contamination testing, and DPR‑level traceability common in aerospace and medical supply chains. The harmonic reducer’s share of the drive-system cost is non‑trivial and thus a focal point for TCO optimisation and design tradeoffs.
Key demand drivers and technology inflections
-
Miniaturisation and integration: Motor/encoder/actuator integration reduces part‑count and assembly complexity. Ultra‑thin and cup/hat styles continue to compete based on envelope and thermal performance.
-
Materials innovation: High‑performance polymers such as PEEK enable significant weight and space savings without sacrificing stiffness — an important lever for energy efficiency in articulated humanoid limbs.
-
Functional safety and standards: As humanoids move from labs to public environments, suppliers must support safety functions and documentation aligned with machine safety standards; vendors with ISO 9001 / AS9100 footprints will have an advantage when supporting mission‑critical customers.
-
Cost‑performance compression: New entrants — particularly from offshore manufacturing hubs — are narrowing the gap to incumbent precision suppliers, forcing a bifurcation between low‑cost, volume providers and high‑value, high‑assurance specialists.
Competitive landscape — supplier archetypes and strategic implications
The supplier ecosystem can be usefully divided into a few strategic archetypes. Our full report contains scorecards and capability matrices for each vendor; the highlights below outline the competitive positioning you should evaluate when building a supplier playbook.
-
Global precision incumbents — Examples: Harmonic Drive Systems Inc. (Japan), Harmonic Drive SE (Germany). Strengths include deep IP in strain‑wave technology, proven reliability in robotics and aerospace contexts, and complete product portfolios for demanding joint architectures. Strategic implication: incumbents are preferred for high‑assurance platforms and customers requiring long lifecycle support and certification interoperability.
-
Localized support players — Example: Harmonic Drive LLC (USA). These firms combine core technology with local service and logistics, reducing time‑to‑integration for North American OEMs. Strategic implication: useful for rapid prototyping and support contracts where proximity reduces risk.
-
Alternative gearbox specialists — Example: Cone Drive (USA), with product positioning that pairs harmonic strain wave outputs and cycloidal elements. Strategic implication: attractive where hybrid architectures or unique envelope constraints require customised gearbox solutions.
-
High‑volume, cost‑competitive entrants — Several sophisticated Chinese suppliers (including Zhejiang Laifual, Leaderdrive and others) are improving precision, lifetime, and value proposition. Strategic implication: ideal for scaling production cost‑effectively, but buyers should diligence quality systems, IP posture, and dual‑sourcing strategies.
-
Innovators focused on weight/efficiency — Examples include Makon Gear and Shenzhen PICEA Motion. These suppliers emphasise lightweight cup‑type designs and improvements in transmission efficiency, enabling meaningful system‑level weight reductions.
Market concentration metrics in our model indicate high share capture by a small group of vendors; top‑three and top‑five concentration ratios are significant. This duality — concentrated expertise plus rising challenger capabilities — creates fertile ground for selective partnerships, licensing, and targeted M&A to secure supply or accelerate capability transfer.
Recent industry signals you cannot ignore
-
Product showcases at global events (e.g., a compact planetary actuator tailored for humanoids presented in early 2026) highlight a shift towards highly integrated actuator modules that combine gearbox, motor, encoder and control electronics.
-
Public positioning by established gearbox manufacturers emphasises “made‑in” provenance and hybrid drivetrain approaches for high‑load axes — a clear response to OEMs’ demand for both reliability and regional sourcing options.
-
Market analysis and field reports cite adoption in high‑visibility humanoid programs; design disclosures make harmonic reducers a visible line item in drive‑system BOMs and total system cost calculations.
Procurement and product strategy playbook for 2026
-
Adopt a two‑tier sourcing strategy: qualify one high‑assurance incumbent and one cost‑competitive challenger for each critical joint family. Use performance‑based contracts tied to life‑cycle and reliability KPIs.
-
Insist on functional safety roadmaps and supply‑chain attestations. Components that support safe torque off/back‑driving need validation evidence and documented test traces.
-
Model TCO, not just unit price: include deferred maintenance, energy consumption impact from transmission efficiency, certification costs and replacement cadence into the procurement model. Harmonic reducers can represent a meaningful share of the drive‑system cost base and influence scaling economics.
-
Vet material strategies: where weight or envelope is a differentiator, require vendors to demonstrate alternatives such as PEEK assemblies and provide test data for wear, temperature and creep behaviour.
-
Define IP and product‑control guardrails up front for any collaboration with challengers to protect core platform designs while accessing lower unit costs.
What PW Consulting’s full study delivers (practical contents)
-
Forward‑looking market model to 2032 with scenario bands and sensitivity to unit price, adoption rates and design‑win velocity.
-
Supplier scorecards with capability assessments across precision, lifetime, certification, R&D roadmap and regional service footprint.
-
Technical deep dives comparing cup‑style, hat‑style and ultra‑thin reducer architectures, including system‑level tradeoffs for energy, torque density and thermal management.
-
Procurement playbook: RFP templates, qualification matrices, sample contract language for performance guarantees and life‑cycle support.
-
Risk heatmap covering raw material availability, regulatory shifts (REACH/RoHS/CE and IP ratings), and supplier concentration scenarios with contingency planning.
-
M&A and partnership shortlist with strategic fit analysis for vertical integrators and OEMs targeting faster time‑to‑market.
Concluding recommendations for executives acting in 2026
-
Prioritise supplier validation over lowest price when selecting reducers for mission‑critical joints; select vendors that demonstrate certification readiness and traceable production processes.
-
Build modular architectures that allow gearbox swaps as providers iterate rapidly; this protects platform investment while enabling performance upgrades.
-
Assess vertical integration selectively — acquiring or partnering with a precision reducer supplier can secure supply and protect differentiation, but requires rigorous integration of quality systems.
-
Invest in scenario planning and TCO analysis that incorporate evolving material technologies (e.g., PEEK) and functional safety requirements; these often have outsized impact on product competitiveness.
PW Consulting’s introduction aims to give you the strategic lens needed in 2026: the harmonic reducer market is transitioning from niche precision component to strategic enabler of humanoid capability and economics. The full PW Consulting report provides the numerical segmentations, vendor scorecards, and executable templates that procurement, product and corporate development leaders will need to translate this trajectory into defensible business outcomes.
For access to the complete dataset, proprietary segmentation tables and supplier scorecards, please consult the full market report on PW Consulting’s research portal.
For detailed analysis of this topic, please visit the official page: Harmonic Reducer For Humanoid Robot Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


