



PW Consulting: Short Circuit Fault Current Limiter Market Poised for 8.21% CAGR to 2032

Short Circuit Fault Current Limiter Market — Strategic Preview for 2026 Decision-Makers
Executive summary
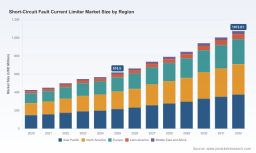
As utilities, industrial operators, and renewable asset owners plan capital allocations and technology pilots for 2026, the short circuit fault current limiter (FCL) market is transitioning from project-level curiosity to a strategic grid-architecture element. Our latest PW Consulting Short Circuit Fault Current Limiter Market study synthesizes seven years of historical tracing and a seven-year forecast, demonstrating a clear, investable growth trajectory underpinned by grid-modernization programs, inverter‑dominant generation, and targeted innovations in superconducting and power-electronic approaches. The global market reached approximately USD 618.5 Million in our 2025 base year and—at a compound annual growth rate (CAGR) of 8.21%—is positioned to cross the USD 1 billion threshold during the 2026–2032 forecasting horizon.
Short Circuit Fault Current Limiter Market
Why this study matters for 2026 strategic decisions
- Timing of deployment matters: Grid-code evolution and accelerated inverter penetration create windows of opportunity where early proof-of-concept installations can become referenceable deployments. Decisions taken in 2026 determine whether an organization participates in early value capture (reduced retrofit costs, prioritized interconnection queues) or faces later, more expensive integration efforts.
- Technology risk vs. reward: Superconducting designs, solid‑state solutions and hybrid approaches each carry distinct CAPEX/OPEX profiles, maturity curves, and supply‑chain sensitivities (notably HTS tape availability and cost). The study provides scenario-based cost trajectories and risk buffers crucial for 2026 procurement strategies.
- Regulatory alignment: New grid codes emphasizing fault-ride-through, grid-forming behaviors, and harmonics management materially affect specification, testing and acceptance criteria. Our regulatory mapping lets executives prioritize markets and product families that will meet near-term compliance and long-term operational requirements.
Market trajectory — data-driven perspective
PW Consulting’s historical analysis shows consistent expansion from the early 2020s through 2025, reflecting widening commercial interest and several high-profile validation projects. The market grew from the low‑hundreds of millions in 2020 to about USD 618.5 Million in 2025. Forecasting to 2032 at an 8.21% CAGR, the market eclipses the USD 1 billion mark in the latter part of the decade—signaling that FCLs will move from niche installations into mainstream system planning and procurement cycles. These macro-level dynamics are central to any capital planning and vendor engagement strategy for 2026 and beyond.
Short Circuit Fault Current Limiter Market
Key market dynamics and implications
- Inverter-rich grids create technical demand: The increasing share of inverter-based resources alters fault contribution behavior and raises the bar for fault-current management. FCLs become part of the compliance toolkit for maintaining stability without wholesale replacement of legacy switchgear.
- Regulatory push is accelerating uptake: Grid codes are progressively emphasizing grid-forming capability, fast fault-current management, and harmonic control. These regulatory shifts convert FCLs from optional resilience enhancers into mandated enablers in some new interconnection contexts.
- Technology evolution—HTS and power electronics: Superconducting FCLs (SFCLs) show promising performance for high-value applications but remain sensitive to HTS tape costs and cooling strategies. Power-electronic limiters, including solid-state and hybrid designs, offer faster response and modularity but require careful thermal and lifecycle management. Our study models these trade-offs across multiple deployment scenarios.
- Supply-chain and materials: Cost and availability of high-temperature superconductor (HTS) tape and critical cryogenic components are identified as key leverage points. Even modest reductions in conductor usage or operating-temperature optimization materially change total cost of ownership (TCO) for SFCL solutions.
- Regional investment programs shape demand windows: Large-scale transmission investments and reform agendas in several markets create prioritized corridors for FCL deployment—particularly where legacy switchgear retention or rapid renewable integration is strategic. Our market models overlay policy timelines to pinpoint near-term opportunity clusters.
Competitive landscape — what to watch
The market exhibits a moderate level of consolidation with a meaningful presence of global electrical equipment majors alongside specialized technology vendors. Key incumbents and challengers each bring complementary strengths:
Short Circuit Fault Current Limiter Market
- ABB Ltd. (Switzerland) — Offers medium-voltage FCL products designed for compact indoor/outdoor integration and high-requirement IS-type limiters targeted at demanding grid applications. ABB’s product breadth and systems integration capability make them a frequent partner in utility-scale projects.
- Siemens AG / Siemens Energy (Germany) — Presents fault current mitigation solutions aligned with network stability objectives, leveraging its deep transmission and distribution engineering footprint.
- Schneider Electric (France) — Integrates FCL functionality within broader medium- and low-voltage protection ecosystems, appealing to industrial and facility-level retrofit scenarios.
- Eaton Corporation (Ireland) — Focuses on current-limiting devices that support SCCR compliance and equipment protection in machine building and power distribution contexts.
- Nexans (France) — A notable mover in superconducting FCLs, with strategic alliances targeting rail and distribution network applications and a clear push toward field-validated SFCL deployments.
- LS Electric (South Korea), G&W Electric (USA), GridON (Israel), American Superconductor (AMSC, USA), Rongxin Power Electronic (China) — Each adds differentiated offerings: rapid-response limiters, high-voltage system coverage, cost-effective interrupting solutions, HTS-based SFCL development, and power-electronics centric products respectively.
Recent validated demonstrations—such as a resistive SFCL integrated with a mechanical DC circuit breaker successfully limiting faults in high-voltage DC tests, and Nexans’ alliance to field the first rail-sector superconducting limiter—illustrate the technological inflection points now moving from lab to field. These developments underscore the need for 2026 procurement teams to include pilot project clauses, staged acceptance criteria, and interoperability tests in vendor contracts.
What the report contains — practical, procurement-oriented deliverables
PW Consulting designed this study as an actionable playbook for decision-makers. Highlights include:
- Methodology and transparent market-sizing that reconciles historical deployments with modeled adoption curves and policy timelines.
- Technology-focused assessment, including performance envelopes, maturity heatmaps, and failure-mode cost implications for superconducting, solid-state, inductive and pyrotechnic approaches.
- Vendor profiles and capability matrices—covering product families, system integration experience, warranty and service models, and go‑to‑market strategies.
- Commercial guidance: procurement templates, contract risk clauses for technology validation, staged acceptance testing protocols, and TCO calculators aligned to both CAPEX and lifecycle O&M exposures.
- Regulatory impact mapping and scenario analyses that quantify market opportunity under alternative grid-code trajectories.
- Implementation playbooks for utilities and industrial asset owners, including site selection criteria, retrofit vs greenfield decision trees, and pilot-to-scale roadmaps.
- Strategic investment frameworks for investors and project developers, incorporating sensitivity analyses to HTS tape pricing, cryogenics cost curves, and supply-chain lead times.
Strategic takeaways for executives planning in 2026
- Prioritize pilot investments now: Secure early operational data and interconnection precedence by committing to measured pilots in high-impact feeders and renewable hubs. Pilots executed in 2026–2027 become competitive differentiators by 2028.
- Adopt modular contracting: Use staged procurement and performance-based milestones to reduce vendor technology risk while retaining upside if specific approaches (e.g., SFCL) achieve anticipated cost reductions.
- Embed regulatory monitoring into procurement: Align specifications with the fast-moving grid-code landscape; include acceptance criteria for fault-ride-through and harmonic performance to avoid rework.
- Model TCO under supply-chain scenarios: Stress-test ROI against HTS tape price shocks and alternative cooling strategies. Decisions on cryogenic architecture can shift TCO and project bankability materially.
- Leverage partnerships: Consider strategic alliances with suppliers that combine system integration experience and technology depth—particularly where combined offerings reduce retrofitting complexity.
How to get the full picture
This preview highlights strategic conclusions, market trajectory, vendor positioning and the operational tools executives need to define their 2026 FCL strategy. In line with our “preview” approach, we have intentionally withheld granular subsegment figures and regional/application-level splits so interested parties can access detailed datasets, segment-level forecasts and supplier scoring matrices via the full report. That granular intelligence is where procurement decisions are optimized—particularly when configuring specifications, negotiating pricing, and prioritizing pilot sites.
PW Consulting’s Short Circuit Fault Current Limiter Market study is designed to be the definitive decision-support resource for 2026: pairing market-scale validation with practical procurement artifacts and technology-risk mitigation playbooks. For organizations that must choose rapidly between competing architectures and vendors, the full report converts strategic intent into executable, low-friction action plans.
For detailed analysis of this topic, please visit the official page: Short Circuit Fault Current Limiter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


