



PW Consulting: Gamma Knife Radiosurgery Market to Hit USD 714.65M by 2032 at 5.76% CAGR

Gamma Knife Radiosurgery (GKRS) — Strategic Industry Briefing for 2026 Decision-Makers
Executive trailer: why this briefing matters for 2026
As hospital capital planning, clinical pathway redesign, and device-vendor consolidation accelerate into the mid-2020s, executives need a compact but authoritative synthesis of the Gamma Knife radiosurgery (GKRS) market that points to near-term strategic inflection points without leaking the proprietary granular tables that underpin procurement and M&A plays. PW Consulting’s Gamma Knife Radiosurgery (GKRS) Market Research serves precisely that role. It condenses validated market-sizing, trend diagnostics, and competitive positioning into a decision-grade narrative that makes clear where to probe next in procurement cycles, clinical investments, and corporate development strategies for 2026.
Gamma Knife Radiosurgery Gkrs Market Research
Market snapshot (high level, decision-useable)
Our base-year assessment for 2025 places the global GKRS market comfortably within the high hundreds of millions (USD, revenue unit: Million). After a multiyear trajectory that included uneven growth in the early 2020s, the market stabilized in 2024–2025 and is forecast to grow at a compound annual growth rate (CAGR) of approximately 5.76% over the 2026–2032 forecast window. By the end of the forecast horizon, the cumulative effect of installed-base upgrades, new clinical indications, and services/maintenance monetization is projected to lift the market materially above mid-decade levels.
Gamma Knife Radiosurgery Gkrs Market Research
Two structural features define the opportunity set for investors and hospital systems alike: (1) very high market concentration among the leading suppliers, and (2) a product profile that combines long-lived capital equipment with recurring service and consumable revenue. In plain terms: the economics favor incumbent manufacturers with established install bases and deep service networks, while offering targeted entry points for challengers who can demonstrate differentiated clinical value or superior TCO (total cost of ownership).
Gamma Knife Radiosurgery Gkrs Market Research
What this report delivers — practical, transaction-oriented intelligence
- Proprietary market-sizing model with year-by-year historicals (2020–2025) and a scenario-based forecast (2026–2032) that supports buy/sell sensitivity analysis.
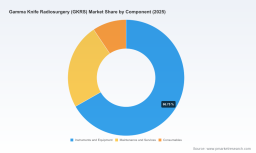
- Segmentation frameworks by product class (hardware, maintenance & services, consumables) and by clinical indication — presented to highlight market dynamics while preserving vendor-level granularity for licensed clients.
- Competitive scorecards that benchmark technology roadmaps, installed-base maturity, service coverage, pricing posture, and channel models for the major vendors and notable challengers.
- Reimbursement and regulatory mapping that links CPT/regulatory pathways to unit economics and adoption timing across advanced neurosurgery programs.
- Facility-level buy vs. lease decision templates, long-term service contract models, and a TCO calculator tailored to intracranial radiosurgery investments.
- Risk matrices and scenario playbooks addressing source management (cobalt-60 lifecycle), supply-chain contingencies, and policy shifts that materially affect capital deployment.
- M&A and partnership playbook with precedent transactions, valuation multiples (by revenue and recurring revenue), and integration checklists tailored to GKRS assets.
- Primary research: interviews with hospital program directors, medical physicists, procurement leads, and device executives to ground forecasts in observed adoption behavior.
Competitive landscape — what the market structure means for strategy
The GKRS market is notably concentrated. The top three and top five firms account for the overwhelming majority of industry revenues, creating a landscape in which incumbency, clinical reputation, and comprehensive service footprints create high barriers to displacement. For incumbents, the path to growth is twofold: protect installed-base economics through service and consumable contracts; and broaden clinical indications to capture incremental procedures within existing neurosurgical programs.
- Elekta AB (Stockholm, Sweden) remains the dominant incumbent with a full portfolio of Leksell Gamma Knife systems — including long-standing generations and upgrade pathways — and associated fixation consumables. The company’s clinical and regulatory momentum is material: in mid‑2025 Elekta secured U.S. regulatory clearance to expand indications to include refractory, drug‑resistant mesial temporal lobe epilepsy (MTLE) in adults. Strategically, this expands GKRS from primarily tumor- and vascular-focused workflows into higher‑volume functional neurosurgery, with implications for treatment mix, site-of-care strategies, and reimbursement negotiations.
- MASEP Medical Science & Technology Development Co., Ltd. (China) presents a regional challenger model focused on rotary gamma systems that are marketed as cost-competitive alternatives in select markets. Their playbook emphasizes local manufacturing, faster procurement cycles, and service partnerships that align with regional hospital purchasing preferences.
- American Radiosurgery Inc. (United States) brings a differentiated rotating gamma system (RGS Vertex360) that targets specific delivery advantages and may appeal to centers seeking alternatives to cobalt-centric platforms or looking for specific workflow efficiencies.
For 2026 planning, the practical implications are clear: procurement teams should model both acquisition and installed‑base upgrade scenarios, and corporate development teams should evaluate adjacencies (e.g., service networks, software-enabled treatment planning, and outcomes data platforms) as levers to sustain high-margin recurring revenues.
Market drivers, dynamics and constraints
- Clinical expansion and regulatory pathways: Indication expansion into functional disorders (e.g., MTLE) and other non-oncologic uses supports procedure growth per center. Regulatory clearances that broaden indications typically accelerate hospital capital committee approvals and payer discussions.
- Reimbursement complexity: Single‑fraction GKRS often commands higher technical reimbursement than certain multi‑fraction or linac-based SRS alternatives in several markets. That differential creates both upside for centers that demonstrate cost-efficient throughput and downside risk if payers compress payment levels or impose site-of-service controls.
- Capital intensity and lifetime economics: GKRS platforms are high-value, dedicated intracranial systems with long clinical lifecycles. Hospitals must weigh high upfront CapEx and source management requirements against predictable long-term case volumes and maintenance revenue potential.
- Regulatory and operational burden: Cobalt‑60 source management imposes unique installation, safety, and decommissioning requirements that raise the bar for new site openings and complicate cross-border deployments.
- Service and consumables as revenue multipliers: After-sale service contracts, source replacements, and consumables form an outsized share of lifecycle revenue — a focus area for both incumbents defending share and new entrants seeking steady cash flow.
Risk scenarios that should shape 2026 choices
- Reimbursement downside: If payers narrow technical payments or shift incentives toward multi‑purpose linac treatments, smaller or marginal GKRS programs may become uneconomic.
- Regulatory tightening on sources: Stricter source transport, import/export controls, or added decommissioning liabilities would increase total system cost and slow new installations.
- Competitive displacement: Broader adoption of flexible linac SRS with competitive clinical outcomes and lower site-specific overhead could constrain GKRS unit placements to high-volume centers.
- Supply-chain concentration: Single‑source components and limited manufacturing capacity for replacement sources or key subsystems represent operational risks that can affect uptime and service profitability.
Strategic playbook: recommended moves for 2026
- For hospital systems: Prioritize an outcomes-driven procurement rubric that models lifetime cost, expected case-mix shifts (including functional indications), and payer mix sensitivity. Consider service-intensive contracting or consortium purchasing to reduce unit cost and secure rapid technician and physics support.
- For vendors and investors: Protect recurring revenue through differentiated service agreements, invest in software and outcomes registries that demonstrate longitudinal value, and pursue selective partnerships to accelerate geographic reach without heavy CapEx exposure.
- For private equity and corporate development: Target tuck-in acquisitions that expand service footprints, consumables portfolios, or add complementary treatment-planning software; these moves can convert transactional hardware sales into predictable annuity streams.
Why PW Consulting’s GKRS research is uniquely actionable for 2026
Our report synthesizes robust primary interviews, hospital procurement templates, and a scenario-driven forecast model that translates market trends into executable options: buy, postpone, partner, or divest. We intentionally present the directional intelligence and competitive diagnostics that C-suite leaders need to start board-level conversations — while reserving the line‑by‑line segmentation datasets and vendor-specific unit economics for licensed report access. This “trailer” approach ensures you can make timely strategic calls in 2026 while preserving the data granularity required for financial diligence and negotiation tactics.
Next steps
Decision-makers preparing 2026 capital and M&A plans should engage with the full report to retrieve the detailed segmentation matrices, the center-level adoption curves, vendor scorecards, and the downloadable TCO and scenario models that power procurement and valuation workstreams. For a targeted executive briefing and license options, please consult the PW Consulting report landing page to unlock the datasets and appendices necessary for transaction execution.
For detailed analysis of this topic, please visit the official page: Gamma Knife Radiosurgery Gkrs Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


