



PW Consulting: Semi Direct Drive Wind Turbine Market to Reach USD 41,034.98M by 2032 (12.02% CAGR)

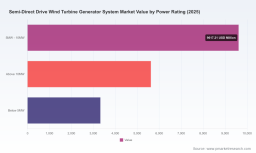
Semi Direct Drive Wind Turbine Generator Systems: Strategic Outlook for 2026 Decision-Making
As governments, utilities, OEMs, and investors set capital and technology priorities for 2026, semi direct drive wind turbine generator systems (WTGS) have moved from niche engineering experiments to a mainstream option for large-megawatt offshore projects and selected onshore deployments. Our PW Consulting market study, anchored on a 2025 base year and a 2026–2032 forecast horizon, quantifies that transition and converts it into practical implications for commercial strategy. The global market demonstrates sustained expansion—coming off a multi-year growth trajectory in the early 2020s and projecting a compound annual growth rate (CAGR) of 12.02% through the forecast window—an acceleration that changes competitive dynamics, supplier economics, and procurement frameworks in 2026 and beyond.
Semi Direct Drive Wind Turbine Generator System Market
Why this research matters for 2026 strategic choices
-
Timing matters: 2026 is the inflection year for many offshore program decisions—turbine selection, supply agreements, factory footprint commitments, and long-lead procurement. The study translates market-scale growth into concrete procurement windows and technology adoption milestones.
Semi Direct Drive Wind Turbine Generator System Market -
Risk-reward calibration: higher-capacity semi direct drive platforms are now competing on total cost of ownership (TCO) rather than headline CAPEX alone. Our analysis articulates the break-even sensitivities—installation logistics, availability profiles, and maintenance pathways—that commercial teams must quantify before contract signature.
Semi Direct Drive Wind Turbine Generator System Market -
Partnering and M&A signals: with market concentration trends and rising scale requirements, the report helps executives decide whether to pursue vertical integration, supply partnerships, or targeted acquisitions to secure key drivetrain components and aftermarket revenue.
Market trajectory in brief
Using 2025 as the analytical base, PW Consulting’s consolidated market model shows that the semi direct drive WTGS market has expanded materially since 2020 and is set to continue growing through 2032. The market-sized baseline in 2025 reflects mature deployments and accelerating adoption, and our projection to 2032—with an implied CAGR of 12.02% for the forecast period—supports a multi-fold increase in industry throughput over the decade. These macro metrics underpin scenario-level capital requirements, supply chain ramp plans, and engineering capacity forecasts that procurement and strategy teams need to finalize 2026 budgets.
Report scope — what you’ll get (high level)
-
Market sizing and forecast model (2020–2032) with scenario variants reflecting commodity shocks, regulatory accelerants, and technology diffusion paths.
-
Demand-side drivers: project pipeline analysis, offshore vs onshore dynamics, tender win probability models, and OEM selection criteria used by developers.
-
Supply-side mapping: detailed supplier tiers for generators, medium-speed gearboxes, nacelle integration, and specialized floating-hub components—plus a capacity build-out timeline for manufacturing footprints.
-
Economics toolbox: component-level cost curves, LCOE sensitivity analysis, and operating-expenditure (OPEX) scenarios tied to reliability and maintenance modalities.
-
Technology assessment: comparative TRL mapping across full direct-drive, semi direct drive, and doubly-fed solutions, with IP landscaping and patent cluster analysis.
-
Regulatory and permitting overlays by major jurisdiction, including modeled timelines for permitting-to-commissioning under alternate policy scenarios.
-
Commercial playbook: procurement negotiation templates, risk allocation matrices for supply contracts, and aftermarket service commercialization roadmaps.
Competitive landscape — who matters and why
The semi direct drive sector is consolidating around a small set of technology leaders and specialized component suppliers. Market concentration metrics signal a defensible incumbent set: the three largest groups capture a meaningful majority of market share, and the top five extend that dominance further—dynamics that directly affect pricing power, certification bandwidth, and access to reference projects.
-
Ming Yang Smart Energy Group Co., Ltd. (China) — Ming Yang has positioned itself as a global leader in semi-direct drive solutions for offshore installations. Its medium-speed compact drive (MCD) product family and typhoon-resistant platforms are engineered for large-array deployments and adverse weather resilience. The company’s public roadmap emphasizes modular drivetrain designs and a growing floating turbine concept portfolio—evidence of a product strategy that targets both fixed-bottom scale and next-generation floating applications.
-
Dongfang Electric Corporation (DEC) (China) — DEC has invested heavily in highly integrated semi direct drive architectures, including very large prototypes in the multi-tens of megawatts class. Recent prototype installations demonstrate the company’s ability to integrate shaft systems, gearsets, and permanent magnet generators into compact assemblies—reducing interface risk and creating attractive lift-and-install profiles for offshore projects that value installation window compression.
-
Goldwind Science & Technology Co., Ltd. (China) — Historically a major PMDD (permanent magnet direct drive) proponent, Goldwind’s portfolio has evolved to include medium-speed hybrid drivetrains. This hybrid posture allows Goldwind to compete across a broader set of project economics, offering flexibility to developers weighing unit-size economies against reliability and supply-chain considerations.
-
Yinchuan Weili Transmission Technology Co., Ltd. (China) — As a specialized supplier of integrated speed increasers and compact gearbox subsystems, Weili addresses the most material technical challenge for semi direct drive designs: connecting the impeller to a medium-speed permanent magnet generator while preserving compactness, weight targets, and efficiency. Their component solutions reduce nacelle mass and simplify installation interfaces—critical attributes for floating and deepwater projects.
Recent strategic developments (context for 2026 negotiations)
-
Ming Yang unveiled next‑generation medium‑speed compact semi‑direct drive (MCD) platforms alongside conceptual floating concepts, signaling an intent to compete on both scale and platform versatility. Such launches affect tender specifications where modularity and floating readiness are procurement differentiators.
-
Dongfang completed installation of a very large-capacity prototype employing a fully integrated semi-direct drive assembly. Prototype deployments of this caliber shorten the path to commercial certification for OEMs and tip procurement decisions toward suppliers that can demonstrate integrated subsystems with real-world performance data.
-
Across the supplier base, migration toward medium-speed or hybrid drivetrains is accelerating. This shift changes the supplier ecosystem: standard gearbox and generator suppliers are adapting product roadmaps, and new integration specialists are emerging to capture value in the mid-speed interface.
Key dynamics and supply-side considerations
-
Material intensity and rare-earth strategy: semi direct drive PM generators typically require materially less rare-earth magnet mass than full direct-drive equivalents. That provides resilience against raw-material price spikes and simplifies logistics for large-unit programs. Market participants are simultaneously pursuing rare-earth reduction through design optimization—an important R&D and procurement consideration for 2026 bids.
-
Manufacturing scale and localization: as large projects demand higher unit volumes and faster delivery, OEMs face choices on where to localize assembly vs. import. The report models ramp phasing and breakeven analyses to guide factory-capex decisions tied to confirmed offtake.
-
Certification and reliability data: semi direct drive platforms benefit from lower rotational speeds and favorable vibrational profiles, which can translate to reduced fatigue loads and maintenance intervals. Buyers should demand consistent failure-mode data and standardized testing protocols during 2026 procurement cycles.
-
Concentration and bargaining power: with top-tier suppliers accounting for a large share of incumbent capacity, developers may encounter limited price flexibility but gain faster commissioning and easier warranty enforcement when choosing proven supplier chains.
Strategic recommendations for executives planning in 2026
-
Prioritize supplier validation: make conditional commitments to suppliers demonstrating integrated prototype performance and third-party reliability metrics. Insist on tranche-based contracts that align payment milestones with certification and factory readiness.
-
Hedge material exposure: engage in forward contracts or strategic partnerships for permanent-magnet material supply where necessary, while incentivizing suppliers to pursue rare-earth-light designs.
-
Design for serviceability: given the operational importance of offshore uptime, structure OEM contracts to include meaningful availability guarantees and clear KPIs for mean time to repair (MTTR), supported by local service hubs and spare-parts logistics plans.
-
Consider selective vertical integration: for developers with large pipelines, capturing value through in-house drivetrain assembly or critical component JV’s can shorten lead times and improve bargaining positions—but only where structured with realistic ramp and certification milestones.
-
Use competitive concentration to your advantage: when the market is oligopolistic, leverage reference projects and consortium arrangements to extract technology transfer, spares pricing, and capacity reservations as part of award negotiations.
What the full PW Consulting report contains that you’ll need in 2026
Our full study provides the granular models and proprietary datasets that allow procurement teams, product strategists, and investors to convert the high-level trends above into executable plans. That includes detailed cost build-ups by component, regional supply-path analyses, project-level TCO models, IP maps, and a tranche-by-tranche risk register aligned to project schedules. Crucially, the exhaustive segment-level figures, scenario matrices, and supplier scorecards are reserved for the full report to preserve competitive integrity and to ensure stakeholders use the validated models when finalizing commercial commitments.
Closing perspective
Semi direct drive WTGS represent a pragmatic inflection point in the wind industry’s pursuit of lower LCOE and higher project reliability for large-scale offshore deployments. For 2026, the imperative is clear: convert the headline macro growth (anchored on a robust CAGR through 2032 and a substantially expanded market base by the end of the decade) into concrete supplier selections, risk allocations, and manufacturing commitments that are testable and reversible. Executives who align procurement windows, material hedges, and partner structures to the timelines and technical realities outlined in this briefing will be best positioned to capture value as the market scales.
For project-ready models, supplier-level scorecards, and the segment-level intelligence that supports binding commercial decisions in 2026, access the full PW Consulting Semi Direct Drive Wind Turbine Generator System Market report.
For detailed analysis of this topic, please visit the official page: Semi Direct Drive Wind Turbine Generator System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


