



PW Consulting: Soy Milk Market to Top USD 11,707.9M in 2025

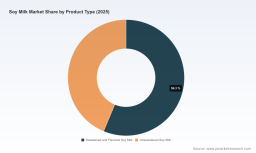
Soy Milk Market 2026: Strategic Imperatives for Leaders and Challengers
As PW Consulting’s Senior Strategic Advisor and Head of Industry Research, I present a forward-looking synthesis of the Soy Milk Market designed to inform boardroom decisions in 2026. This executive primer draws on our full-market study (base year 2025; forecast period 2026–2032), which models demand, price dynamics, channel migration, and competitive responses across developed and emerging markets. The headline: the global soy milk market has demonstrated steady expansion — moving from the low‑single‑digit billion-dollar range earlier in the decade to roughly USD 11.7 billion at the 2025 base year — and under our central scenario is set to continue growing at a mid-single-digit compound annual growth rate (CAGR) of approximately 6.0% through the forecast window, approaching the mid‑teens billion range by the early 2030s.
Soy Milk Market
Why 2026 is a Strategic Inflection Point
- Nutrition-led product innovation is accelerating. 2026 has seen incumbents and start‑ups reposition soy milk from commodity plant‑based beverage to targeted nutritional solutions: high‑protein formulations, complete‑protein claims, and minimal‑ingredient “clean label” offerings intended for mainstream and premium shelves alike.
- Channel fragmentation and digitalization intensify go‑to‑market complexity. Traditional brick‑and‑mortar remains important, but e‑commerce, DTC, subscription models, and foodservice channels are reshaping assortment, pricing and promotional mechanics.
- Supply‑side volatility raises margin and sourcing risk. Commodity drivers — including higher U.S. season‑average soybean price forecasts and marginal gains in global vegetable oil indices — are creating a nearer‑term cost floor that will influence pricing strategy and contract structures in 2026.
Market Dynamics: Growth Drivers and Constraints
Demand fundamentals for soy milk are supported by several durable trends. Rising consumer health awareness, protein‑seeking behavior, lactose avoidance, and environmental concerns underpin steady end‑market expansion. At the same time, product sophistication — from fortified, high‑protein formulations to regionally inspired flavors and hybridized plant blends — is pushing average selling prices and creating white spaces for premiumization.
Soy Milk Market
However, growth is not uniform. Raw‑material dynamics matter. For example, USDA adjustments to the 2025/26 U.S. soybean season‑average price and slight year‑over‑year changes in global soybean production signal that procurement strategies, hedging and supplier diversification should be central to 2026 planning. Furthermore, macro factors such as biofuel demand for soyoil and FAO‑tracked vegetable oil movements introduce near‑term price sensitivity that can compound margin pressure in exposed, low‑value product lines.
Soy Milk Market
Competitive Landscape: Structure, Players and Strategic Moves
Industry concentration measurements indicate a market with meaningful national and regional champions, but not an entrenched oligopoly — the top three and top five firms account for a plurality rather than a majority of global value. This structure keeps competitive pressure high, and incentives for differentiation and private‑label penetration remain strong.
- Global branded leaders: Multinational food companies are leveraging scale, distribution and R&D to broaden portfolios. For example, companies with established plant‑based platforms are introducing higher‑protein refrigerated SKUs and cross‑brand innovation to capture mainstream shoppers seeking nutritional parity with dairy.
- Regional specialists and heritage brands: Firms rooted in Asia and other high‑consumption markets maintain strong brand equity and tailored SKUs for local palates, supply linkages with soybean producers, and deep foodservice relationships.
- Natural and organic challengers: Smaller organic and clean‑label brands are carving out premium niches with minimalist ingredient lists, traditional processing claims, and targeted retail placements.
- Private‑label and co‑packing: Retailers and co‑packers continue to expand private‑label ranges, using soy milk as a strategic entry point into plant‑based milks for value‑oriented consumers.
In the competitive appendix of our full report we profile the leading and fast‑emerging firms, including their strategic positioning, channel priorities and recent product moves. Companies covered include major multinationals with widely recognized soy portfolios, large regional players with dominant in‑market presence, and disruptive new entrants advancing high‑protein and clean‑label concepts—each assessed for innovation capacity, route‑to‑market effectiveness, and acquisition appetite.
Recent Strategic Developments (Early 2026) and Their Implications
- Several high‑profile product launches in early 2026 underscore a bifurcating product strategy: high‑protein mainstream offerings that compete with dairy on nutrition, and minimalist clean‑label SKUs aimed at premium natural channels. These launches validate protein as a marketing axis and clean label as a margin enhancer.
- New brands entering Southeast Asian markets with modernized formulations are accelerating premiumization in fast‑growing urban centers — a reminder that regional taste adaptation and branding are critical in APAC markets.
- Incremental sales gains reported by heritage food manufacturers in health‑oriented packaging formats point to upside in smaller pack sizes and on‑the‑go consumption occasions.
Together, these moves indicate that 2026 will be defined by portfolio re‑engineering: bigger SKUs for value play; smaller, fortified SKUs for on‑the‑go and protein seekers; and a continued premium push via organic and clean‑label differentiation.
What Our Full Report Provides (Practical Deliverables)
PW Consulting’s complete Soy Milk Market report is designed as an operational playbook for commercial leaders and investment committees. Key deliverables include:
- Bottom‑up historical and forecast market sizing (2020–2032) with scenario analysis and sensitivity to soybean price, oilseed supply shocks and demand elasticity.
- Channel and occasion mapping that highlights where margin pools shift under online, convenience and foodservice penetration scenarios.
- Product taxonomy and innovation tracker that catalogs formulations, nutritional claims, packaging formats and emerging value propositions.
- Detailed competitor benchmarking with capability heatmaps, go‑to‑market strategies, recent M&A and pipeline activity.
- Commercial playbooks for retailers, CPG manufacturers and ingredients suppliers: SKU rationalization, pricing ladders, private‑label strategies, and negotiation levers for raw‑material contracts.
- Risk matrix and policy/regulatory tracker tied to labeling, health claims and sustainability metrics relevant to soy‑based beverages.
- Investment implications and M&A thesis for consolidators, ingredient suppliers and entrants targeting manufacturing or distribution scale.
Note: this executive preview intentionally omits the granular split tables and line‑by‑line segment financials that appear in the full dataset. Those segment‑level tables and country profiles are central to transaction diligence and competitive benchmarking and are available through the full report.
Strategic Recommendations for 2026 Decision‑Makers
- Tactical procurement and hedging: Lock in multi‑year supplier arrangements with built‑in flex for quality tiers; explore vertical integration or strategic sourcing partnerships in high‑exposure markets.
- Portfolio segmentation: Define clear product pillars — value/basic, nutrition‑led, and premium clean‑label — with tailored supply chains and margin targets for each.
- Channel‑specific GTM: Build distinct pricing and promotional playbooks for supermarkets, convenience channels, and e‑commerce; prioritize DTC pilots for premium SKUs to capture first‑party consumer data.
- Innovation cadence: Invest in rapid prototyping and consumer testing for protein and flavor claims; consider co‑innovation with ingredient suppliers to secure exclusivity on functional profiles.
- M&A and partnerships: Target bolt‑on acquisitions that add route‑to‑market in priority regions or that bring proprietary processing/fortification capability; evaluate strategic JVs with regional champions to accelerate market entry.
How PW Consulting Can Help
Our team combines category P&L experience with primary retail POS analytics, supply‑chain modeling, and on‑the‑ground consumer insight capability. For leadership teams preparing budgets and investment roadmaps in 2026, we offer: accelerated due diligence packages, go‑to‑market playbooks, SKU rationalization workshops, and risk‑stress testing for commodity scenarios.
For practitioners seeking the complete data tables, segment breakouts, company scorecards and downloadable models referenced above, please consult the full PW Consulting Soy Milk Market report. The detailed segment revenue layers, country‑level forecasts, and transaction‑ready annexes are intentionally reserved for the full publication to preserve the commercial utility of the dataset.
In short: the soy milk category is entering a phase where nutritional credibility, supply resilience, and channel execution will determine winners and losers. 2026 is the year to lock strategy to the evolving cost base, invest selectively in high‑value product pillars, and use M&A and partnerships to plug capability gaps before competition commoditizes those advantages.
For detailed analysis of this topic, please visit the official page: Soy Milk Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


