



PW Consulting: Industrial Sodium Nitrate Market to Hit USD 520M by 2025

Industrial Sodium Nitrate Market: Strategic Outlook for 2026 Decision‑Makers
Executive overview
As 2026 begins, industrial sodium nitrate has re-emerged as a strategic input across a set of capital‑intensive and high‑value industrial value chains — from glass and metal processing to energy storage and specialty chemical synthesis. PW Consulting’s latest study frames this market not as a niche commodity but as a mid‑cycle growth arena, offering actionable signals for procurement, operations, and M&A decisions across manufacturing portfolios.
Industrial Sodium Nitrate Market
The global market demonstrated steady expansion through the last half‑decade, rising from the low‑hundreds of million USD in 2020 to roughly half a billion USD by the 2025 base year. Our forecast through 2032 embeds a compound annual growth rate (CAGR) of approximately 4.0% for the 2026–2032 period, reflecting a combination of steady end‑market demand, selective capacity additions, and persistent raw‑material cost pass‑throughs. This trajectory creates a predictable envelope for capital planning while leaving room for differentiated winners who act on structural shifts now.
Industrial Sodium Nitrate Market
Why this research matters for 2026 corporate strategy
- Decision horizon alignment: The report translates macro growth rates and price dynamics into 18–36 month tactical imperatives — critical for budget cycles, contract negotiations, and plant scheduling.
- Risk‑adjusted investment signals: By identifying where substitution risk, feedstock exposure, and regulatory compliance coalesce, the study enables firms to prioritize investments that de‑risk margins.
- Competitive positioning: We map the market concentration and the distribution of operational advantages that matter to buyers, sellers, and financiers in 2026.
Market trajectory and structural drivers
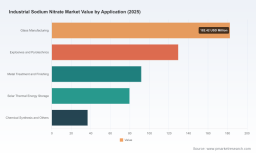
The sodium nitrate market’s gradual but steady expansion is anchored in two structural features. First, a diversified application set — a balance of established industrial uses (e.g., glass, explosives, metal finishing) and emerging use cases (notably thermal energy storage salts) — smooths overall volatility. Second, the industry’s feedstock sensitivity links profitability directly to movements in soda ash and nitric acid markets, creating rapid margin swings when upstream price cycles move.
Industrial Sodium Nitrate Market
Our scenario work shows that typical market outcomes are shaped by three vectors: (a) feedstock cost volatility and its pass‑through cadence; (b) upstream capacity expansions by resource‑advantaged producers; and (c) regulatory tightening on nitrogen‑discharge and emissions, which raises the bar for brownfield operators. Taken together, these vectors explain why a measured CAGR is likely to coexist with episodic regional price differentials and procurement arbitrage opportunities.
Pricing and raw‑material dynamics (what to watch in 2026)
- Feedstock linkage: Soda ash and nitric acid remain the dominant cost drivers for producers. Procurement teams that secure multi‑month hedges or vertical integration with soda ash suppliers materially reduce margin volatility.
- Regional price divergence: In recent quarters the market has shown divergent regional behavior — some regions posting modest upward pressure while others experienced notable softness. Buyers and risk managers should therefore expect regional spreads and plan logistics and contracting accordingly.
- Seasonality and demand shocks: End‑market seasonality (e.g., construction cycles affecting glass demand) and episodic demand from explosives/pyrotechnics markets can create short windows of tight supply. Tactical inventory policies will outperform across these windows.
Regulatory, sustainability and supply‑chain constraints
Environmental regulation is a growing shaping force. Compliance related to nitrogen run‑off, water quality, and emissions is raising the effective cost of production for operators that rely on legacy processes. 2026 action items for operations leaders include capital prioritization for effluent treatment, adoption of cleaner process chemistries, and supplier audits to ensure compliance across multi‑tier supply chains. Those that anticipate these costs in procurement contracts and product pricing will preserve margin and avoid sudden compliance costs.
Competitive landscape — who sets the tone
The market exhibits moderate concentration: the top three players account for a meaningful share of global capacity, and the top five increase that concentration materially. This structure produces an environment in which scale and feedstock access translate into pricing discipline and supply reliability.
Key industry participants illustrate differentiated competitive logic:
- Resource‑advantaged producers with direct access to natural deposits retain a structural cost edge. Their scale, long‑term low‑cost feedstock access, and export logistics make them central to balancing global supply in stressed periods.
- Large integrated chemical groups leverage portfolio synergies — feedstock sourcing, co‑product optimization, and global distribution networks — to supply specialty and industrial grades into diverse end markets.
- Regional players, including several fast‑growing producers in Asia, bring cost‑competitive supply and agility for domestic demand, particularly where logistics barriers favor local sourcing.
- Public‑sector and legacy fertilizer producers often maintain strategic capacity and can act as price stabilizers or disruptors depending on domestic policy and export strategy.
Recent industry developments reinforce these dynamics: notable capacity additions by a leading Indian producer—implemented through new overseas facilities—and production expansion initiatives by a major Chilean supplier underscore how capacity moves remain a principal way to influence regional availability and pricing in 2026. Buyers should assume that capacity projects introduced over the last 12–18 months will increasingly shape competitive outcomes.
Practical implications for business functions
- Procurement and supply‑chain: Shift from pure cost procurement to total cost of ownership (TCO) frameworks that integrate feedstock exposure, regulatory compliance costs, and logistics volatility. Negotiate flexibility clauses tied to feedstock indices when possible.
- Operations and plant managers: Prioritize effluent controls and process upgrades where capex budgets are constrained — the regulatory cost of inaction is material. Consider modular capacity additions to capture niche thermal‑storage and specialty demand.
- Corporate strategy and M&A: Target acquisitions that deliver feedstock security or downstream application footholds (e.g., specialty blends for thermal storage or high‑purity grades for glass). The market favors strategic vertical or geographic bolt‑ons over broad horizontal consolidation.
- Sales and marketing: Differentiate on reliability, certification/compliance, and technical service. Purely price‑based competition is increasingly unsustainable in regions where environmental compliance and logistics reliability command premiums.
Report highlights — what PW Consulting provides (practical, executable modules)
- Verified market sizing and a 2026–2032 forecast model calibrated to commodity cycles and project pipelines, giving CFOs and corporate planners a scenario toolkit for budgeting and stress‑testing.
- Supply‑chain heat maps showing where feedstock sourcing risk, logistics congestion, and regulatory exposure concentrate and how these nodes shift under alternative scenarios.
- Competitive profiles and capability matrices for the leading global and regional producers, including production footprints, expansion projects, and strategic differentiation.
- Price‑sensitivity models that translate soda ash and nitric acid price swings into margin outcomes at the corporate and plant level — designed for negotiation and hedging strategies.
- Regulatory playbooks with remediation cost estimates and implementation roadmaps for effluent treatment and emissions controls, prioritized by ROI and compliance urgency.
- Actionable M&A screening criteria and a shortlist of targets consistent with buy‑and‑build strategies, compact with integration risk matrices to accelerate due diligence.
How to use this intelligence in 2026
For decision‑makers the value of this study is practical rather than purely descriptive. Use it to:
- Calibrate procurement contracts to protect margins against feedstock swings while preserving supply flexibility for demand peaks.
- Prioritize capital projects that both reduce exposure to regulatory risk and unlock new, higher‑margin applications such as thermal energy storage salts.
- Identify acquisition targets that either secure feedstock or provide geographic access to growth markets with favorable pricing dynamics.
- Design go‑to‑market differentiation emphasizing reliability, sustainability credentials, and technical service rather than competing on volumetric price alone.
Limitation and the value of the full report
This article is a strategic preview: it synthesizes market structure, dynamics, and strategic implications to support immediate 2026 decision cycles. To preserve the practical consulting value and protect proprietary modeling, we have intentionally withheld granular segment allocations, region‑level revenue tables, and unit‑price time series that underpin our forecasts. These detailed components — including interactive scenario models, granular regional demand matrices, and company‑level shipment estimates — are available in the full PW Consulting report and are essential for transaction‑grade analysis.
Conclusion and next steps
The industrial sodium nitrate market in 2026 is a study in managed growth: steady headline expansion, episodic regional price divergence, and a competitive landscape where feedstock access and compliance readiness determine winners. Companies that convert these insights into procurement discipline, targeted capex, and selective M&A will materially outperform peers over the next 18–36 months.
For firms seeking transaction‑level detail, supplier scorecards, or scenario models to support 2026 budgets and negotiations, PW Consulting’s full Industrial Sodium Nitrate Market report is set up as a hands‑on toolkit. Access to the complete datasets and model outputs will enable you to translate the strategic implications above into executable projects with quantified ROI.
For detailed analysis of this topic, please visit the official page: Industrial Sodium Nitrate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


