



PW Consulting: Orthodontic Aids Market hits USD 7,850.5M in 2025

Orthodontic Aids Market 2026: Strategic Imperatives for Executive Decision-Makers
Introduction — Why PW Consulting’s New Study Matters
As PW Consulting’s lead industry analyst, I present the executive primer to our latest Orthodontic Aids Market study. This briefing synthesizes the macro trajectory, regulatory inflection points, competitive moves and actionable playbooks that should shape corporate strategies through 2026 and into the 2030s. The goal is to demonstrate the analytical depth and commercial relevance of the report while preserving core segment-level data as a gated asset — a deliberate “trailer” designed to show value and prompt engagement with the full intelligence set.
Orthodontic Aids Market
Executive snapshot: size, growth and horizon
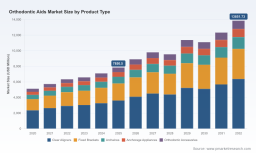
The orthodontal aids market has moved from a niche medical-supply category into a growth-oriented medtech subsector with a clear digital uplift. Our base-year sizing places global revenue near USD 7.85 billion (2025), up from roughly USD 5.12 billion in 2020, reflecting sustained adoption of aesthetic systems, digital workflows and higher-treatment uptake. The forecast period (2026–2032) projects a compound annual growth rate of 8.45%, with the market crossing meaningful thresholds by the late 2020s under multiple plausible scenarios.
Orthodontic Aids Market
- Five-year momentum (2020–2025) established scale and enabled accelerated investment in R&D and channel expansion.
- The 2026 opening year reflects both pent-up demand and technology-driven substitution — notably in clear aligners and digital intraoral scanning ecosystems.
- Our forecast horizon balances cyclical uncertainty with durable secular drivers: digitalization, patient preference for aesthetics, and expanding clinical pathways in hospitals and DSO frameworks.
Why this matters for 2026 corporate strategy
The coming 18 months will determine which manufacturers and service providers translate technological promise into durable market share. Executives must treat the market as a digitally enabled medical device category — not a commodity dental-supply segment. That framing changes capital allocation, go-to-market priorities and regulatory resource planning.
Orthodontic Aids Market
- Revenue growth is healthy but uneven: scale benefits incumbents; nimble innovators win pockets of margin expansion.
- Regulatory and reimbursement shifts are creating windows of opportunity for first-movers and risk for late entrants.
- Channel and pricing strategies will be decisive — distribution strength, partnerships with DSOs and integrated digital offerings materially affect unit economics.
Market dynamics and inflection points
- Regulatory regime tightening — Orthodontic devices such as clear aligners and brackets are treated as Class II medical devices in major markets and require robust 510(k) substantiation (or equivalent). Manufacturers must invest in regulatory affairs and post-market surveillance as core competencies rather than overhead.
- Reimbursement normalization — The 2026 CDT code updates introduce new coding options and clarify claims pathways for several orthodontic procedures. Companies that engage payers and DSOs early will gain commercial leverage when codes are applied at scale.
- Digital and AI enablement — FDA clearances for advanced imaging and AI-assisted diagnostics (e.g., recent 510(k) approvals for AI-enabled 3D cephalometric tools) are accelerating adoption of integrated digital workflows that tie hardware, software and consumables together.
- Channel evolution and DTC retrenchment — Regulatory and corporate retrenchment in certain direct-to-consumer aligner models has shifted volume back to clinically mediated channels, reshaping provider economics and the role of distributors.
- Concentration and consolidation — The competitive landscape shows meaningful concentration among leading technology incumbents, creating attractive targets for vertical integration and strategic partnerships.
Competitive landscape — capabilities that define winners
The market is multi-modal: leading players combine product breadth, digital platforms and channel reach. Below are the capability vectors that distinguish the front-runners we track in the report:
- Align Technology — Market leadership in clear aligner systems and intraoral scanning, with continuing regulatory and product expansions that extend treatment indications and clinical workflows. Their platform-driven model sets the benchmark for integrated consumables + software monetization.
- 3M (Unitek / Clarity) — Strength in both aesthetic and traditional appliance suites, coupled with deep distribution networks and material science competencies that support broad clinical segments.
- Envista (Ormco) — Focused on bracket-and-wire system optimization and lab-enabled services; success rests on clinician efficiency gains and differentiated bracket systems that reduce chair-time.
- DENTSPLY SIRONA — Combines aligner offerings with adjunctive devices (e.g., high-frequency vibration) and a strong route-to-clinic distribution model. Their channel reach and device portfolio make them a strategic integrator in many markets.
- Institut Straumann — Leverages implant/restorative integration to offer digital orthodontic workflows aligned with restorative outcomes, attractive to premium clinics and specialist referral networks.
- Regional/competitive specialists (American Orthodontics, RMO, G&H, Dentaurum, Henry Schein Orthodontics, DB Orthodontics) — These players maintain strong share in fixed-appliance components, consumables and distribution, offering resiliency and margin stability to their customers.
Recent tactical moves matter: Align’s product clearances and CE expansions, Dentsply Sirona’s partnership recognition in cleft care, new aesthetic bracket launches from specialty manufacturers and AI/3D imaging regulatory clearances collectively reshape competitive tactics and create new adjacency plays (e.g., integrated diagnostics + treatment planning).
Strategic implications and a practical playbook for 2026
Here are the priority moves PW Consulting recommends for market participants seeking to convert growth into durable shareholder value. These are practical, prioritized actions — not academic suggestions.
- Invest in regulatory-first product development. Build parallel clinical evidence and post-market surveillance to shorten approval timelines and underpin premium pricing.
- Pursue platform economics. Combine hardware (scanners, aligner manufacturing), software (treatment planning, AI diagnostics) and recurring consumables to increase customer lifetime value.
- Embed reimbursement and payer engagement into commercial launches. Use 2026 CDT updates to create clear billing playbooks for clinics and DSOs.
- Forge distribution and DSO partnerships. Prioritize agreements that secure preferred-provider status, bundled pricing and training commitments to lock-in adoption.
- Target M&A selectively. With market concentration favoring scale, bolt-on acquisitions in digital software, lab capacity or regional distribution can accelerate access to growth corridors.
- Optimize supply chain resilience. Dual-sourcing for critical consumables, localized manufacturing partnerships and inventory-as-a-service models reduce disruption risk and support margin preservation.
- Differentiate through clinical outcomes measurement. Companies that can demonstrate shorter treatment times or improved retention will command pricing and formulary advantages.
- Prioritize customer success and training. Implementation support, telemonitoring, and clinician education convert trial use into longitudinal adoption and recurring revenue.
What the full PW Consulting report delivers (practical contents)
The report is intentionally operational — built for executives, corporate development teams, product leaders and investor due diligence. Highlights include:
- Detailed global market model with historic reconciliation (2020–2025) and a granular forecast (2026–2032) by product class, end-user and region — including sensitivity scenarios and upside/downside drivers.
- Competitive scorecards and supplier strength matrices (technology, manufacturing, regulatory, channel reach) for the core manufacturers and regional challengers.
- Regulatory pathway maps and reimbursement playbooks tied to product archetypes and market-entry timelines across major jurisdictions.
- Commercial go-to-market frameworks: DSO engagement templates, clinic onboarding flows, pricing and discounting simulations, and customer success KPIs.
- M&A target screening and valuation heuristics tailored to acquirers seeking to build scale or technology adjacency.
- Scenario-based strategic options and a 90-day execution roadmap to capture near-term share gains while preserving long-term optionality.
Note: To preserve confidentiality of our primary research and maintain commercial value for paying subscribers, the report reserves detailed segment-level revenues and regional splits for the full document. The overview here intentionally omits those granular tables while summarizing strategic takeaways.
90-day diagnostic and actions
Executives can translate insight into outcomes with a short diagnostic and sprint plan:
- 30 days — Run a regulatory readiness checklist against your product pipeline, map exposure to new CDT code opportunities and validate distribution agreements for 2026 billing cycles.
- 60 days — Pilot a digital workflow bundled offer with a leading clinic or DSO (scanning + planning + aligner subscription) and capture baseline treatment economics.
- 90 days — Define an M&A shortlist or partnership targets; finalize a go-to-market push that leverages clinical evidence and payer engagement to accelerate adoption.
Closing — the strategic choice for 2026
The orthodontic aids market presents a classic medtech inflection: strong demand growth, rapid digitalization and regulatory complexity. For leaders, the question is not whether the market grows — it will at roughly an 8.45% CAGR over the forecast window — but who captures the value embedded in integrated workflows, clinical evidence and channel control. PW Consulting’s full study provides the datasets, competitive benchmarking and tactical playbooks to convert market growth into sustained competitive advantage. Visit our source page to access the complete analysis, segment tables and customized advisory options.
For detailed analysis of this topic, please visit the official page: Orthodontic Aids Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


