



PW Consulting: CPE Antenna Market to Reach USD 2.76B by 2032 at 8.27% CAGR

CPE Antenna Market — Strategic Imperatives for 2026
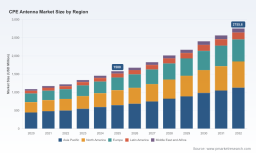
As operators, OEMs and investors set 2026 budgets and product roadmaps, the CPE antenna market is moving from “connectivity utility” to strategic infrastructure. Our PW Consulting market study — base year 2025, forecast horizon 2026–2032 — quantifies this shift. The global CPE antenna market reached ~USD 1,580 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 8.27% across the forecast window, reaching the mid-to-high billions by 2032. These headline figures frame the opportunity; the operational choices you make in 2026 will determine whether you capture premium growth or are relegated to low-margin commodity supply.
Cpe Antenna Market
Why 2026 Is a Strategic Inflection Point
-
Regulatory and spectrum momentum is accelerating mid‑band availability and reshaping deployment economics. Recent policy moves — including reclassification debates, spectrum repurposing proposals in the upper C‑band, and congressional directions to free additional federal spectrum — are steadily lowering the cost-per-bit for fixed wireless access (FWA) and creating new commercial windows for mid‑band CPE. Timing of auctions and rulemaking between 2026–2028 will materially change operator investment horizons.
Cpe Antenna Market -
Technology convergence is compressing product cycles. Advances in integrated multi‑antenna systems, AI-assisted beamforming and combined Wi‑Fi/5G gateway designs are creating differentiated performance tiers rather than simple “more dBi” metric battles. Design wins secured in 2025–26 will determine market share through 2028–30.
Cpe Antenna Market -
Commercial models are evolving. Operators are experimenting with hybrid CAPEX/OPEX models, device-as-a-service bundles and managed Wi‑Fi plans that attach long‑tail services to the physical CPE — increasing lifetime value but requiring closer coordination between antenna design, firmware, and service orchestration.
What Our Research Delivers — Practical Outputs for 2026 Decision-Making
-
Robust market sizing and demand scenarios (conservative / baseline / accelerated) for 2026–2032 with dynamic sensitivity to spectrum timing, macro growth and price erosion.
-
Actionable product roadmaps that map antenna architectures (internal integrated vs external high‑gain, panel vs blade vs omnidirectional, outdoor enclosure spec) to operator deployment cases and procurement specs.
-
Supply‑chain and manufacturing heat maps (tiered suppliers, lead times, sourcing risks), together with an OEM/ODM partner prioritization framework.
-
Vendor scorecards and M&A playbooks — technology fit analyses, integration complexity estimates, and valuation levers — based on technical IP, channel access and production scale.
-
Commercial templates: procurement checklists, RF performance acceptance tests, and go‑to‑market bundle designs for operator and retail channels.
-
Ready‑to‑use Excel models and scenario trees that let leadership convert strategic choices into 2026 P&L and capex forecasts.
To respect the “preview” intent of this article, granular regional and application splits and the full set of segment tables are reserved for the full report — those revenue and percentage breakdowns are the competitive intelligence that will inform precise tactical moves.
Key Demand and Technology Vectors to Prioritize in 2026
-
Mid‑band FWA optimization. The most immediate near‑term demand driver is fixed wireless access using expanded mid‑band spectrum. Antenna subsystems that extract spectral efficiency (through higher usable gain, improved front-to-back ratios and multi‑port MIMO) will be differentiators. Proprietary mid‑band boosters and multi‑element indoor systems are examples of where performance premiums are emerging.
-
Embedded Wi‑Fi evolution. With the arrival of Wi‑Fi 7 and forthcoming Wi‑Fi 8 innovations, gateway vendors need embedded antenna technologies that support higher channel widths, multi‑link aggregation and tighter coexistence between cellular and Wi‑Fi radios.
-
Outdoor ruggedization and mmWave integration. For rural and enterprise edge use cases, rugged IP‑rated enclosures supporting broad frequency coverage (from sub‑6 through extended C‑band and selected mmWave slices) will be critical, especially where satellite or hybrid backhaul is paired with FWA CPE.
-
AI and adaptive beam management. Solutions that combine hardware design with AI‑driven beam scanning and automatic tuning are moving from lab demos into commercial design wins — these systems materially increase throughput and resilience in dense and mobility‑challenged environments.
Competitive Landscape — Who Matters and Why
The market displays moderate consolidation: the top three players account for just over one‑third of market share, while the top five exceed fifty percent — a structure that indicates scale advantages but also ample room for specialized suppliers and regional champions. Strategic positioning falls into three archetypes:
-
Technology and premium system integrators. Companies investing in proprietary antenna subsystems and integrated gateway solutions are targeting operator design wins and premium ASPs. Example: Vantiva’s third‑generation Indoor5G™ 8Rx system (patented mid‑band boosters, high efficiency) positions it to win urban FWA deployments where indoor performance and spectrum efficiency command price premiums.
-
Scale and platform OEMs. Large multi‑product vendors with broad channel access and vertical integration capabilities can push volume‐driven deployments and bundled offers. ZTE’s next‑gen 5G‑A FWA lineup combining indoor AI antenna solutions and outdoor mmWave-capable CPE shows how platform breadth can secure both operator and wholesale channels.
-
Niche specialists and OEM/ODM producers. Manufacturers focusing on high‑gain outdoor antennas, rugged enclosures, or contract manufacturing fill critical roles in the value chain. Firms with extensive testing capability (anechoic chambers) and IP in manufacturing processes are attractive partners for both established brands and new entrants seeking fast time‑to‑market.
Notable commercial moves underscore these dynamics: high‑visibility product launches and design wins in late 2025–2026 point to where early hardware differentiation will be concentrated. Providers with multi‑year gateway design wins (particularly for Wi‑Fi 7/8) gain multi‑cycle revenue visibility and influence over operator spec choices.
Implications for Enterprise Decision‑Makers — A 2026 Playbook
-
Product strategy: Prioritize modular antenna platforms that allow firmware‑driven beamforming upgrades and swappable external modules. Allocate R&D to mid‑band efficiency and AI signal control rather than marginal dBi increases alone.
-
Partnerships: Lock in at least one design‑win path with a gateway OEM and one with an outdoor CPE specialist. Design wins secured in 2026 yield commercial deployments in 2027–2028 when spectrum auctions and operator rollouts accelerate.
-
Supply chain resilience: Qualify dual sources for RF front‑end components and seek near‑shoring options for critical assembly. Use independent anechoic testing to validate vendor claims in procurement.
-
Regulatory engagement: Advocate proactively on spectrum allocation timelines and R&O rules that affect device certification. Understand the interaction between national net‑openness rules and operator commissioning requirements for FWA equipment.
-
M&A and investment: Consider tuck‑ins for antenna IP or AI signal‑processing capabilities if your strategy is to climb the value chain; prioritize targets with validated design wins or proprietary mid‑band boosters over pure volume manufacturers.
Risks and Scenario Planning
-
Policy timing risk: Delays or narrower-than-expected spectrum releases compress demand and depress near‑term unit economics. Contingency: prioritize designs that are frequency‑agile and can be retuned through software/filters.
-
Component and testing bottlenecks: Lead times for RF components and access to validation labs can slow launches. Contingency: invest in in‑house RF measurement capability or pre‑paid lab slots with key testing houses.
-
Competitive price pressure: Mass‑market scale players can drive commodity pricing. Contingency: preserve margin through service differentiation (managed customer experience, firmware features) and targeted premium SKUs for operator deals.
How to Use the Full PW Consulting Report
The full report contains the guarded segment‑level intelligence that operational teams need: a region-by-region and application-by-application decomposition, product‑type demand curves, vendor revenue estimates, BOM‑level cost checkpoints and downloadable financial models set to your planning horizon. These granular tables and supplier profiles are intentionally withheld from this preview to preserve their competitive value. If your 2026 strategy requires concrete procurement specifications, channel plans, or an M&A target shortlist, the full dataset — and the consulting engagement that accompanies it — will convert the strategic directions above into executable 90‑ and 180‑day plans.
In short: the market is large enough to reward differentiation, concentrated enough that scale matters, and soon to be reshaped by spectrum policy and technology convergence. Companies that align product architecture, procurement resilience and partner ecosystems in 2026 will capture the premium growth that the projected ~8.27% CAGR creates. PW Consulting’s full CPE Antenna Market study provides the calibrated forecasts, vendor intelligence and playbooks required to turn that opportunity into measurable revenue and margin outcomes.
For detailed analysis of this topic, please visit the official page: Cpe Antenna Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


