



PW Consulting: Corn Flour Market to Reach USD 8.63 Billion by 2032 at 4.25% CAGR

Corn Flour Market 2026: Strategic Imperatives for Decision-Makers — PW Consulting Industry Brief
By PW Consulting — Senior Strategic Advisor & Chief Industry Analyst
Corn Flour Market
Executive snapshot
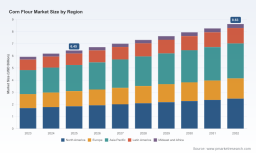
The global corn flour market is entering a period of steady, structurally-driven growth. After a multi-year historical review (2020–2025), our baseline analysis identifies the market at approximately USD 6.45 Billion in 2025 (base year). Under conservative demand- and supply-side assumptions, the market is projected to expand to roughly USD 8.63 Billion by 2032, reflecting a compound annual growth rate (CAGR) of about 4.25% over the 2026–2032 forecast window.
Corn Flour Market
This industry brief previews the full PW Consulting Corn Flour Market study and translates our quantitative findings into pragmatic strategic guidance for 2026 corporate decision-making. We intentionally reveal directional market dynamics, methodology rigor, and practical use cases while withholding detailed sub-segmentation datapoints to preserve the study’s exclusive value for subscribers.
Corn Flour Market
Why this matters for 2026 strategy
- Portfolio prioritization: Growth is predictable but not uniform — stable mid-single-digit expansion means firms must choose where to invest for higher returns versus protecting volume-driven businesses.
- Capex & capacity planning: Manufacturers and ingredient suppliers need forward-looking demand curves and input-price scenarios to time mill upgrades, capacity expansions, or contract manufacturing partnerships without overexposure to cyclical inventory risk.
- Procurement & price risk: Corn price dynamics remain a primary margin lever; procurement strategies (fixed contracts, indexed purchasing, hedge overlays) will materially influence 2026 earnings sensitivity.
- Innovation & premiumization: Premium, specialty, and functional applications offer margin uplift — but they require R&D, labeling, and targeted distribution investments aligned to consumer trends.
- Regulatory & trade-readiness: Recent regulatory shifts and tariff developments mean supply-chain flexibility and compliance readiness are non-negotiable for exporters and multinational processors.
What the full report delivers — practical, action-oriented content
Our full Corn Flour Market report is structured to convert macro insight into executable initiatives. Key deliverables include:
- Transparent market-sizing methodology with bottom-up and top-down reconciliations, sensitivity testing, and alternate scenarios for high/low demand outcomes.
- Seven-year forecasting models (2026–2032) with monthly-to-annual cadence options for demand planning and capex phasing.
- Supply-chain maps by milling configuration and logistics archetype, highlighting lead times, critical bottlenecks, and cost-to-serve benchmarks.
- Input-price scenario suite: spot, forward, and stress-case trajectories for corn and energy that feed margin-scenario matrices for manufacturers and ingredient buyers.
- Go-to-market playbooks for ingredients (e.g., industrial, retail, foodservice), including route-to-market options, co-manufacturing criteria, and private-label risk assessments.
- M&A & partnership target screening framework: a scored universe of strategic fits based on product portfolio, geography, capacity, and ESG alignment.
- Regulatory compliance checklist and labeling implications across key jurisdictions, plus an assessment of how trade-policy shifts could alter sourcing economics.
- Operational improvement diagnostics: recommendations for yield uplift at wet- and dry-milling operations, energy optimization, and waste valorization opportunities.
Market dynamics shaping 2026 choices
Several ongoing dynamics will determine which players capture disproportionate value in 2026 and beyond:
- Input-price volatility: USDA’s projection of a season-average corn price for 2025/26 and contemporaneous futures pricing indicate continued sensitivity to harvest outcomes and macro demand (including feed and ethanol). Firms must model procurement under both normalized and stress-price regimes.
- Regulatory clarity: Standards of identity and labeling requirements (e.g., national food codes) remain a structural constraint for product reformulation and cross-border trade. Compliance-driven reformulation timelines must be built into product-development roadmaps.
- Trade-policy friction: Recent tariff activity and legal rulings have injected uncertainty into import/export economics; supply-chain reworking (nearshoring, multi-sourcing) is a prudent defensive measure.
- Sustainability and traceability: Buyer preference is accelerating toward regenerative sourcing, lower-carbon milling, and documented supply chains. Sustainability credentials are increasingly table stakes for large retail and foodservice contracts.
Competitive landscape — who to watch and what they signal
The corn flour market sits at the intersection of large agribusiness integrators, specialized ingredient innovators, and regional/heritage millers. Each cohort brings distinct capabilities and strategic intent that will influence competition, partnership opportunities, and consolidation dynamics in 2026.
- Global processors (Archer Daniels Midland, Cargill, Bunge): These firms leverage scale, integrated origination, and diversified end markets. Their strengths are in supply security, contract logistics, and large-scale food-ingredient solutions. Recent sustainability initiatives and new-plant investments reflect a dual focus on decarbonization and feedstock-to-fuel economics — moves that can compress supplier risk for buyers but also escalate competitive intensity in commoditized channels.
- Ingredient specialists (Ingredion, Grain Millers): These companies compete on formulation expertise, functional performance, and ingredient customization. They are natural partners for consumer-packaged goods firms seeking clean-label texture and shelf-life solutions. Expect continued product development around texturizing functionalities and starch-protein blends that enable reformulation away from higher-cost inputs.
- Heritage and nixtamal-focused producers (Gruma, Azteca Milling, Minsa): With deep know-how in traditional masa and nixtamalized flours, these players dominate cultural and premium segments. Their IP in processing and recipe adaptation creates high barriers for entrants aiming at heritage categories, and they are attractive targets for CPGs aiming to secure authenticity credentials.
- Specialty and retail-focused mills (Bob’s Red Mill, King Arthur Baking, regional millers): These firms command premium positioning through organic, non-GMO, and gluten-free claims. They are well positioned to capture retail and specialty foodservice premiums, though scale limitations may prompt contract manufacturing or distribution alliances to meet broader demand.
- Regional & contract processors (SEMO Milling, LifeLine Foods, Mittal Cornezza): These players offer flexible tolling, private-label, and B2B supply solutions. Their value lies in agility and cost-competitive regional fulfillment; they often form the backbone of contingency supply strategies for larger buyers.
The mix of scale, specialty, and regional players suggests a market where strategic collaborations — rather than pure acquisitions — may deliver the most immediate value in 2026. Examples include co-located milling partnerships with retailers, sustainability-linked offtake agreements, and joint R&D on functional flours.
Recent developments with strategic implications
- Major processor sustainability programs — for example, large global processors introducing regeneratively sourced flours milled with renewable electricity — will accelerate buyer requirements for origin verification and may shift premium capture toward vertically integrated suppliers.
- New downstream or adjacent-capacity announcements (e.g., processing and ethanol facilities) can alter local corn balances and logistics flows; firms should re-evaluate feedstock availability and tolling economics in affected corridors.
- Commodity-price signals and futures levels through early 2026 emphasize the value of dynamic hedging frameworks and flexible supply contracts to protect margins during price swings.
- Trade-policy and court rulings that modify tariff regimes create windows for import growth in some supply-constrained markets — an opportunity for agile exporters and tolling providers.
Strategic recommendations for 2026 (prioritized)
- Build adaptive sourcing playbooks: Implement multi-tier supplier strategies that combine long-term offtake with short-term spot levers and hedges tied to price triggers.
- Invest selectively in premium innovation: Allocate R&D and commercial resources to high-margin, specialty blends and labeling claims favored by retail and foodservice channels.
- Partner for sustainability: Form origin-level partnerships to secure regenerative or low-carbon inputs; align commercial incentives with farm-level practices to lock in premiums.
- Operationalize scenario planning: Use the report’s forecast and stress scenarios to sequence capex, manage working capital, and design contingency logistics pathways.
- Explore targeted alliances: For mid-size players, pursue co-manufacturing, distribution-sharing, or minority investments with specialty millers to access capabilities without full integration risk.
How PW Consulting’s study supports execution
Our full report operationalizes the above recommendations with the tools procurement, finance, and commercial teams need to act in 2026: granular forecasting models, supplier-scorecard templates, scenario-ready P&L impacts, and a screened M&A/partnership universe. Subscribers receive both the evidence base and the execution checklists required to move from strategy to measurable outcomes within twelve months.
Next steps
PW Consulting’s Corn Flour Market study is designed as a decision-support asset for 2026. If your organization is evaluating capacity investments, re-shaping procurement, launching premium products, or exploring M&A in the corn value chain, the full report will provide the detailed segmentation, financial models, and supplier-level diligence you need. Contact our client services team to arrange a briefing, data-room access, or a tailored advisory workshop that maps findings to your strategic priorities.
Note: This preview emphasizes high-level market sizing, growth trajectory, competitive positioning, and actionable implications while withholding detailed sub-segment data reserved for the full report subscription.
For detailed analysis of this topic, please visit the official page: Corn Flour Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


