



PW Consulting: Biomass Power Equipment Market to reach USD 201.46B by 2032 (6.99% CAGR)

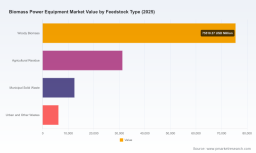
Biomass Power Equipment Market — Strategic Outlook for 2026 Decision-Making
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused preview of our full Biomass Power Equipment Market study — a practical intelligence package designed to inform capital allocation, partnership selection, and technology choices as organizations finalize strategies for 2026. Our analysis is grounded in a comprehensive market model (base year 2025, forecast 2026–2032) and shows the global market expanding from USD 125,458.26 Million in 2025 to USD 201,458.54 Million by 2032, reflecting a compound annual growth rate (CAGR) of 6.99%. This trajectory, and the structural dynamics behind it, will materially influence project economics, procurement timelines, and M&A activity over the next three years.
Biomass Power Equipment Market
Why 2026 Is an Operational and Strategic Inflection Point
- Policy-driven demand acceleration. Recent and prospective policy interventions—ranging from strengthened renewable targets in major economic blocs to tax incentives and investment credits—have created a near-term window for project developers and OEMs to lock in favorable financing and subsidy conditions. Timing investments to capture these policy windows is a high-return move in 2026.
- Carbon and energy-market economics are reshaping fuel choice. Elevated carbon prices in emissions trading systems and more aggressive national decarbonization roadmaps increase the economic case for biomass retrofit and replacement of fossil-fired capacity in jurisdictions where sustainability credentials are accepted for biomass feedstocks.
- Feedstock and component cost volatility matters. Commercial wood pellet and other biomass feedstock prices, plus the unit costs for key equipment (e.g., grate stoker systems), have shown meaningful bid-ask spreads in recent project tenders; supply-chain negotiations and contracting strategies in 2026 will materially affect long-term project IRRs.
- Technology performance is advancing quickly. Efficiency improvements and hybridization strategies demonstrated by incumbent OEMs compress payback periods for higher-capex, higher-efficiency solutions. Buyers that optimize for lifecycle cost rather than first-cost will capture superior margins or lower levelized cost of energy (LCOE).
What PW Consulting’s Full Report Delivers (Practical, Implementable)
- Robust top-down market sizing and forecast: granular annual modeling from 2026–2032 with scenario variants tied to policy and commodity shocks.
- Technology and feedstock decision frameworks: actionable matrices that map technology archetypes (combustion, fluidized bed, gasification, anaerobic digestion) to typical plant scales, operational profiles, and feedstock elasticity — enabling quick narrowing of viable options for a given project mandate.
- Procurement & CapEx/O&M playbooks: standardized bid templates, cost benchmarking, and assembly-level component cost ranges to accelerate vendor selection and negotiate fixed-price EPC contracts.
- Policy & incentive integration tools: jurisdictional incentive trackers and templates that translate headline subsidies and tax credits into project-level cashflow impacts and investor-return scenarios.
- Supply chain risk maps: prioritized mitigation strategies for feedstock sourcing, component lead times, and logistics, including contingency procurement paths that preserve project timelines.
- Commercial and contracting models: off-take, tolling, and co-generation commercial term sheets, plus model financial covenants that reflect biomass-specific risks.
- M&A and partnership playbook: valuation frameworks for bolt-on acquisitions and JV structures that accelerate market entry while de-risking supply and permitting exposures.
The above deliverables are designed as executable tools — not just narrative — so commercial teams can move from strategy to procurement and execution with clarity and speed. To preserve competitive value and to respect client confidentiality thresholds, the public preview intentionally omits certain segment-level monetary and regional share tables; the full report contains those stratified datasets and downloadable models.
Biomass Power Equipment Market
Competitive Landscape: Players, Positions, and Tactical Moves to Watch
- Valmet (Espoo, Finland) — Strengths: full-plant capability spanning boilers, turbines, and flue gas cleaning for multiple combustion platforms. Tactical implication: attractive partner for developers seeking turnkey delivery and advanced emissions compliance. Recent commissioning of a biomass-fired CHP plant demonstrates continued commercial execution on mid-to-large scale projects.
- ANDRITZ (Graz, Austria) — Strengths: fluidized bed combustion expertise and turnkey deliveries. Tactical implication: suited for projects focused on efficient biomass utilization and fuel flexibility; maintain ANDRITZ on shortlists where fuel variability is expected, as evidenced by recent European orders.
- Babcock & Wilcox (Akron, USA) — Strengths: grate and hybrid stoker technologies optimized for co-firing and dedicated biomass. Tactical implication: strong candidate for retrofit projects and for clients prioritizing modular staging; recent grid connections validate commercial reliability.
- Mitsubishi Power (Yokohama, Japan) — Strengths: integrated high-efficiency steam turbines and advanced combustion systems. Tactical implication: preferred where top-tier thermal efficiency and long-term performance guarantees are procurement priorities; recent efficiency milestones highlight R&D-to-market velocity.
- Siemens Energy (Munich, Germany) & GE Vernova (Cambridge, USA) — Strengths: turbine optimization and systems integration for variable fuel inputs and hybrid configurations. Tactical implication: ideal partners where integration with broader grid assets or hybrid gas/steam cycles is envisioned.
- Kraftwerke Mannheim (Mannheim, Germany) — Strengths: operator-supplier model with European co-generation experience. Tactical implication: partner of choice for utilities and municipalities pursuing operational know-how and O&M excellence.
- Zibo Zichai New Energy (Zibo, China) — Strengths: cost-competitive gasifiers and equipment for small-to-medium plants. Tactical implication: strong contender for distributed generation projects where capital efficiency and local content are decisive.
Market concentration metrics indicate an industry that remains moderately fragmented, leaving room for consolidation and alliance strategies. Incumbents are using a mix of turnkey project wins, efficiency innovations, and selective geographic plays to expand footprints — presenting opportunities for M&A, technology licensing, and OEM-developer partnerships.
Biomass Power Equipment Market
Key Dynamics That Will Drive 2026 Decisions
- Policy and incentives: National investment credits and renewable targets materially change the NPV calculus for new-build projects and repowering initiatives. Structuring bids to capture those windows is critical.
- Carbon pricing: Elevated allowance prices increase the competitiveness of biomass solutions against fossil alternatives; buyers should model carbon-price sensitivities across 5–10 year horizons.
- Feedstock markets: Feedstock cost and availability will be a gating factor for project sizing and contract tenors. Hedging, vertical integration, or long-duration supply agreements should be prioritized in 2026 procurement strategies.
- Component supply and CapEx: Equipment lead times and the unit economics of core systems (e.g., grate stoker modules) will shape project schedules and financing structures; early procurement windows reduce schedule risk.
- Operational efficiency and retrofits: Efficiency upgrades and hybridization pathways materially change lifetime returns — businesses should evaluate retrofit options for existing assets as potential quick wins.
Actionable Strategic Imperatives for Executives
- Prioritize feedstock security through long-term contracts, strategic inventories, or upstream investments. Short-term savings on feedstock can erode returns if supply reliability is compromised.
- Opt for technology decisions that align with long-term fuel availability and grid-service requirements; favor solutions that offer modular scalability and retrofit pathways.
- Lock in EPC and major-equipment lead times in 2026 to avoid inflationary and supply-chain exposure; consider contractor-financed milestones tied to performance guarantees.
- Design financing structures that capture available tax credits and grants, and stress-test models for carbon-price volatility and fuel-cost inflation scenarios.
- Use M&A and JV structures to accelerate entry in fragmented markets where local operating know-how and permitting relationships are decisive.
Decision Scenarios — How to Use This Intelligence
- Utility decarbonization track: Prioritize high-efficiency steam turbines and long-term feedstock contracts; evaluate retrofits to existing coal plants as a near-term emissions reduction lever.
- Independent power producer track: Emphasize modular plant options and flexible off-take agreements; structure financing to capture available investment tax credits and subsidies.
- OEM and equipment supplier track: Focus R&D on fuel flexibility and emissions control, and pursue strategic alliances to offer turnkey solutions that reduce buyer integration risk.
Each of these scenarios is supported in the full report by modelled P&L, sensitivity runs, supplier scorecards, and a prioritized action list for the next 12–18 months.
Next Steps — Where This Preview Leaves You
This preview synthesizes the high-level market trajectory, competitive patterns, and tactical pathways that will shape biomass power equipment investment and procurement decisions in 2026. It intentionally highlights strategic levers and refrains from publishing the full segment-level figures and regional breakouts — those detailed tables, downloadable financial models, and supplier scorecards are part of the full PW Consulting report.
If your team is preparing capital plans, supplier RFPs, or M&A strategies for 2026, the full report will accelerate decision-making by providing the calibrated models and operational playbooks necessary to convert strategy into executable projects. Visit our report page to access the complete dataset, scenario models, and procurement templates (full access includes editable financial models and vendor evaluation tools).
For detailed analysis of this topic, please visit the official page: Biomass Power Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


