



PW Consulting: Heavy Industry Hydraulic Systems Market to Grow at 4.85% CAGR (2026–2032)

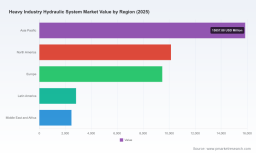
Heavy Industry Hydraulic System Market — Strategic Intelligence for 2026 Decision-Makers
As capital budgets reopen and heavy industry operators accelerate decarbonization and digitalization plans, hydraulic systems remain an indispensable element of the global heavy equipment value chain. PW Consulting’s new market study — anchored on a 2025 base year and projecting through 2032 — quantifies that importance and translates it into executable strategic options. The market is set to expand at a steady mid-single-digit pace (4.85% CAGR for the 2026–2032 forecast window), moving from a large multi‑billion-dollar base in 2025 toward materially higher aggregate revenue by 2032. For C-suite leaders, corporate strategists, and business development teams, the practical question in 2026 is not whether hydraulics matter, but how to allocate scarce capital and talent to capture resilient, margin-accretive growth while managing rising regulatory and input-cost volatility.
Heavy Industry Hydraulic System Market
Why this study matters in 2026
-
Timing and trajectory: The forecast period (2026–2032) captures a decisive phase in the heavy-equipment refresh cycle. Capex programs, electrification pilots, and retrofit projects that are decided in 2026 will reach execution or scale within our forecast horizon — making early strategic choices high-leverage.
Heavy Industry Hydraulic System Market -
Policy and standards acceleration: New standards such as ISO 18464:2025, together with energy-efficiency mandates, materially change product design constraints. Manufacturers that internalize these constraints now will reduce rework and margin erosion later.
Heavy Industry Hydraulic System Market -
Input-cost and supply risk: Steel-price volatility and concentrated raw-material supply chains continue to pressure component costs and supplier reliability. Procurement and product-design strategies developed this year will determine the robustness of supply for the next 5–7 years.
-
Technology inflection: The industry is balancing proven hydraulic architectures with hybrid and electrified options (including electrified hydraulic power units — eHPUs) and increasingly connected control layers. The pace and economics of these transitions are uneven across application classes; our study provides the decision frameworks to prioritize investments.
Market structure and competitive dynamics — what to watch
Our analysis shows a market that blends global incumbents with regionally strong specialists. Market concentration is moderate: the top three firms account for roughly one-third of the market while the top five capture under half. This structure creates a dual pathway for competitive advantage — scale-based plays from the leading incumbents and focused differentiation opportunities for nimble specialists.
Key established players continue to set technology and quality benchmarks: large engineering OEMs and system integrators are investing in connected controls, higher-pressure architectures, and energy-optimization packages. Select independent suppliers are pursuing narrow but deep plays on filtration and wear-resistant components, or on integrated electro-hydraulic subsystems tailored to off-highway and mining applications. Newer entrants and regional champions accelerate adoption through trade-show launches and targeted OEM partnerships — recent product reveals and awards in major 2026 shows demonstrate the ongoing innovation cycle.
-
Strategic positioning matters more than ever: firms that combine systems engineering, software-enabled controls, and service-based revenue models will capture a disproportionate share of aftersales and lifecycle margin.
-
M&A and partnership activity will be selective: buyers are targeting capabilities in electrified power units, system integration, and digital services more than low-margin commodity components.
-
Regional go-to-market remains relevant: global scale helps with R&D and supply chain resilience, but local engineering and aftermarket presence determine success in heavy industries with site-specific requirements.
Technology and regulatory tailwinds that shape winners
Three linked trends will define competitive outcomes across the forecast horizon:
-
Energy efficiency and compliance: With ISO 18464:2025 and strengthening emissions/efficiency mandates, product roadmaps must incorporate energy-optimized circuit design and loss-reduction technologies. Early adopters can exploit first-mover advantages in bidding for large retrofit and greenfield projects.
-
Electrification and hybrid architectures: eHPUs and hybrid hydraulic-electric drivetrains reduce on-site emissions and offer lifecycle cost benefits in many duty cycles. Commercial viability depends on component reliability, integration skill, and TCO-based sales models that account for fuel, maintenance, and downtime.
-
Digitally enabled reliability: Predictive maintenance, remote diagnostics, and control-layer optimization translate into lower OPEX and higher attachment uptime — and thus into monetizable service contracts. Companies that marry hydraulic expertise with software platforms will be best positioned to grow aftermarket revenues.
Recent market signals — what the shows and awards reveal
Targeted industry events in early 2026 offered useful directional signals. Several exhibitors showcased next-generation mobile hydraulics and purpose-built cylinder and pump solutions at major North American trade shows; an electrified hydraulic power unit secured a top new-product award at a leading agricultural expo. These public demonstrations — from both established suppliers and newer specialists — confirm rising customer interest in electrified subsystems, application-specific performance tuning, and integrated testing platforms. For strategists, these signals imply that product maturity, customer validation, and price points are aligning to enable broader commercial adoption in the near term.
What the PW Consulting report delivers (practical contents)
Our study is designed to be hands-on and decision-oriented for 2026 corporate planning cycles. Highlights include:
-
Transparent market sizing and forecast methodology, including base-year reconciliation and scenario-based projections across a 2026–2032 forecast horizon.
-
End-user demand drivers and procurement behavior profiles: capital vs. operating cost sensitivities, retrofit decision triggers, and service-interval economics.
-
Technology deep dives: comparative TCO analyses for conventional hydraulics, hybrid architectures, and electrified hydraulic power units; control-layer integration and cybersecurity considerations for connected systems.
-
Value-chain mapping and supplier risk assessment that identify choke points (raw materials, filtration, control semiconductors), mitigation levers, and strategic sourcing playbooks.
-
Competitive benchmarking and capability matrices across system suppliers, component specialists, and OEM integrators, coupled with M&A and partnership screening templates.
-
Commercial playbooks for market entry and scale: channel strategies, aftermarket enhancement tactics, pricing frameworks, and retrofit program designs tailored to heavy-industrial customers.
-
Executive-ready decision tools: investment prioritization frameworks, sensitivity analyses for steel-price shocks and regulatory tightening, and phased implementation roadmaps for 2026 capital plans.
Note: The full report contains granular splits, component- and regional-level scenarios, proprietary segmental tables and financial templates that are intentionally omitted from this preview to preserve the report’s exclusive value.
How to convert insight into 2026 actions
-
Rebalance R&D toward integration: Shift incremental R&D budgets from component improvement to system-level integration (electro-hydraulic controls, eHPU uptime, and digital diagnostics) to increase capture of lifecycle value.
-
Hedge raw-material exposure: Implement a two-tier procurement approach — strategic long-term steel contracts for core production and tactical spot positions for opportunistic sourcing — and update bill-of-materials designs to reduce steel intensity where feasible.
-
Prioritize retrofit economics: Develop retrofit bundles that emphasize short payback for high-utilization assets in mining and infrastructure — backed by financing or outcome-based contracts to lower buyer resistance.
-
Build aftermarket-as-a-service propositions: Monetize predictive-maintenance insights through subscription models that combine remote monitoring, parts-on-demand logistics, and uptime guarantees.
-
Design M&A with capability inflection in mind: Target acquisitions that offer direct capability jumps in electrified subsystems, software platforms, or specialized filtration and wear components rather than pure-volume roll-ups.
Final takeaways for 2026 strategic planning
Hydraulics will remain central to heavy-industry productivity through 2032, but the basis of competition is shifting. Firms that integrate energy-efficient engineering, electrified subsystems, and software-enabled lifecycle services will win premium returns. Conversely, players relying on commodity differentiation face margin compression and acquisition vulnerability unless they pursue structural change. The market’s moderate concentration means there is room for both scale plays and focused specialists, but successful execution requires clarity on regulatory scenarios, raw-material risk, and the economics of electrified alternatives.
PW Consulting’s Heavy Industry Hydraulic System Market study provides the empirical foundation — robust market sizing, scenario modeling, and operational playbooks — to convert these insights into action. For executives preparing 2026 capital allocations, technology roadmaps, or M&A targets, the study offers a pragmatic, prioritized path to secure competitive advantage in a market growing at a 4.85% CAGR through 2032.
To access the full set of segment-level intelligence, competitive scorecards, and investment-ready templates, visit the PW Consulting report page for this study.
For detailed analysis of this topic, please visit the official page: Heavy Industry Hydraulic System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


