



PW Consulting: Recovered Carbon Black (RCB) Market to Grow at 11.5% CAGR (2026–2032)

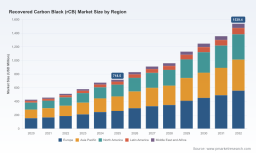
Recovered Carbon Black (rCB) Market — Strategic Briefing for 2026 Decision-Makers
Executive snapshot
Recovered carbon black (rCB) has moved rapidly from niche sustainability pilots into a commercially material segment of the carbon black industry. Our PW Consulting Recovered Carbon Black Rcb Market study—anchored on a 2025 base year and a 2026–2032 forecast horizon—documents a clear, investment-grade growth trajectory: the rCB market expanded materially between 2020 and 2025 and is projected to compound at a double-digit clip (11.5% CAGR) into the early 2030s. By 2025 the market reached a level that demands serious strategic attention from tire makers, masterbatch formulators, coatings companies and raw-material traders; by 2032 the market is expected to be more than double the size it was in 2020.
Recovered Carbon Black Rcb Market
Why this matters for 2026 corporate strategy
-
Supply security & cost resilience: rCB introduces a new upstream vector that can reduce exposure to fossil-derived feedstock pricing cycles. For companies deciding 2026 procurement strategies, rCB supply agreements and feedstock partnerships can be structured to complement traditional carbon black sourcing while de‑risking long-term cost volatility.
Recovered Carbon Black Rcb Market -
Regulatory arbitrage and market access: policy moves—most notably European recognition of tire pyrolysis as a recovery process and the emergence of ISCC PLUS for circular carbon—create a compliance and commercial pathway for rCB to be treated as a non‑waste, tradeable input. Firms adjusting product specifications or sustainability claims in 2026 will need to embed certification prerequisites into procurement contracts.
Recovered Carbon Black Rcb Market -
Product strategy and margin management: rCB’s current material properties (purity levels that are lower than top‑grade virgin carbon black) create both opportunity and constraint. 2026 decisions will hinge on pragmatic product segmentation—where to deploy rCB blends without compromising performance, and where to retain virgin carbon black for high‑stress applications.
-
M&A and capex prioritization: the rCB value chain is consolidating but far from mature (market concentration shows leading groups do not yet dominate the sector). For corporates evaluating inorganic growth or greenfield investments in 2026, the market offers attractive bolt‑on and joint‑venture prospects, particularly for firms that can marry feedstock access to downstream integration.
Market trajectory — what the headline data says
Our modeling, which synthesizes historical data and primary interviews across the value chain, shows robust expansion from the early 2020s into the 2030s. After a multi‑year ramp from 2020 to 2025, the market’s compound annual growth rate during the forecast window points to sustained demand pull and accelerating commercialization. This macro momentum is driven by three structural forces: increasing tire and rubber recycling rates, industrial adoption for lower‑risk elastomer and non‑tire applications, and policy frameworks that reward circular inputs.
Competitive landscape — who to watch (and why)
The rCB competitive set is populated by technology‑led specialists and strategic initiatives from incumbent tyre and chemical players. Key profiles include:
-
Pyrolyx AG (Germany) — A commercial pyrolysis producer that has moved from demonstration to industrial production. Pyrolyx’s early plant commercialization provides practical evidence that scaled rCB supply can meet industrial reinforcement specifications, supporting integration strategies for downstream users.
-
Black Bear Carbon (Netherlands) / Michelin partnership — Backed by a major tire manufacturer, this operation is emblematic of the “buyer‑backed” approach to feedstock security and quality control. Strategic partnerships of this sort materially shorten commercialization timelines and reduce technical adoption risk for tyre makers.
-
Enviro AB (Sweden) — Focused on certification and compliance, Enviro’s attainment of circularity credentials demonstrates the importance of verified sustainability chains for market acceptance, especially in Europe.
-
Hi‑Green Carbon (India) — A lower‑cost regional producer whose ISCC‑certified production lines and proximity to feedstock pools illustrate the geographic arbitrage and trade flows that will shape regional supply dynamics.
Market concentration remains moderate: the top three and top five suppliers do not yet command an overwhelming share of the market, leaving room for new entrants and consolidation. That balance favors strategic buyers who can secure preferential supply or form joint ventures without paying monopoly premia.
Regulatory and technical dynamics impacting 2026 decisions
-
Regulatory recognition and certification: The EU Waste Framework’s treatment of pyrolysis outputs and the adoption of ISCC PLUS establish a compliance framework that allows rCB to be commercially used and marketed as circular. Companies planning 2026 product claims must lock in certified supply and ensure mass‑balance bookkeeping.
-
Purity and application scope: rCB purity presently sits below the highest‑performance virgin grades. This technical constraint will dictate a phased adoption: early wins will be in non‑critical rubber goods, some plastics/masterbatch formulations and selected coatings/inks, with gradual penetration into higher‑performance tire compounds as R&D advances.
-
Trade and tariffs: Regional fiscal treatments (including import duties in certain jurisdictions) will influence global sourcing strategies. These are tangible near‑term considerations for companies designing 2026 cross‑border procurement programs.
What our report delivers — practical outputs for 2026 action
The PW Consulting Rcb Market report is intentionally built for decision makers who need executable recommendations, not just high‑level commentary. Key deliverables include:
-
Global market model with scenario and sensitivity analysis—enabling buyers and investors to stress‑test demand, feedstock availability and price pathways without exposing proprietary segment splits in this preview.
-
Supplier due‑diligence and scorecard toolkit—covering technology maturity, certification status, feedstock security, and commercial reliability to accelerate vendor selection.
-
Procurement playbook—templates for offtake agreements, quality acceptance criteria, and contract provisions that incorporate certification and traceability clauses.
-
Commercial adoption roadmap—segment‑by‑segment go‑to‑market sequencing, pilot design checklists, and KPI frameworks to measure performance during 2026 rollouts.
-
CapEx and investment decision matrix—an interactive framework for evaluating greenfield vs. JV vs. supplier partnerships, with trigger thresholds for investment readiness calibrated to market growth and concentration dynamics.
-
Regulatory and certification checklist—practical steps to achieve ISCC compliance, engage with authorities and ensure claims are auditable across multiple jurisdictions.
Case actions for 2026 (recommended)
-
Secure short‑to‑mid term offtake: Negotiate staggered offtake volumes with certified suppliers to de‑risk supply while preserving optionality as product acceptance evolves.
-
Embed certification requirements: Make ISCC (or equivalent) certification a contractual condition for sustainability claims and corporate reporting.
-
Run targeted formulation pilots: Prioritize non‑critical rubber and plastics applications where rCB performance parity is closest, then scale into higher‑risk tire applications only after validated performance data and lifecycle assessments.
-
Design a blended sourcing strategy: Combine regional low‑cost producers with strategic local partners to balance price, logistics and regulatory exposure.
-
Allocate a small strategic M&A war chest: Use it to secure minority stakes in technology‑proven producers or recycling networks that provide privileged access to feedstock.
Where the uncertainty lies—and how the report helps
-
Feedstock price volatility and competition for scrap tires: Increased recycling demand can drive feedstock costs. Our forecast scenarios quantify impacts on margin and recommend hedging and vertical integration strategies.
-
Technical parity with virgin carbon black: Current purity gaps limit some tyre tread applications. The report includes an R&D prioritization guide and blending decision matrix to minimize performance tradeoffs.
-
Policy tailwinds and trade friction: Divergent regional treatments create both arbitrage and compliance complexity; our regulatory matrix maps actions by jurisdiction to keep 2026 strategies compliant and efficient.
Final thoughts — the 2026 strategic inflection
Recovered carbon black is no longer a speculative sustainability experiment; it is a maturing industrial commodity with clear pathways to scale and meaningful implications for cost structures, product positioning and sustainability claims. The macro indicators point to rapid expansion through the remainder of the decade, but the commercial story will be written in 2026 by firms that move from assessment to disciplined operational execution—locking in certified supply, proving formulations in prioritized applications, and using structured procurement and investment frameworks to capture upside while managing purity and regulatory constraints.
Next step
This briefing is a curated preview designed to help senior leaders frame 2026 choices. Our full PW Consulting Recovered Carbon Black Rcb Market report contains the granular forecasting, supplier performance benchmarking, contractual templates and scenario models you will need to operationalize the recommendations above. Visit the report page to access the complete dataset, downloadable toolkits and supplier matrices that support immediate execution.
For detailed analysis of this topic, please visit the official page: Recovered Carbon Black Rcb Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


