



PW Consulting: High Purity Tungsten Market to 2032 — USD 1,001.64M, 6.5% CAGR

High Purity Tungsten Market — Strategic Briefing for 2026 Decision‑Makers
PW Consulting’s latest High Purity Tungsten Market study is designed as a decision‑grade intelligence package for corporate strategists, procurement leaders, and investors gearing up for the 2026 planning cycle. Built on a full historical series (2020–2025) and a forward forecast (2026–2032), the analysis combines a robust demand model, supply‑side mapping, and scenario stress‑tests to translate commodity dynamics into executable business options.
High Purity Tungsten Market
Why this study matters in 2026
-
Strategic inflection. The high purity tungsten market is transitioning from a niche industrial material into a strategic raw material for advanced electronics, semiconductor sputtering targets, and select aerospace/medical applications. That transition creates both volatility and structurally higher long‑term value—requiring distinct strategic choices for suppliers, consumers, and financiers.
High Purity Tungsten Market -
Policy and trade shocks. Recent policy moves—tariff increases and export controls—have altered supply economics and rendered previously robust sourcing strategies fragile. Procurement teams and corporate strategists must reconcile short‑term price volatility with longer term supply security objectives.
High Purity Tungsten Market -
Capital allocation decisions. With the market on a growth trajectory and increasing interest in upstream project development, 2026 is a pivotal year to decide on greenfield investments, offtake agreements, and M&A plays that will determine access to high‑purity feedstocks for the decade ahead.
Market snapshot — the macro view
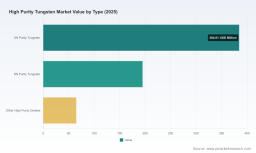
Our macro model tracks the high purity tungsten market from roughly USD 462 million in 2020 to approximately USD 645 million in 2025, driven by stronger electronics demand and constrained feedstock flows. We project the market to expand at a compound annual growth rate (CAGR) of about 6.5% over the 2026–2032 forecast window, reaching roughly USD 1.0 billion by 2032 under the baseline scenario. These headline numbers mask significant structural shifts beneath the surface—changes in buyer concentration, grade mix, feedstock sourcing, and the role of geopolitical policy—that materially affect margin pools across the value chain.
Key market dynamics reshaping strategy
-
Feedstock tightness and price volatility. Ammonium paratungstate (APT), the primary intermediate for high purity production, experienced acute price moves driven by supply controls and trade measures—creating immediate margin pressure for processors and downstream buyers. Rotterdam and domestic price indicators tracked sharp increases through 2025–2026, underscoring the need for explicit raw‑material risk management in contracts and forecasting.
-
Regulatory and trade interventions. Major jurisdictional actions—most notably increased tariffs on imports from China in the U.S., and Chinese export controls on selected tungsten intermediates—have elevated the cost basis for cross‑border flows and accelerated regionalization of processing capacity. These interventions change commercial calculus for sourcing and capital projects and require continuous monitoring in supplier selection frameworks.
-
Supply response and new project pipeline. The supply side is responding: new mining production and advanced project developments in multiple jurisdictions, together with targeted public funding for domestic capacity in several markets, will change availability over the medium term. However, upstream lead times and metallurgy constraints mean that supply elasticity will remain limited in the near term.
-
Consolidation and concentration. The market exhibits moderate concentration: incumbent manufacturers and integrated material houses retain dominant shares of high‑purity manufacturing capabilities. This concentration supports pricing discipline but also raises counterparty risk for large raw‑material consumers.
What the PW Consulting report delivers (practical, operational modules)
-
Interactive demand model — build your own scenarios by application, purity grade, and procurement horizon (baseline, upside, downside).
-
Supply chain map — from concentrate to ultra‑high purity metal and finished components, identifying single points of failure and alternative routing options.
-
Price and feedstock sensitivity matrices — quantify margin exposure across realistic APT price trajectories and tariff permutations.
-
Regulatory watchlist and export‑control matrix — jurisdictional rules and likely policy pathways that impact trade flows and permitting timelines.
-
Company profiles and capability heatmap — strengths, technological differentiators, capacity footprints, and counterparty risk indicators (detailed supplier dossiers included for leading market participants).
-
Project evaluation templates — capex/opex heuristics, payback thresholds, and blended cost of supply models tailored for greenfield and brownfield investments.
-
Commercial playbooks — procurement levers, hedging blueprints, offtake negotiation frameworks, and M&A screening criteria focused on 2026 execution.
Competitive landscape — strategic reads on core participants
-
Elmet Technologies LLC (Lewiston, ME, USA) — Fully integrated U.S. manufacturer with reduction‑based powder making and downstream mill products. Elmet’s integration gives it defensible margin control and fast response times to North American demand surges. Strategic implication: attractive partner for short‑term offtake and for firms seeking to shorten supply lines, but scale limitations may constrain large program commitments without capacity expansion.
-
Buffalo Tungsten Inc. (Depew, NY, USA) — Independent specialist focused on ultra‑high purity powders and tungsten carbide powders. Buffalo’s product purity and niche customer relationships make it a preferred supplier for high‑value electronics work; however, independents remain exposed to feedstock cost shocks and freight disruptions.
-
Global Tungsten & Powders (GTP) — Plansee Group affiliate — A major integrated materials house with broad downstream capabilities, positioned to capture value across the chain (powder, chemicals, components). GTP’s global footprint and downstream product mix reduce single‑point exposure, making it a logical counterparty for OEMs seeking supply continuity and technical partnerships.
-
H.C. Starck / Plansee Group / A.L.M.T. / JX Nippon / Xiamen / Chongyi Zhangyuan / Masan High‑Tech — A mix of European, Japanese, Chinese and Southeast Asian manufacturers covering a range of technological capabilities—from specialty powders and wires to large‑scale powder production. The competitive set presents a spectrum of tradeoffs between cost, quality, speed, and geopolitical exposure. Strategic buyers must weigh price against security and qualification lead times for critical applications.
Recent developments that change the game
-
Project momentum in exploration and development has picked up—new staking and land expansions in North America and project approvals in Europe create optionality for future feedstock supply lines.
-
Trade and regulatory measures enacted since late 2024 and into 2025 have meaningfully tightened cross‑border flows of key intermediates and prompted buyers to re‑evaluate sourcing and inventory policies.
-
Public funding and strategic programs in mine jurisdictions are reducing some sovereign risk, but not eliminating short‑term price spikes driven by immediate constraints in processing and transport.
Actionable plays for corporate leaders in 2026
-
Adopt a two‑tier procurement strategy: secure a core of qualified, long‑term suppliers (to cover critical needs) and maintain a flexible margin of opportunistic purchasing to exploit spot dislocations.
-
Hedge selectively using contract structures that share raw‑material risk—indexation clauses, blended pricing corridors, and multi‑year offtake with escape provisions for extreme policy moves.
-
Prioritize qualification pipelines: accelerate qualification of alternative suppliers and regional sources (even at a premium) for mission‑critical components to shorten response time in supply shocks.
-
Assess vertical integration selectively: for manufacturers with scale, upstream processing or strategic equity stakes in concentrate projects can be accretive—model conservatively and stress‑test on delayed ramp scenarios.
-
Target bolt‑on M&A where it reduces counterparty risk or speeds time‑to‑market for higher‑purity grades; for investors, look for platform assets with repeatable processing technology and locked‑in offtake.
-
Invest in materials R&D that substitutes high‑cost grades or improves recovery—small improvements in yield or downstream processing can materially change unit economics over multi‑year production runs.
Why PW Consulting’s study is different
Beyond conventional market sizing, our study ties macro dynamics to micro decisions through an integrated demand/supply/risk model and an actionable toolkit for 2026. We combine granular supplier intelligence, a dynamic pricing sensitivity engine, and regulatory scenario mapping so that commercial, procurement, and corporate development teams can run "what‑if" strategies and produce investment‑grade outputs suitable for Board review.
Note: this briefing emphasizes strategic takeaways and constrained disclosure by design. Core subsegment tables, granular regional shares, and application‑level revenue splits are intentionally withheld from this public overview to preserve the report’s commercial integrity. Full access to the segmentation, supplier dossiers, and interactive models is available through the PW Consulting report portal.
Immediate next steps for readers
-
Procurement & Supply Chain leads — request the report’s procurement playbook and the supplier risk heatmap to incorporate into 2026 sourcing cycles.
-
Corporate Strategy & M&A teams — schedule a scenario workshop to test acquisition and investment hypotheses against our baseline and downside cases.
-
Investors & Project Developers — use the project evaluation templates and offtake framework to fast‑screen opportunities in the new supply pipeline.
For organizations that need to convert market signals into executable plans in 2026, this study provides the models, vendor intelligence, and tactical playbooks to act with conviction. Access to the full study, including the underlying segmentation tables, supplier dossiers, and the interactive forecast model, is available via PW Consulting’s report portal.
For detailed analysis of this topic, please visit the official page: High Purity Tungsten Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


