



PW Consulting: Selective Soldering Market to Hit USD 922.6M by 2032 at 6.8% CAGR

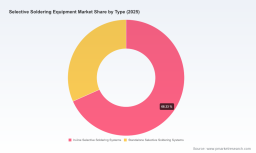
Selective Soldering Equipment Market: Strategic Intelligence for Executive Decisions in 2026
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present an incisive preview of our latest Selective Soldering Equipment Market study — a practical briefing designed to inform capital allocation, product strategy, supply-chain prioritization, and M&A decision-making throughout 2026. This article emphasizes the strategic value of the research while deliberately withholding the granular sub-segment figures that reside in the full report to preserve the incentive to engage with our complete analysis.
Selective Soldering Equipment Market
Executive snapshot: why this matters to 2026 decision-makers
Selective soldering is no longer a niche workshop capability; it is a foundational technology for high-reliability, mixed-technology PCB assembly across automotive electrification, advanced industrial controls, telecom infrastructure and increasingly demanding consumer electronics. Our base-year view (2025) positions the global selective soldering equipment market at approximately USD 582.1 Million, with a projected 2026 market step-up to roughly USD 663.2 Million and a compound annual growth rate (CAGR) of 6.8% through our 2026–2032 forecast window. Those topline numbers quantify a recovery and acceleration trajectory that corporate leaders must internalize when planning CAPEX cycles, equipment refresh programs, and factory modernization roadmaps in 2026.
Selective Soldering Equipment Market
Market trajectory and the mechanics behind the growth
-
Recovery and momentum: The market exhibited pandemic-era volatility during 2020–2022, followed by stabilization and renewed investment through 2023–2025. The forecast to 2032 anticipates steady expansion driven by miniaturization, lead-free requirements, and rising complexity in mixed-technology assemblies.
Selective Soldering Equipment Market -
Consolidation and concentration: Market concentration is non-trivial: the leading three suppliers control close to half the market, while the top five approach two-thirds of market share. This balance of scale and specialized engineering capacity shapes pricing, service coverage and innovation cycles for buyers and investors.
-
Structural demand drivers: Adoption is being propelled by three structural shifts — miniaturized components that require focused heat control, regulatory and lead-free soldering mandates, and the growth of electric vehicle (EV) and ADAS electronics which demand selective accuracy and low-void solder joints.
Why 2026 is a pivot year for equipment and operations strategy
For OEMs, EMS providers, and equipment vendors, 2026 represents a decision inflection: deferment of equipment investment risks falling behind in throughput and process yield versus competitors; premature replacement risks under-utilized assets and eroded returns. Our study frames that tradeoff through three executable decision lenses:
-
Capital allocation: Use forward-looking demand curves and scenario stress-tests to time major inline selective soldering investments. Short-cycle production needs can still be met with modular or standalone platforms, while strategic high-volume lines justify integrated, multi-station in-line systems.
-
Operational efficiency: Selective soldering’s cost profile (notably lower flux and solder consumption and reduced nitrogen use) can materially alter TCO compared with conventional wave soldering — a critical lever when margins are under pressure.
-
Quality & compliance: The technology supports compliance with IPC-level industry standards and can achieve void and reliability targets necessary for aerospace, medical and automotive electronics, making selective soldering a risk-management investment as much as a throughput play.
Practical, actionable content inside the full report
Our Selective Soldering Equipment Market study was assembled specifically for operational leaders and strategic investors. Key pragmatic deliverables include:
-
Decision-ready financial models — TCO calculators that contrast CAPEX, OPEX, consumables, and service across equipment classes and production profiles.
-
Vendor scorecards — engineering, aftermarket support, global service footprint, and retrofit compatibility metrics to accelerate shortlisting and procurement.
-
Technology roadmaps — comparative analysis of inline multi-station architectures versus standalone/batch systems, including modular upgrade paths and automation integration considerations.
-
Scenario playbooks — three to five demand and supply scenarios with sensitivity analysis for raw-material price swings, labor constraints, and regulatory tightening.
-
M&A and partnership lenses — playbooks for strategic and financial buyers highlighting integration risks, service-synergy opportunities, and quickly accretive bolt-ons.
-
Service & spares optimization — inventory policies and aftermarket strategies to reduce downtime and guarantee process repeatability across multi-site rollouts.
Competitive landscape: who matters and why
The competitive field blends long-established OEMs with focused niche specialists. Our study contains detailed vendor profiles, but the strategic highlights follow.
-
Kurtz Ersa GmbH (Germany) — A market leader with modular VERSAFLOW and ECOSELECT platforms. Strengths: broad platform range from entry-level to high-volume, electromagnetic pump technology and multi-nozzle adaptability that supports throughput scaling.
-
Nordson SELECT (United States) — Offers a complete spectrum (standalone, inline, multi-station) with a deep global service network. Competitive edge: turnkey solutions and aftermarket coverage for high-volume electronics manufacturers.
-
SEHO Systems GmbH (Germany) — Strong in integrated fluxing, preheating and soldering zones aimed at productivity and yield. Notable for platform-level engineering to support higher first-pass yields.
-
Pillarhouse International Ltd (UK) — Pioneer of selective soldering with a high-patent count; competitive in high-engineering-standard, reliability-focused segments.
-
JUKI Corporation & Apollo Seiko (Japan) — Provide batch and inline platforms, respectively, with particular relevance to through-hole legacy transitions and dual-pot innovations for precision soldering.
-
US and regional specialists (DDM Novastar, RPS Automation, TM Soldering Solutions, Hentec, VennTek-SASinno, INERTEC) — Offer cost-effective, niche and retrofit solutions that improve access to selective soldering across small and medium-sized EMS providers.
Recent vendor movements underscore competitive dynamics: multiple product launches and trade show showcases in late 2025 and early 2026 signal accelerating feature competition and an emphasis on throughput and modularity. Our full profiles catalog disclosed product launches, service expansions and regional go-to-market tactics in granular detail.
Key operational and regulatory context
-
Raw materials: The solder flux market — a critical consumable for selective processes — was estimated at roughly USD 3.12 billion in 2025 and is itself a growth market. Understanding flux segmentation and supply-chain concentration is essential for reliable OEE planning.
-
Process efficiency: Empirical process studies and vendor claims point to substantial reductions in solder usage and nitrogen consumption for selective soldering versus wave approaches. These efficiencies directly influence operating margins and environmental footprint.
-
Standards & reliability: Selective soldering is a practical enabler of compliance with IPC-level requirements and lower void percentages demanded by aerospace, medical and automotive assemblies — translating into lower warranty risk and higher product reliability.
Risk factors and scenario planning
While demand fundamentals remain constructive, 2026 strategies must include contingency playbooks addressing:
-
Raw-material volatility and supply chain disruptions for fluxes and specialty alloys.
-
Geopolitical shifts affecting capital-equipment sourcing and service footprints.
-
Rapid technology substitution or unexpected shifts in production architectures — for instance, a faster-than-anticipated move to fully automated inline cells that renders some legacy standalone investments sub-optimal.
Actionable strategic recommendations for 2026
-
For OEMs and Tier-1 manufacturers: Prioritize selective soldering investments on product lines where reliability premiums or regulatory compliance deliver quantifiable margin uplift. Use staged adoption: start with pilot inline cells on critical SKUs before committing to full-line conversions.
-
For EMS providers: Build a flexible equipment portfolio that mixes compact standalone systems for short runs and modular inline stations for predictable, high-volume customers. Strengthen service contracts and spare-parts availability to turn uptime into a competitive differentiator.
-
For equipment vendors: Invest in service orchestration, remote diagnostics, and modular upgradeability. Product differentiation will hinge on throughput scaling, ease-of-retrofit, and lifecycle service economics.
-
For investors & M&A teams: Seek targets that offer either niche technological IP (e.g., unique pump or nozzle technologies) or service-reach that can be rapidly integrated into a global aftermarket network; focus on assets that improve gross margin predictability in rolling 12–24 month horizons.
What the full PW Consulting report unlocks
The complete study contains the operational models, supplier scorecards, and scenario analytics required to convert these strategic signals into executable plans. To respect proprietary value and maintain the “selective” nature of this preview, we have withheld the granular regional and application splits from this article — those tables and the interactive modeling tools are available within the full report package and on our data portal.
Next steps
If you are responsible for CAPEX planning, factory modernization, procurement of selective soldering systems, or evaluating investment targets in 2026, the PW Consulting Selective Soldering Equipment Market study provides the operational blueprints and financial models you need. Contact our team or visit the report landing page to obtain the full dataset, vendor scorecards, and the TCO calculator.
For detailed analysis of this topic, please visit the official page: Selective Soldering Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


