



PW Consulting: Water Recycling & Reuse Market to Reach USD 47,349.62M by 2032 (11.25% CAGR)

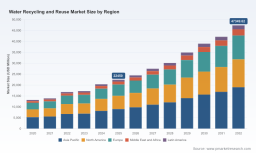
Water Recycling and Reuse Market — 2026 Strategic Preview
As PW Consulting’s Senior Strategic Advisor and Chief Industry Analyst, I present a focused, decision-grade preview of our full Water Recycling and Reuse Market study — designed to fast-track C-suite and corporate strategy teams in 2026. This piece demonstrates the depth of our analysis and the concrete strategic implications emerging today, while preserving proprietary segment-level intelligence to encourage direct access to the full report and interactive tools.
Water Recycling And Reuse Market
Market Snapshot: Scale, Trajectory, and the Investment Imperative
The global water recycling and reuse market has transitioned from a niche sustainability play to a major infrastructure and industrial investment theme. Our base-year assessment shows the market reached approximately USD 22.45 billion in 2025. Under a central-case projection, the market expands at a compound annual growth rate (CAGR) of 11.25% across our 2026–2032 forecast horizon, nearly doubling to an estimated USD 47.35 billion by 2032. This trajectory reflects the combined effect of policy acceleration, industrial demand for closed-loop water systems, urban-scale recycling programs, and growing commercial viability of advanced treatment technologies.
Water Recycling And Reuse Market
Strategic Drivers That Will Shape Corporate Decisions in 2026
- Regulatory acceleration and mandate-driven demand. New policy frameworks and standards are proliferating. Notable examples include the US EPA’s Water Reuse Action Plan 2.0, which explicitly targets industry verticals such as data centers and energy; state-level mandates increasing reuse of produced water in oil & gas; and adoption of testing/qualification standards for onsite reuse systems. These create predictable demand corridors for firms able to meet compliance thresholds and demonstrate validated treatment performance.
- Large-scale municipal and industrial projects as market pull. Major programmes — from municipal purified-recycled-water initiatives to industrial reuse facilities built under long-term O&M contracts — are crystallizing the market into investable, bankable assets. Project milestones in 2025–2026 have converted theoretical demand into executable pipelines.
- Technology maturation and cost dynamics. Membrane-based systems, modular MBRs, and multi-barrier tertiary treatment are now proven at scale. Capital-intensity remains a consideration: industry benchmarks continue to quote capital cost ranges for membrane bioreactor systems and advanced tertiary treatment in per-gallon terms, which materially affect project-level IRR and procurement choice between centralized and decentralized architectures.
- Commercial models shifting to services and outcomes. The value pool is moving from equipment sales toward integrated offerings — performance guarantees, long-term service contracts, and digital-enabled lifecycle optimization. Acquirers and platform investors are seeking recurring-revenue streams tied to O&M and analytics.
- Fragmented supplier base with rising consolidation pressure. Market concentration metrics show meaningful room for consolidation: leading vendors account for a material but not dominant share, leaving strategic space for M&A, roll-up plays, and strategic partnerships between technology specialists and global operators.
What the PW Consulting Report Delivers — Actionable, Not Academic
Our full report is structured to convert market intelligence into executable initiatives. Highlights include:
Water Recycling And Reuse Market
- Proprietary market sizing and three scenario-based forecasts (conservative, central, disruption) with sensitivity analysis to policy and capital-cost variables.
- Demand-driver mapping by use-case (municipal programs, industrial reuse, produced water, onsite greywater), translating regulatory signals and capital cycles into addressable opportunity curves.
- Technology assessment framework that ranks treatment pathways by total cost of ownership, regulatory fit, footprint, and time-to-deploy — with deployment playbooks for centralized vs. decentralized models.
- Supplier and competitive intelligence, including strategic profiles and capability heatmaps for global and regional challengers. (Profiles of core companies included in the public synopsis; full comparative matrices are in the report.)
- Investment and procurement toolkits: project-level financial models, contractor RFP templates, O&M contracting options, risk allocation matrices, and a regulatory tracker for major markets.
- Ten detailed case studies that distill lessons from recent project wins, large-scale municipal programs, and industrial ZLD implementations — each with implementation timelines and supplier ecosystem maps.
Competitive Landscape — Who Matters and Why
The market is competitive and strategically diverse: global operators with integrated water-management capabilities are competing alongside specialized membrane and modular-system vendors. Key players we profile in depth include Veolia, Xylem Inc., SUEZ Water Technologies & Solutions, Ecolab (Nalco Water), DuPont Water Solutions, Pentair, Aquatech, Kubota, ALFA LAVAL, Hitachi, Siemens, Fluence, Kurita, Culligan, and Consolidated Water. Our report evaluates each firm across three strategic vectors: technology stack and IP, go-to-market model (project EPC vs. recurring O&M vs. product sales), and corporate capability to scale across geographies and verticals.
- Veolia continues to leverage its project-development and long-term O&M expertise to secure consortium-scale industrial reuse contracts, exemplified by large industrial plant agreements signed in 2025.
- Xylem’s platform expansion via acquisition is a defining move — combining fluid-handling, membranes, and analytics shifts the value proposition toward integrated lifecycle services and data-driven performance guarantees.
- SUEZ and Ecolab remain strong in modular solutions and customized industrial programs; their strength lies in multi-barrier approaches and chemical/biological process integration.
- Specialists — from membrane manufacturers to ZLD system integrators and modular decentralized providers — are the most likely acquisition targets or partners for larger engineering and services firms seeking rapid capability scaling.
Recent, tangible developments underscore these dynamics: a major acquisition completed in early 2026 that enlarged a membranes-and-analytics platform; milestone project agreements and contract awards for large-scale industrial and municipal plants in 2025–2026; and municipal programs advancing environmental approvals — all of which convert stated strategies into near-term addressable revenue.
Strategic Playbook for Executives in 2026
- Prioritize use cases with policy-backed demand. Immediate priorities should be projects and contracts anchored to regulatory mandates or long-term municipal programmes. These are the highest-confidence revenue streams for capex deployment and investor pitches.
- Design offerings around lifecycle economics, not just capex. Given the capital intensity of advanced treatment, winning in 2026 requires service-centric pricing, performance guarantees, and ability to reduce total cost of ownership through predictive maintenance and process optimization.
- Pursue targeted M&A and partnerships. Buyers should acquire modular-treatment specialists, membrane IP, or analytics providers to create bundled solutions. Sellers should seek strategic buyers that can deliver large-scale O&M contracts to convert product revenues into recurring streams.
- Use pilots to derisk and prove commercial models. Structure limited pilots with clear KPIs and scale-up triggers tied to financing milestones; consider shared-risk, incentive-aligned contracts to accelerate customer adoption.
- Embed digital to monetize performance data. Invest in remote monitoring and analytics to enable outcome-based contracts and to protect margins as hardware becomes commoditized.
- Monitor cost benchmarks and procurement timing. Capex-per-unit benchmarks for membrane bioreactors and tertiary treatment remain central inputs to bid strategy and ROI calculations — incorporate these ranges into tender pricing and lifecycle models.
- Engage regulators early and shape standards. Proactive engagement on standards and testing protocols will accelerate approvals and give first-mover advantages in nascent reuse categories (e.g., industrial reuse for data centers, produced water mandates).
Why PW Consulting’s Report is Valuable for 2026 Decisions
This study is not an academic compendium; it is a hands-on, transaction-oriented playbook. It gives corporate strategists and investment committees the forecasts, vendor scorecards, and risk-adjusted financial models needed to: prioritize capital allocation, design deals that convert projects into annuity-like income, position organizations for consolidation waves, and operationalize regulatory change. We surface where policy and project execution intersect to create bankable opportunities — and where capability gaps will determine winners and losers.
For decision-makers preparing budgets, negotiating partnerships, or evaluating M&A opportunities in 2026, the choice is twofold: rely on high-level public narratives — or equip your team with the granular scenarios, commercial templates, and supplier assessments that materially improve project selection, pricing discipline, and negotiation outcomes. Our report delivers the latter.
Next Steps
Access to the full PW Consulting Water Recycling and Reuse Market report provides the detailed, segment-level models, vendor matrices, and interactive ROI tools referenced above. For executives ready to convert the 2026 market dynamics into a clear growth agenda — whether through organic investment, partnership, or acquisition — the report is the operational map and the decision support system you need.
For detailed analysis of this topic, please visit the official page: Water Recycling And Reuse Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


