



PW Consulting: MP SoC Market to Hit $363.16B by 2032 at 9.25% CAGR

Mp System On A Chip (SoC) Market — Strategic Outlook for 2026 Decision‑Makers
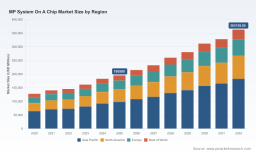
As companies recalibrate product roadmaps, capital allocation, and supply‑chain strategies for 2026, the Mp System On A Chip (SoC) market is a linchpin that will determine competitive advantage across consumer electronics, telecommunications, automotive and industrial systems. PW Consulting’s latest market study synthesizes seven years of historical data and a seven‑year forward forecast to give executives a precise, actionable view of where investment and strategic effort will produce the highest returns. The market has expanded materially in recent years — rising from approximately USD 128,110 million in 2020 to roughly USD 195,500 million in 2025 — and our base‑case projection places the market above USD 215,000 million in 2026 with a compound annual growth rate of 9.25% through 2032, reaching an expected USD 363,159 million at the end of the forecast window. These headline dynamics create both opportunity and complexity for strategic decision‑makers in 2026.
Mp System On A Chip Market
Why this study matters for 2026 decisions
-
Timing of technology inflection points: 2026 is the first year many leading foundries and designers will roll out 2nm‑class products at scale. This will reshape performance, power and integration economics for flagship SoCs and high‑end edge devices.
Mp System On A Chip Market -
Strategic policy tailwinds and headwinds: public funding programs and export control regimes are simultaneously accelerating domestic capacity in some markets while constraining cross‑border technology flows. Firms must navigate incentives, compliance risk and the new economics of localized supply chains.
Mp System On A Chip Market -
Consolidation pressure vs. fragmentation opportunity: the market exhibits moderate concentration among global leaders, but technology specialization (imaging, automotive-grade safety, mixed‑signal integration) leaves room for targeted entrants and M&A plays.
-
Packaging and integration shifts: advanced packaging and standardized chiplet interconnects are changing the value chain — companies that adopt heterogeneous integration early will shorten time‑to‑market for differentiated performance.
What the report delivers — practical, decision‑grade insight
-
Robust market sizing and scenario models: transparent methodology that reconciles historical revenues (2020–2025) with three forecast scenarios (base, upside, downside) across 2026–2032, enabling stress‑tested volume and revenue planning.
-
Go‑to‑market playbooks: prioritized GTM options for semiconductor vendors, OEMs and system integrators by technology stack and buyer persona, including product positioning, channel choices and pricing levers.
-
Supply‑chain and manufacturing roadmaps: evaluation of node transition timelines, advanced packaging adoption curves, and high‑margin assembly strategies, with a focus on risk mitigation under export control regimes.
-
Technology and IP strategy: assessment of chiplet adoption, UCIe standardization impacts, and how to structure partnerships with foundries and packaging specialists to capture performance cost improvements.
-
Commercial due diligence toolkit: vendor scorecards, M&A screening criteria, and integration checklists to accelerate target selection and post‑acquisition value capture.
-
Regulatory and compliance matrix: practical guidance for export control exposure analysis, navigating incentives (including national chip funding programs), and building a defensible compliance posture.
-
Risk and contingency planning: scenario‑based operational playbooks for yield shocks, geo‑political supply interruptions and sudden demand shifts in automotive or telecommunications segments.
Competitive landscape — what the leaders are doing and why it matters
The competitive field spans vertically integrated platform owners, fabless specialists, diversified semiconductor giants and niche systems vendors. The market’s top three players collectively command a meaningful portion of aggregate revenue, while the top five account for a dominant slice of industry revenue — a structure that supports both scale advantages and differentiated niche strategies. Key strategic positioning to watch in 2026:
-
Qualcomm Technologies, Inc.: Continues to leverage modem and connectivity IP alongside high‑performance application processors to defend its mobile and expanding automotive footprint. Its integrated approach to connectivity and heterogeneous compute remains a commercial advantage for OEM partnerships.
-
Apple Inc.: Vertical integration of SoC design and system architecture drives substantial per‑device differentiation. Its control of silicon and software stacks makes it a benchmark for performance per watt and user experience optimization.
-
MediaTek Inc.: A proven operator in cost‑performance tradeoffs for mainstream mobile and consumer segments; its recent tape‑out on advanced process technology signals an intent to close the gap on flagship performance while preserving aggressive cost structures for high‑volume markets.
-
Samsung Electronics: Dual role as designer and foundry provides flexibility in aligning SoC design to manufacturing advances and memory integration including HBM, valuable for both mobile and high‑performance segments.
-
AMD and Intel: Both are converting traditional CPU franchises into broader SoC strategies for data center, edge and PC markets, with implications for platform consolidation and software ecosystem lock‑in.
-
NVIDIA: Focused on GPU‑centric SoCs for automotive and edge AI; its strengths in deep learning acceleration make it a go‑to for workloads that prioritize parallel compute and model inference at the edge.
-
Broadcom, NXP, STMicroelectronics, Texas Instruments: Each occupies differentiated niches in networking, automotive, industrial and analog/mixed‑signal SoCs. Their breadth of product portfolios delivers resilience against single‑market downturns.
-
OMNIVISION and Socionext: Examples of specialized IP and systems expertise — from imaging sensor SoCs to custom automotive solutions — that enable targeted wins where domain knowledge and integration matter most.
Industry dynamics shaping strategic choices in 2026
-
Node adoption and packaging: The industry’s march toward 2nm‑class process nodes and wider deployment of advanced packaging (including large‑reticle interposers supporting HBM) will change the performance/cost frontier. Decision‑makers should assess where node upgrades materially improve product value versus where multi‑die integration yields better TCO.
-
Standardization and modularization: The emergence of chiplet standards is lowering barriers to heterogeneous integration but increasing the importance of IP orchestration and ecosystem partnerships.
-
Policy and supply‑chain realignment: Export control regimes and national incentives are reconfiguring supply footprints. Firms must develop localized manufacturing options or secure strategic supply agreements to avoid market access constraints.
-
Domain‑specific acceleration: Automotive L2–L4, edge AI, and telecommunications (5G/6G evolution) are driving differentiated SoC requirements — from functional safety certification to determinism and long‑term availability commitments.
Strategic imperatives for 2026 — recommended action checklist
-
Prioritize investment where node and packaging advances unlock clear product differentiation; defer blanket node upgrades where chiplet or packaging alternatives deliver similar performance at lower capital spend.
-
Harden regulatory playbooks: map export control exposure to product roadmaps, and align R&D footprints to incentive programs and compliant manufacturing partners.
-
Forge ecosystem partnerships: early adoption of chiplet standards and joint engineering agreements with foundries and packaging houses will accelerate time‑to‑market for heterogeneous SoCs.
-
De‑risk supply: diversify high‑risk suppliers, secure long‑lead materials, and design for multi‑sourcing of critical IP blocks where possible.
-
Targeted M&A: prioritize tuck‑ins for missing capabilities (imaging ISPs, automotive safety IP, mixed‑signal expertise) over large horizontal purchases that dilute focus.
-
Commercial readiness: establish price‑performance tiers aligned to buyer personas and produce modular product families that simplify platform migration for OEM customers.
How PW Consulting’s study helps operationalize these imperatives
This research is designed as a decision‑support engine: detailed financial models, LCOE style cost curves for node and packaging options, vendor scorecards, and stepwise GTM templates are included so that product and corporate strategy teams can convert insight into executable plans within quarters, not years. Importantly, this introduction intentionally omits granular regional and application splits and the vendor‑level financial tables — those sensitive, high‑value datasets are available in the full report and the accompanying interactive dashboard for subscribers.
For executives preparing 2026 budgets, negotiating supplier agreements, or screening M&A targets, the combination of a 9.25% CAGR base case, our scenario stress tests, and the technology‑policy overlay provided in the full study will materially improve the quality and defensibility of strategic choices.
Next steps
-
Download the full report and interactive models to access regional and application breakouts, vendor financials, and a prioritized list of acquisition targets and partnership candidates.
-
Engage PW Consulting for a tailored workshop: scenario planning, capex optimization, and regulatory risk quantification specific to your product portfolio.
PW Consulting’s Mp System On A Chip Market study is structured to convert complexity into executable strategy for 2026 — providing a roadmap that balances technological ambition, regulatory realism and commercial discipline. For access to the granular intelligence and tools that support concrete investment and partnership decisions, please consult the full report.
For detailed analysis of this topic, please visit the official page: Mp System On A Chip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


