



PW Consulting: Gas Humidity Sensors Market to Reach $2.43B by 2032 at 7.51% CAGR

Gas Humidity Sensors Market 2026 — Strategic Preview for Executive Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Head Industry Analyst, I present an executive preview of our newest market study on Gas Humidity Sensors. This briefing distills the research’s strategic value for corporate leaders planning actions in 2026, highlights the market trajectory, and identifies the operational levers that will determine winners over the next planning cycle. The goal: demonstrate the depth of our analysis while reserving the granular segment-level datapoints for the full report.
Gas Humidity Sensors Market
Market at a Glance — The Macro Frame
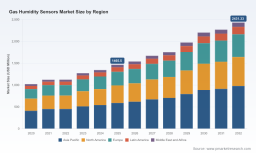
The gas humidity sensors market is on a multi-year expansion path. After a steady recovery across the early 2020s, the market base in our 2025 reference year stands near the mid‑single‑billion dollar mark (USD, revenue unit: Million). Under our central forecast — grounded in historical 2020–2025 performance and validated demand drivers — the market grows at a compound annual growth rate of approximately 7.51% through our 2026–2032 forecast horizon, with the 2032 market approaching roughly USD 2.43 billion. Market concentration is moderate: the top three firms account for about 32.4% of industry revenues, and the top five about 48.2%, indicating meaningful room for both scale-driven incumbents and specialized challengers.
Gas Humidity Sensors Market
Why This Matters for 2026 Strategic Planning
- Revenue predictability with tactical inflection points: The underlying CAGR provides a baseline for budget planning, but 2026 is characterized by discrete catalysts — product upgrades to meet safety standards, OEM design-wins in automotive sensing, and integrated multi-sensor modules for IoT — that can materially accelerate adoption in targeted verticals.
- Margin and procurement pressure: Supply-chain frictions remain a structural risk. Our research flags a notable increase in lead times for certain specialty electronic materials used in sensing modules; clients should expect procurement volatility unless they actively diversify suppliers or secure strategic inventory positions.
- Regulatory and safety-driven demand: Functional-safety certification requirements (e.g., ASIL-level readiness in automotive perception and LiDAR systems) are creating premium segments within the market where suppliers can command differentiation and pricing power.
What the Full Report Delivers — Actionable, Practically Oriented Content
This study is designed to be operationally prescriptive for executives and commercial teams. Key deliverables include:
Gas Humidity Sensors Market
- Forward-looking market sizing and scenario models (base, upside, downside) that you can plug directly into corporate planning tools. Models are parameterized for demand shocks, technology adoption, and regulatory shifts.
- Commercial playbooks for OEM engagement: prioritized verticals, value-proposition templates, and recommended channel strategies for capturing design wins in automotive, HVAC, industrial controls, and healthcare applications.
- Supply-chain resilience toolkit: supplier segmentation, dual-sourcing constructs, recommended inventory buffers, and cost-to-serve analysis to mitigate lead-time and rare-material exposure.
- Technology roadmap and R&D scorecards: comparative assessment of MEMS, digital sensor integration, and hybrid sensing approaches with time-to-market and IP risk indicators.
- M&A and partnership map: target archetypes for bolt-on acquisitions, JV models for co-development with automotive Tier 1s, and licensing opportunities with complementary semiconductor partners.
- Regulatory impact matrix: compliance timelines, certification cost estimates, and go/no-go decision thresholds for adopting ASIL and other region-specific standards.
Competitive Landscape — Who to Watch and Why
The industry mixes established sensor specialists, diversified industrial conglomerates, and semiconductor players. The competitive dynamics are nuanced: incumbents with high-precision heritage enjoy credibility in industrial and life-sciences segments, while semiconductor and electronics OEMs are leveraging integration and scale to acquire share in consumer and automotive adjacencies.
- Sensirion AG (Stäfa, Switzerland) — Maintains a technology leadership posture in high-precision digital humidity sensors and has recently highlighted safety-rated (ASIL) product developments and several automotive design-wins. Sensirion’s moves underscore the strategic premium available for suppliers that certify sensors for functional-safety environments.
- Honeywell International — Leverages its building technologies portfolio to sustain strong placements in HVAC and building automation, where integrated environmental sensing is a staple of retrofit and new-build projects.
- Texas Instruments — Brings semiconductor scale and power-efficiency credentials to digital humidity sensing, forcing a commercial playbook that bundles sensors with broader embedded-system solutions.
- Bosch Sensortec — Focused on MEMS-enabled combo sensors for consumer, wearable and IoT platforms; their strategy highlights the value of sensor fusion in constrained form factors.
- Amphenol, TE Connectivity, Vaisala, and E+E Elektronik — These firms represent a mix of robust industrial offerings, aerospace/defense channel access, and high-accuracy instrumentation, making them attractive partners for customers that require environmental-grade performance, long-term support, or sector-specific certifications.
Recent corporate actions accelerate these themes: product launches integrating humidity elements into broader environmental sensors, distribution agreements to reach aerospace and defense OEMs, and investor presentations calling out ASIL-rated sensor roadmaps are all signs the competitive bar is rising in 2025–2026.
Key Dynamics Shaping Competitive Advantage
- Integration wins: The market increasingly rewards vendors that can deliver combined temperature, humidity, pressure, and gas sensing in compact, calibrated modules suitable for IoT and automotive platforms.
- Safety and lifetime support: Designers and procurement teams in regulated industries now factor multi‑year support and safety certification into supplier selection. Products promising extended legacy support windows command strategic value.
- Supply chain friction: Geopolitical tariff actions and rare-material bottlenecks have increased procurement complexity; firms that secure upstream continuity via multi-region sourcing or backward integration will realize a pricing and reliability edge.
Strategic Imperatives for 2026 — What Executives Should Do Now
- Prioritize ASIL and certification roadmaps: If you supply or depend on sensors for automotive or safety-critical systems, accelerate certification planning. Early movers will capture design wins and create switching costs.
- Hedge supply risk with tactical inventory and dual-sourcing: Our supply-chain analysis quantifies lead-time volatility for critical components; firms should combine limited strategic stockpiles with validated alternate suppliers to avoid production stoppages.
- Adopt a product differentiation playbook: Invest in sensor fusion, calibration services, and edge-compute software to move from component supplier to systems partner — this expands TAM per device and deepens customer stickiness.
- Embed commercial flexibility: Offer tiered SLAs and long-term support contracts for enterprise and industrial customers, monetizing durability and lifetime assurance as a premium service.
- Explore focused inorganic moves: Use M&A selectively to acquire niche IP (e.g., MEMS or coating technologies), channel access, or certifications — faster than building in-house capability.
How to Use This Research in Your 2026 Planning Cycle
Integrate our forecast and scenario outputs into three core planning processes this quarter:
- Capital allocation: benchmark R&D and manufacturing investments against the market growth envelope and allocate to initiatives with >2x return under our central case.
- Commercial strategy: use the OEM engagement frameworks to prioritize design-win opportunities where certification and integration create outsized value.
- Risk management: apply the supply-chain toolkit to stress-test your sourcing and develop contingency playbooks tied to specific supplier disruption probabilities.
Final Observations — The Strategic Horizon
By 2026, the gas humidity sensor market will still be shaped by technological integration, regulatory pressure, and supply-chain realignment. Firms that combine certification readiness, supply resilience, and product differentiation will capture disproportionate value as the market scales toward the early-2030s. The market’s mid-term CAGR and concentration metrics suggest enough growth to reward both incumbent scale and focused innovators — but execution risk remains high for those that wait to react.
For executives preparing 2026 budgets and go-to-market plans, our full PW Consulting report provides the granular segmentation, regional demand maps, supplier scorecards, and downloadable financial models required to convert insight into action. This preview reveals the strategic contours; the complete study contains the detailed tables, heat maps, and scenario workbooks you will need to operationalize these recommendations.
Next Steps
- Contact PW Consulting to access the full report and downloadable scenario models.
- Request a tailored briefing with our sensor-market specialists to align our findings to your product roadmap, procurement strategy, or M&A pipeline.
PW Consulting’s Gas Humidity Sensors Market study is engineered to be a direct input into 2026 decision-making — pragmatic, defensible, and calibrated to the execution challenges that separate strategic plans from realized outcomes.
For detailed analysis of this topic, please visit the official page: Gas Humidity Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


