



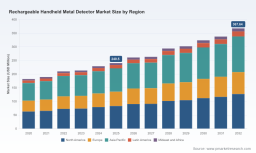
Rechargeable Handheld Metal Detector Market: $240.5M in 2025, 6.25% CAGR to $367.6M by 2032

Rechargeable Handheld Metal Detector Market — Strategic Briefing for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Head Industry Analyst, I present an executive preview of our latest market research on the Rechargeable Handheld Metal Detector industry. This briefing is designed for procurement leads, product strategists, investors, and security operators who must make high-stakes decisions in 2026. It synthesizes market-scale dynamics, competitive posture, technology inflection points, and practical actions — while intentionally withholding the granular segment tables and model-level forecasts available in the full report to preserve its tactical value.
Rechargeable Handheld Metal Detector Market
Market at a Glance: Direction and Scale
- Market scale: By the end of the report base year, the global rechargeable handheld metal detector market reached a substantive size measured in the hundreds of millions (USD, revenue units used). The industry is on a multi-year expansion path driven by heightened public security priorities and renewed capital investments in screening infrastructure.
- Growth trajectory: PW Consulting’s forecast horizon points to mid-single digit compound annual growth. The market is expected to grow at a steady pace through the 2026–2032 window, reflecting recurring replacement cycles, technology refreshes, and expanded adoption across non-traditional venues.
- Concentration: Competitive concentration is meaningful but not prohibitive. A cluster of established manufacturers controls a significant portion of global revenues, leaving room for focused challengers and regional specialists to capture niche opportunities.
Why 2026 Is a Strategic Inflection Point
- Certification convergence: With updated NIJ draft standards and increased public-sector procurement scrutiny, 2026 is primed for a certification-driven wave of purchases and device retirements. Vendors who can demonstrate compliance early will secure preferred-bidder status in major tenders.
- Battery and charging standards: Lithium-ion energy packs and USB-C charging are becoming baseline expectations. Product lifecycles will be increasingly judged on operational hours per charge, charging convenience, and maintenance cost — not just raw sensitivity.
- Commoditization risk vs. value capture: Hardware specification is converging (sensitivity, weight, IP rating). Differentiation will shift to lifecycle services, software-enabled diagnostics, ergonomic design, and bundled commercial models (warranty, replacement programs, training).
Key Market Dynamics
- Demand diversification: Traditional buyers — airports, correctional facilities, and government buildings — remain core. However, growth in events, education, and certain industrial segments is broadening the end-market footprint and changing procurement cycles.
- Technology trajectory: Multifrequency sensing, waterproofing for harsh environments, and vibration-based feedback are now table stakes in mid to high tiers. Higher-end models increasingly tout NIJ-standard compliance and extended run-times (some exceeding 100 hours), which influence total cost of ownership assessments.
- Supply-side pressures: Lithium-ion battery availability and certification timelines for new standards represent the primary near-term supply risks. Manufacturers operating single-source battery lines or relying on long cross-border supply chains are exposed to lead-time and price volatility.
- Regulatory influence: New and draft standards (notably NIJ 0602 updates) are reshaping procurement specs. Buyers are favoring NIJ-compliant units and field-calibration minimization features to reduce maintenance overhead.
Competitive Landscape: What the Leaders and Challengers Are Doing
The market’s competitive fabric blends legacy OEMs with agile regional players. Key archetypes and recent moves illustrate strategic positioning:
Rechargeable Handheld Metal Detector Market
- Established global OEMs: Firms with long-standing supply contracts for aviation and government buyers emphasize certification, durability, and service networks. Their strength lies in procurement relationships, warranty infrastructure, and brand trust.
- Specialist high-performance vendors: Select European and U.S. companies compete on NIJ-certified performance and tailored law-enforcement features. Their investments in compliance and ruggedization make them preferred in high-risk, mission-critical deployments.
- Cost-competitive OEMs from Asia: Several Chinese manufacturers aggressively pursue volume opportunities with competitive pricing, USB-C convenience, and localized channel strategies. Their agility and cost structure favor large-volume, lower-margin institutional buyers and private sector event managers.
- Recent product signals: Market leaders are refreshing portfolios — from ergonomic, IP-rated flagship units to law-enforcement-specific variants with multifrequency sensing and improved battery management. These launches underscore a bifurcation: commoditized low-end replacements versus premium, service-backed units for critical infrastructure.
Strategic Implications for Manufacturers
- Prioritize NIJ compliance and pre-certification: Invest in aligned testing early. Compliance will expedite access to large public tenders and reduce price competition.
- Diversify battery sourcing and standardize charging interfaces: Lock in supply via alternative suppliers, dual-sourcing contracts, or vertical integration for battery packs. Offer USB-C as a standard to meet operational expectations and reduce friction in recharging logistics.
- Shift go-to-market from product to platform: Build digital services — device health telemetry, usage analytics, and predictive maintenance — as margins in hardware compress. Subscription and managed-service models can smooth revenue and deepen customer relationships.
- Defend premium positioning with service SLAs: For airport and government customers, response time, calibration-free operation, and field-swappable battery options are decisive. Service contracts are a competitive moat.
- Explore bolt-on acquisitions in APAC: Regional OEMs with low-cost manufacturing and channel access are attractive targets to accelerate capacity and reduce lead times for global bids.
Strategic Implications for Buyers and Operators
- Procurement playbook for 2026: Reframe RFPs to prioritize total cost of ownership metrics — run-time per charge, maintenance intervals, field-calibration needs, and end-of-life battery replacement costs — rather than purchase price alone.
- Specify lifecycle services: Include remote diagnostics, replacement battery provisioning, and training bundles in contracts. These additions lower downtime and simplify procurement governance.
- Leverage phased replacement strategies: For large fleets, consider staged upgrades tied to certification milestones. This reduces capital shock and aligns device rollouts to regulatory timing.
- Demand interoperability and data standards: Insist on telemetry-friendly devices with standardized APIs for asset management systems, enabling centralized monitoring and predictive maintenance.
Risk Map — What to Watch in 2026
- Standard updates and procurement pauses: Draft standard rollouts can temporarily slow purchasing as buyers await new compliance baselines.
- Battery supply fluctuations: Price spikes or lead-time increases for lithium-ion cells will compress margins and could trigger substitution risks for lower-grade batteries with shorter lifecycles.
- Counterfeit/gray-market challenge: Price-sensitive channels may introduce unauthorized units that underperform in the field, damaging trust and increasing false-acceptance incidents.
- Service capacity constraints: Rapidly expanding installed bases without corresponding service investments create operational risk and reputational exposure for vendors.
Actionable Priorities — A 90-Day Playbook for 2026
- For manufacturers: Complete NIJ-alignment audits and publish a compliance roadmap; secure at least two battery suppliers; pilot a telemetry-enabled service offering with 3–5 anchor customers.
- For investors: Screen for targets with strong service revenue, certification-ready product lines, and regional manufacturing that shortens logistics lead times; prioritize assets with existing public-sector contract footprints.
- For buyers/operators: Update procurement templates to emphasize TCO and certification; run a fleet audit to classify units for immediate retirement versus phased upgrade; negotiate service-level KPIs tied to device uptime and battery replacement.
What PW Consulting’s Full Report Delivers
The complete Rechargeable Handheld Metal Detector Market report provides practical, executable intelligence designed for immediate integration into 2026 plans. Highlights include:
Rechargeable Handheld Metal Detector Market
- Detailed market sizing and forecasts with scenario modeling and sensitivity analysis across 2026–2032.
- Competitive benchmarking with capability matrices, channel maps, and profile deep-dives of leading vendors.
- Buyer personas and procurement templates that procurement teams can adapt for RFPs and tender evaluations.
- Manufacturing and supply-chain heatmaps identifying single-source risks, near-shoring opportunities, and battery-sourcing strategies.
- Practical go-to-market playbooks for premium and volume segments, including pricing levers, bundling strategies, and aftermarket monetization paths.
- M&A screening criteria and a shortlist of strategic acquisition targets and partnership profiles by region and capability.
Concluding Guidance
The rechargeable handheld metal detector market in 2026 sits at the intersection of regulatory tightening, technology convergence, and enduring demand for reliable screening. For incumbents, the path to defend margins and accelerate growth runs through certification, battery resilience, and services. For challengers and investors, opportunities exist in regional consolidation, software augmentation, and targeted bolt-on acquisitions. For buyers, the tactical advantage accrues to teams that reframe procurement around operational uptime, lifecycle cost, and compliance readiness.
PW Consulting’s full analysis contains the granular models, vendor scorecards, and procurement-ready templates needed to convert these insights into action. To access the complete dataset and interactive strategic tools, please visit the report portal.
For detailed analysis of this topic, please visit the official page: Rechargeable Handheld Metal Detector Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


