



PW Consulting: IoT in Energy to reach USD 76.8 Billion by 2032 at 13.08% CAGR

IoT in Energy 2026: A Strategic Preview for Decision Makers
Executive snapshot
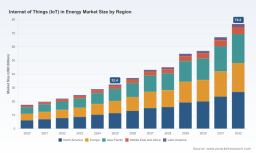
The Internet of Things (IoT) is no longer an experimental layer in energy systems — it is a structural element reshaping how generation, transmission, distribution and consumption are planned, operated and monetized. Our latest PW Consulting market study, with a base year of 2025 and a forecast through 2032, maps this transformation and translates it into practical decision frameworks for 2026. The market has already moved from USD 17.5 Billion in 2020 to roughly USD 32.4 Billion in 2025 and is projected to reach approximately USD 76.8 Billion by 2032, implying a robust compound annual growth rate of about 13.08% over the forecast period. These macro dynamics make 2026 a pivotal year for capturing strategic advantage — the choices you make now will determine whether you lead or lag as deployments scale.
Internet Of Things Iot In Energy Market
Why 2026 matters: inflection points and timing
Two simultaneous forces converge in 2026. First, capital flows into clean energy and grid modernization have accelerated — global energy investment is set to reach roughly USD 3.3 trillion in 2025, with a sizeable portion directed at renewables, grid, storage and related infrastructure that are natural hosts for IoT-enabled control and analytics. Second, connectivity and edge compute economics (driven by wide-area protocols, low-cost modules and hardened edge platforms) have passed critical thresholds, enabling utility-grade use cases at scale. The result is a maturation window where proof-of-concept pilots must convert into sustained rollouts — and where architectural, commercial and regulatory choices become irreversible at scale.
Internet Of Things Iot In Energy Market
What the numbers tell you (not everything we measured)
- Historical momentum: the market nearly doubled over five years to 2025, reflecting accelerating deployment of sensors, connectivity and analytics across energy value chains.
- Forecast trajectory: our forecast to 2032 anticipates more than doubling from the 2025 base, driven by greater telemetry density, software-led monetization and an expanding set of edge-cloud services.
- Market structure: despite significant activity from major industrial players and new entrants, concentration remains low — a structural feature that favors partnerships, vertical specialization and niche strategies.
Strategic implications for corporate leaders
For executive teams, the headline is straightforward: invest selectively and move deliberately. The following implications should shape strategic planning for 2026.
Internet Of Things Iot In Energy Market
- Prioritize architecture, not point solutions. The winners will be those who can guarantee secure, interoperable data flows from edge devices to cloud-native analytics, and who can demonstrate deterministic outcomes (reliability, loss reduction, flexibility markets participation) rather than generic efficiency claims.
- Embed regulatory and policy scenarios into roadmaps. Executive actions and interconnection policies — for example, grid reliability mandates and clean energy procurement rules — will materially affect deployment cadence and allowable business models across jurisdictions.
- Shift from capex pilots to opex platforms. Many utilities will prefer managed-service or outcome-based commercial models to accelerate adoption while conserving capital. Vendors should build flexible pricing and SLA constructs to capture this demand.
- Design for lifecycle economics. Procurement decisions in 2026 must be evaluated against seven- to ten-year total cost of ownership perspectives that include software updates, cyber resilience, calibration and data value extraction.
Operational levers for scaling IoT programs
Operational excellence becomes the bottleneck once pilots move to regional or national scale. In 2026, organizations should focus on three execution levers:
- Standardized validation gates: create a light but rigorous set of design, security and performance gates that any vendor solution must pass before being allowed in production.
- Edge-first data strategies: balance where analytics run. Use edge processing to reduce latency and network cost, and reserve cloud layers for model training, historical analytics and cross-domain orchestration.
- Interoperability and supplier diversity: avoid single-vendor lock-in by adopting open standards where possible and building integration layers that can onboard multiple device types and protocols.
Competition and capability mapping
The competitive landscape is populated by industrial incumbents, networking specialists and metering-focused vendors. Each archetype brings different strengths and commercial models. Below we summarize the strategic posture of ten leading vendors and their implications for buyers and partners.
- Siemens AG (Munich) — Strength: end-to-end digital twins and grid automation. Strategic posture: platform-led, with deep integration into transmission and distribution projects; ideal partner for utilities seeking systems integration and long-term digitalization programs.
- Schneider Electric SE (Rueil-Malmaison) — Strength: energy management architecture and building-grid convergence. Strategic posture: solution bundler focused on energy efficiency and renewable integration within commercial and industrial estates.
- ABB Ltd. (Zurich) — Strength: asset performance and grid stability solutions. Strategic posture: positioned to win on reliability and legacy grid modernization, especially where electro-mechanical asset expertise matters.
- General Electric (GE Vernova) (Cambridge, MA) — Strength: industrial IoT platforms and ADMS. Strategic posture: targets utilities seeking operational analytics and asset optimization across generation and distribution.
- Honeywell International (Charlotte, NC) — Strength: building and industrial energy systems with a strong performance optimization platform. Strategic posture: effective in industrial and commercial environments where process integration and safety overlap with energy use.
- Cisco Systems (San Jose, CA) — Strength: networking, secure edge compute and industrial connectivity. Strategic posture: infrastructure-first vendor for large utilities and operators prioritizing cyber-hardened connectivity.
- Hitachi Energy (Zurich) — Strength: digital substations and grid automation. Strategic posture: enterprise-grade offerings for transmission and distribution modernization, recently recognized as a market leader in industrial IoT platforms for energy.
- Itron Inc. (Liberty Lake, WA) — Strength: smart metering and AMI with deep utility relationships. Strategic posture: go-to supplier for large-scale metering programs and meter-to-cloud data services.
- Landis+Gyr AG (Zug) — Strength: grid-edge intelligence and smart metering. Strategic posture: focused on distribution edge solutions and integration with utility OMS/MDMS stacks.
- Semtech (formerly Sierra Wireless) (Camarillo, CA) — Strength: cellular and LPWAN modules for utility applications. Strategic posture: key connectivity supplier enabling low-cost device rollouts at scale.
Recent signals you should monitor in 2026
- Massive-scale connectivity platforms: LoRaWAN deployments surpassed 125 million devices globally and continue to expand rapidly — utilities remain a leading vertical. This validates low-power wide-area networks as credible production architectures for grid edge telemetry.
- Standards and edge projects: LF Edge initiatives and similar open projects are moving from pilots to production use cases (for example, verifiable carbon measurement in bio-gas plants), making open edge stacks a commercial consideration — not just academic interest.
- Policy drivers: national and regional policy (including executive orders focused on grid reliability and security) will shape procurement priorities and accelerate funding for grid digitalization programs.
Investment and M&A posture
Given the market’s growth trajectory and fragmented supplier base, 2026 is a year for targeted inorganic moves and capability fills rather than large-scale consolidation. Strategic acquirers should prioritize:
- Edge compute and device management capabilities that close the operational gap between device fleets and cloud orchestration.
- Data rights and analytics IP that can convert telemetry into recurring revenue streams (e.g., predictive maintenance, flexibility services participation).
- Channel and utility relationships that accelerate procurement cycles and reduce pilots-to-production friction.
What’s in the PW Consulting report (practical, actionable deliverables)
Our full study is built for strategy teams and implementers. Key operational deliverables include:
- A validated top-down market model and scenario analyses through 2032 that quantify adoption drivers and sensitivity to policy and commodity trends.
- Vendor scorecards and capability matrices mapping product, service and go-to-market strengths to utility and industrial buyer needs.
- Playbooks for procurement, pilot-to-scale transitions, and outcome-based contracting templates tailored to energy sector risk appetites.
- Technical architecture blueprints that prescribe edge/cloud partitioning, cyber controls and interoperability patterns across common protocols and legacy interfaces.
- Case studies and TCO frameworks from live deployments that expose hidden cost drivers and identify high-impact efficiency levers.
How to use this intelligence in 90 days
Leaders should convert insight into action with a focused 90-day program: 1) align executive sponsors and define 12–36 month outcomes; 2) run a rapid vendor bake-off using the PW Consulting validation gates; 3) design a pilot pipeline with clear scale triggers and funding mechanisms; and 4) lock in strategic partnerships for connectivity, cybersecurity and data monetization. Rapid execution in 2026 will capture first-mover advantages in flexibility markets, DER orchestration and resilience services.
Closing — the trailer, not the film
This preview highlights why IoT will be a defining component of energy strategy in 2026 and beyond. It surfaces the strategic trade-offs, execution levers and competitor moves that matter now. The full PW Consulting report contains the granular segment economics, vendor benchmarks and decision tools required to operationalize these insights — including downloadable models and procurement templates designed for immediate use. Accessing the complete study will give you the segment-level intelligence and executable artifacts to convert 2026 momentum into sustained market leadership.
For detailed analysis of this topic, please visit the official page: Internet Of Things Iot In Energy Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


