



PW Consulting: High Purity L-Glutamine Market to Reach USD 418.28 Million by 2032 at 7.91% CAGR

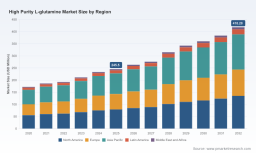
High-Purity L‑Glutamine Market: Strategic Imperatives for 2026 Decision‑Making
As PW Consulting’s Senior Strategic Advisor and Head Industry Analyst, I present an executive preview of our new market study on High‑Purity L‑Glutamine. The study synthesizes a five‑year historical view (2020–2025, base year 2025) and delivers a forward forecast across 2026–2032. At the macro level, the global market—measured in USD Million—is growing robustly, with the 2025 base-year valuation and a forecast path that takes the market materially higher through 2032, driven by a compound annual growth rate (CAGR) of 7.91% across the forecast window. This preview is designed to demonstrate the depth of our analysis and the practical, transaction‑grade guidance embedded in the full report, while intentionally reserving detailed segment and share tables for subscribers and direct engagements.
High Purity L Glutamine Market
Why this study matters to corporate leaders in 2026
-
Strategic timing: 2026 is shaping up to be a hinge year—policy shifts, raw material movements, and capacity investments announced in 2024–2025 are now influencing supply and pricing dynamics.
High Purity L Glutamine Market -
Decision relevance: procurement, capacity planning, regulatory filings, and M&A activity planned this year will crystallize exposure to supply risk or competitive advantage for the next seven years.
High Purity L Glutamine Market -
Actionability: our study converts market forecasts into prioritized options and financial outcomes—so executives can move from data to board-ready decisions within weeks.
Market trajectory and structural drivers
High‑purity L‑glutamine sits at the intersection of biologics manufacturing, cell therapy and cultured cell workflows, clinical nutrition, and the broader nutraceuticals market. Across the historical period to 2025 and into our 2026–2032 forecast, demand growth is underpinned by the expansion of cell culture media and injectable formulations for biologics, alongside continued uptake in clinical nutrition and dietary supplement channels.
Two structural facts are particularly consequential for 2026 planning. First, fermentation‑based manufacture dominates global production—industry data indicate this pathway accounts for the vast majority of supply—implying that upstream feedstock and fermentation capacity cycles drive cost and availability. Second, upstream raw material markets have become more volatile: glutamic acid and other key feedstocks saw price adjustments early in 2026 amid inventory imbalances and softer downstream demand in certain producing regions. Those movements materially affect feedstock cost pass‑through and margin dynamics for suppliers and buyers alike.
Supply chain and capacity dynamics — what to watch in 2026
-
Capacity shifts: recent announcements from large-scale manufacturers indicate an acceleration of capacity expansion outside traditional sourcing hubs. These moves change logistics and lead‑time calculus for global buyers.
-
Quality and certification premium: suppliers with cGMP, USDMF/CEP/JDMF and low‑endotoxin manufacturing capabilities command strategic importance for parenteral and cell‑therapy use cases. Investing to secure these grades is no longer optional for players targeting high‑value segments.
-
Regional trade policy: ongoing trade measures and tariff reviews affecting pharmaceutical ingredients—particularly actions under recent trade investigations—create an overlay of policy risk that can favour local or near‑shore production investment.
Competitive landscape — players, positions, and implications
The marketplace comprises global incumbents with deep fermentation expertise, regional champions with scale and cost advantages, and specialty manufacturers focused on injectable‑grade and research‑grade product lines. Leading multinational producers leverage microbial fermentation technology and robust regulatory filings to serve pharmaceutical and cell culture customers; specialty cGMP firms emphasize low‑endotoxin, low‑metal specifications required by parenteral applications. Several Asian manufacturers are expanding export capacity and product ranges, while regional API and excipient producers in India and Europe strengthen their compliance profiles through active regulatory filings.
-
What it means for buyers: procurement strategy should differentiate between commodity supply and mission‑critical, certified grades. Long‑term contracts, quality audits, and dual‑sourcing arrangements will be critical for clients dependent on parenteral or clinical‑grade material.
-
What it means for investors: quality of earnings will increasingly be tied to regulatory certification and product‑mix rather than absolute capacity. Buyers of producers must value regulatory dossiers, customer concentration, and the ability to upgrade production to parenteral specifications.
Regulatory and policy horizon
Regulatory developments in 2025–2026 have direct strategic implications. Investigations and tariffs targeting pharmaceutical imports introduce complexity for supply chains that rely on cross‑border trade of amino‑acid intermediates and finished L‑glutamine. Some exemptions for certain vitamins and amino acids remain possible, but the policy landscape is fluid. Companies should model tariff‑sensitive scenarios, and consider onshore or nearshore capacity as an insurance strategy where price elasticity and clinical timelines justify the investment.
Risk matrix for 2026 corporate decisions
-
Supply risk: single‑source dependencies, capacity overhang in low‑cost regions, and lead‑time variability for certified grades.
-
Demand risk: cyclical volume swings in cell therapy and bioprocessing programs, and channel substitution in nutraceuticals driven by ingredient alternatives.
-
Policy risk: tariff regimes and import controls that can raise landed costs or force re‑qualification of suppliers.
-
Quality & compliance risk: contamination events or manufacturing non‑compliance leading to batch rejects and costly remediation.
-
Commodity feedstock risk: volatility in glutamic acid and fermentation substrates altering margins and incentive to idle or expand lines.
Practical strategic playbook for 2026
-
Prioritize supplier segmentation: class suppliers by product grade, regulatory coverage, and contingency capacity. Lock in offtake for critical certified grades and maintain tactical frameworks for commodity buys.
-
Dual‑source and nearshore where clinical timelines or tariff exposures make continuity paramount. For high‑value parenteral applications, prioritize suppliers with low‑endotoxin credentials and active regulatory filings.
-
Adopt a staged CAPEX approach: de‑risk greenfield investments with tolling, JV, or capacity reservation agreements before committing full plant spend.
-
Pursue targeted M&A for missing capabilities—quality certifications, regulatory dossiers, or local market access—rather than scale alone.
-
Implement raw material monitoring and hedging: integrate feedstock price dashboards into procurement and product‑margin modelling to enable timely contractual decisions.
-
Differentiate through service: supply chain transparency, guaranteed traceability, and technical support for cell culture and formulation customers create stickiness and premium pricing opportunities.
What PW Consulting’s report delivers (practical and reserved)
Our full study converts the market’s macro momentum into decision‑grade outputs for corporate and investor stakeholders. Key deliverables include:
-
Scenario‑based revenue and margin models across 2026–2032, allowing users to stress test tariff, feedstock and demand shocks against capex and working capital decisions.
-
Supplier benchmarking and procurement playbooks that score manufacturers on certification, traceability, capacity flexibility, and cost position.
-
Regulatory risk dashboards and re‑qualification timelines for key grades and geographies—valuable for supply continuity planning.
-
Commercial templates for offtake contracts, tolling agreements, and JV term sheets designed for rapid execution.
-
Executive briefing slides and tailored, confidential advisory for M&A diligence or strategic sourcing implementations.
Note: this preview demonstrates the analytical depth of our study while intentionally withholding granular segmentation tables and company revenue splits that subscribers and bespoke clients access through the full report and supporting spreadsheets.
Final recommendation — how to act in 2026
For companies exposed to high‑purity L‑glutamine: treat 2026 as a year to convert strategic options into structural protection. That means formalizing supplier segmentation, executing priority certification upgrades where needed, and establishing contingency capacity via contracts or partnerships. For investors and acquirers, focus on capability gaps rather than pure volume—regulatory dossiers, low‑endotoxin manufacturing, and direct customer relationships in cell therapy channels will carry disproportionate value.
PW Consulting is ready to provide the full report, the underlying Excel models, and a tailored briefing that maps these strategic recommendations to your specific exposure and timelines. For access to the detailed datasets, segmentation breakdowns, and supplier scorecards, please visit the PW Consulting research portal or contact our industry team for a confidential briefing.
For detailed analysis of this topic, please visit the official page: High Purity L Glutamine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


