



PW Consulting: Automotive Ethernet Market Poised for 19.5% CAGR (2026–2032)

Automotive Ethernet Market 2026: Strategic Imperatives for Executives Preparing for a Networked Vehicle Future
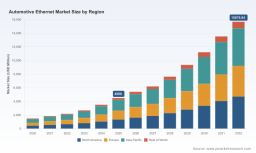
As vehicles transition from distributed electrical architectures to software-defined platforms, Automotive Ethernet has moved from niche experiment to strategic infrastructure. PW Consulting’s upcoming Automotive Ethernet Market research—anchored on a 2025 base year and projecting through 2032—captures this tectonic shift with a rigorous blend of primary research, techno-commercial modeling, and scenario planning. The market we track expanded from roughly $1.5 billion in 2020 to about $4.5 billion in 2025 and is forecast to accelerate at a compound annual growth rate (CAGR) of 19.52% in the 2026–2032 window, reaching an estimated $15.7+ billion by 2032. For leadership teams finalizing 2026 roadmaps, procurement plans, and partnership strategies, this report is designed to be an operational tool—not a marketing brochure.
Automotive Ethernet Market
Why 2026 is a Strategic Inflection Point
-
Bandwidth becomes a governance problem: As ADAS, infotainment, and centralized compute converge, the cost and topology implications of moving to 100BASE-T1/1000BASE-T1—and increasingly 10GBASE-T1—are no longer purely technical. They inform vehicle architecture, supplier selection, and OPEX planning.
Automotive Ethernet Market -
Standards + regulation compress timelines: New and updated standards (ISO 10681 series, OPEN Alliance committees) and regulatory requirements (notably cybersecurity mandates such as UN ECE R155) are creating hard gates for type approval and limiting design freedom for legacy, proprietary bus systems.
Automotive Ethernet Market -
Supplier consolidation and specialization: Market concentration metrics indicate a competitive landscape where a small group of firms account for the majority of supply leadership—creating both dependency risk and M&A opportunity.
What the Report Delivers (Practical, Actionable Content)
-
Executive roadmaps: A prioritized set of short-, medium- and long-term actions for OEMs, Tier-1s and semiconductor suppliers tied to adoption scenarios (conservative, base, accelerated).
-
Scenario-based financial modeling: Sensitivity analyses that translate PHY, switch and software cost declines into vehicle BOM and total cost of ownership outcomes across centralized and zonal architectures.
-
Vendor benchmarking and competitive matrix: Capability maps covering PHYs, MAC-PHY integration, switch throughput, deterministic networking, software stacks and testing toolchains—benchmarks that inform make/buy decisions.
-
Regulatory and standards impact assessment: Timing and design implications of ISO, IEEE, OPEN Alliance work items and UN ECE cybersecurity requirements.
-
Testing, validation and certification playbooks: Practical steps and checklists for lab and in-vehicle verification, including deterministic-networking test cases and EMI mitigation guidance for higher-speed PHYs.
-
Supply-chain and procurement playbook: A risk matrix for single-source dependencies, long-lead component risks, and contract constructs for co-development and IP sharing.
-
Vendor and partner engagement templates: Negotiation levers for joint development agreements, NRE structures, and revenue-share models tied to gateway and domain-controller deployments.
Core Market Dynamics and Technology Constraints
-
Multi-tier standards landscape: OPEN Alliance work on multi-drop and high-speed profiles (TC8/TC10), ISO’s evolving phy requirements and IEEE legacy constraints shape allowable topologies and permissible PHY choices.
-
EMI and signal integrity are not solved problems: 1000BASE-T1 and beyond require sophisticated DSP techniques and carefully specified cable/connectors. These technical constraints translate to supplier differentiation and increase the value of validated reference designs.
-
Cybersecurity is now a procurement filter: UN ECE R155 and OEM cyber policies have elevated secure boot, segment isolation, and log/audit capabilities to mandatory design elements—impacting software, hardware and lifecycle services.
-
Functional safety and power design: Power-over-data-line approaches remain constrained by ISO 26262 safety isolation requirements—limiting some low-cost sensor consolidation strategies and shifting design choices toward dedicated power architectures.
Competitive Landscape—How Key Players Are Positioning
The market is shaped by semiconductor incumbents, specialist switch vendors, and tool providers. Competitive dynamics are defined less by single-product wins and more by ecosystem plays: PHY performance + software stacks + test/validation capabilities + OEM relationships. Notable strategic positions include:
-
Broadcom Inc. —leveraging scale in PHYs and switches, Broadcom’s recent compliance progress with high-speed profiles underscores a push into 10G-class automotive Ethernet, where certification breadth matters for tiered supply strategies.
-
Marvell Technology —demonstrated vehicle integrations highlight the commercial traction of their higher-speed PHYs; integration into OEM platforms acts as a leading indicator for accelerated high-bandwidth ADAS adoption.
-
NXP Semiconductors —continues to marry PHY and SoC capabilities, positioning itself for zonal and domain-controller plays with products tailored for SDV architectures and OEM-grade switch solutions.
-
Texas Instruments and Microchip —target cost-performance and volume gateway applications, emphasizing robust 100BASE-T1 implementations for mass-market segments where price sensitivity dominates.
-
Analog Devices —focusing on specialized PHYs for long-reach sensor networks, providing design advantages in architectures that favor distributed sensor topologies.
-
Renesas —moving to integrate 10G-class Ethernet into SoCs in collaboration with automotive suppliers, placing them at the confluence of compute and network consolidation strategies.
-
TTTech Auto, Vector, Intrepid —specialists in deterministic networking, test & validation and diagnostics. Their tools and software are increasing in strategic value as OEMs require production-grade verification and in-field diagnostics for Ethernet stacks.
Recent vendor activity through 2025—product launches, vehicle integrations and compliance certifications—signals an acceleration toward higher-rate Ethernet in production vehicles. These moves validate the market’s upwards trajectory, but they also raise the bar for verification and supply-chain coordination.
Strategic Recommendations for 2026 Decision-Makers
-
Adopt a two-track architecture strategy: Validate a zonal baseline for near-term cost control while maintaining a phased path to centralized compute for ADAS and domain consolidation. Use PoC programs to stress-test both supply and cybersecurity postures.
-
Prioritize supplier qualification for PHYs and switches with proven EMI performance and compliance records. Where possible, secure dual-sourced design wins or contingency agreements to mitigate single-vendor risk.
-
Invest in in-house or co-developed validation capabilities. The complexity of high-speed automotive Ethernet makes third-party test tools and deterministic-networking stacks mission-critical—delay here increases recall and field-failure risk.
-
Align procurement windows with standardization timelines. Certification and regulatory gating will dictate production readiness; early alignment prevents costly late-stage redesigns.
-
Factor cybersecurity and functional safety into supplier KPIs and contracts. UN ECE R155 and ISO 26262 constraints translate into recurring lifecycle obligations and potential warranty exposure.
-
Consider non-linear revenue streams: software-enabled features, OTA update services, and managed diagnostic offerings can offset hardware margin pressure as component prices decline.
What We Withhold (and Why)
To preserve the report’s strategic utility and to respect the “trailer” principle, we deliberately do not publish granular regional, application or component revenue splits in this introduction. The full report contains an exhaustive breakdown by region, component and application—complete with downloadable Excel models, supplier scorecards and primary-interview transcripts. This granularity is essential for supplier selection, capex modeling and M&A diligence, and is available through PW Consulting’s full deliverable.
Concluding Note
For 2026 planning cycles, Automotive Ethernet is not an incremental engineering choice—it is a portfolio-level decision that impacts product architecture, supplier ecosystems, regulatory compliance, and long-term service models. With a market expanding from multi‑billion dollars today to a projected multi‑billion scale by 2032 at a near‑20% CAGR, the opportunity and the risk are both pronounced. PW Consulting’s Automotive Ethernet research gives leadership teams the frameworks, metrics and tactical playbooks necessary to convert network transition into competitive advantage.
Access the full report to obtain the detailed segmentations, vendor matrices, scenario models and procurement templates necessary to operationalize these insights in 2026.
For detailed analysis of this topic, please visit the official page: Automotive Ethernet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


