



PW Consulting: Ultra White Rolled Solar Glass Market to Reach USD 38.2B by 2032

Ultra White Rolled Solar Glass Market — Strategic Briefing for 2026 Decision‑Makers
Executive summary
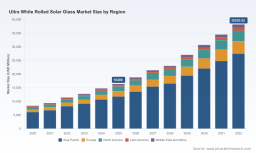
PV glass has moved from a component line item to a strategic lever for module makers, system integrators, and investors. Our PW Consulting Ultra White Rolled Solar Glass Market study—base year 2025, forecasting 2026–2032—shows a market that expanded rapidly through 2020–2025 and is set to grow at a robust compound annual growth rate (CAGR) of 12.84% over the 2026–2032 forecast window. The total market value in 2025 stood at USD 16,400 million and the model projects continued scaling through the forecast period, reflecting both demand-side expansion and supply-side reconfiguration. This briefing explains why the study is strategically valuable for 2026 decisions and what practical outputs clients can deploy immediately.
Ultra White Rolled Solar Glass Market
Why this research matters in 2026
-
Policy and procurement are reshaping demand signals. Recent US policy moves—materially including targeted investment tax credits and financing support—have created first‑mover advantages for domestic producers while changing the calculus for module and component localization.
Ultra White Rolled Solar Glass Market -
Supply‑side reconfiguration is underway. Incumbent global producers and new regional entrants are commissioning lines and furnaces, shifting where and how ultra‑white rolled solar glass is produced, tempered, and coated. These dynamics directly affect availability, lead times, and long‑term pricing trajectories.
Ultra White Rolled Solar Glass Market -
Raw material pressure and downstream efficiency gains are converging. Ultra‑low iron silica sand markets and anti‑reflective coating technologies are now strategic inputs: changes in feedstock pricing or procurement bottlenecks can meaningfully alter module-level performance economics.
What senior leaders can extract from the report
-
Actionable forward views for capacity planning: our demand model translates module deployment scenarios into glass throughput and capital‑intensity requirements, enabling CFOs and plant planners to test capacity timing against financing windows.
-
Procurement playbooks: shortlists, tender structures, price‑indexing templates, quality acceptance criteria and durability testing checklists tailored to rolled/embossed ultra‑white glass versus float alternatives.
-
Regulatory and incentive mapping: a concise matrix linking domestic content rules, tax credits, and loan facilities to supplier selection and site choice for new furnaces or roll forming lines.
-
M&A and partnership frameworks: valuation sensitivity templates, earn‑out structuring options for brownfield acquisitions, and integration checklists for verticalized module manufacturers.
Scope and practical contents of the full study
The report is designed to be a board‑level decision tool that is also directly usable on the plant floor. Deliverables include: a transparent demand model (2020–2032) with scenario toggles; a supply map with existing and commissioned line intelligence; technology assessments comparing rolled, embossed and float routes; techno‑economic models for new line capex/opex; detailed supplier scorecards; a procurement negotiation dossier; and risk heatmaps covering raw materials, logistics and policy. For confidentiality and strategic positioning reasons—consistent with the “trailer” principle used throughout this briefing—we provide high‑certainty aggregate market sizing and growth metrics here, but granular segment allocations by region, thickness and application are reserved for the full dataset available from PW Consulting.
Competitive landscape — where industry power is concentrated
Market concentration is meaningful: the top three manufacturers account for a majority share of global supply, and the top five consolidate roughly three quarters of available capacity. That concentration underpins suppliers’ pricing power in constrained cycles and creates high barriers to rapid commoditization.
-
Xinyi Solar Holdings Limited — a clear technology and scale leader. Its calendering process for ultra‑clear patterned rolled glass and integrated anti‑reflective offerings make it a preferred long‑term partner for high‑efficiency module producers. Xinyi’s large daily melting capacity and recent commissioning of a furnace in Indonesia (Jan 2026) illustrate their strategy of geographic diversification to serve both module fabs and regional demand centers.
-
Established Chinese producers such as Ancai Hi‑Tech, Flat Glass Group, CSG and Qingdao specialists combine technical know‑how with scale and a dense supplier ecosystem. Their strengths lie in cost competitiveness and speed to scale, which remains decisive in price‑sensitive markets.
-
European and Turkish players , led by companies like Şişecam and AGC, are differentiated by patterned glass expertise, AR coating capabilities, and regulatory compliance for markets with stringent material and environmental standards. AGC’s focus on extra‑clear float routes and arsenic/antimony‑free glass is attractive for module makers prioritizing chemical compliance and optical purity.
-
North American entrants such as Stewart Glass and Vitro are redefining local supply economics. Stewart’s new Ohio facility (production start 2026) and Vitro’s Texas expansion (supported by a significant IRS investment tax credit announced in 2025) are practical responses to US localization incentives and supply chain resilience strategies. Stewart’s small‑to‑medium‑scale capacity and Vitro’s large expansion demonstrate two distinct plays: agile local supply versus large industrialized throughput.
Recent developments that matter for 2026
-
Capacity commissioning across geographies: several new furnaces and roll lines came online or were commissioned in late‑2025 and early‑2026, shifting lead times and regional bargaining leverage.
-
Targeted fiscal support has immediate effects: the US allocation of an investment tax credit for domestic patterned glass capacity and a USDA loan guarantee for an Ohio facility are lowering financing costs for new entrants and materially influencing site selection decisions.
-
Feedstock dynamics are rising on corporate radars. The ultra‑low iron silica sand market, a pivotal upstream input, shows its own long‑term scaling (industry estimates value the market in the low‑billions USD by mid‑decade), making long‑term supply contracts and vertical integration legitimate strategic options.
Strategic implications and recommended actions for 2026
-
For module manufacturers: lock differentiated glass supply via multi‑year offtakes tied to quality and performance KPIs (transmittance, AR durability). Negotiate price‑step clauses linked to silica sand indexes and energy inputs to hedge feedstock volatility.
-
For investors and private equity: prioritize assets with flexible tempering and coating capabilities, proximity to logistic hubs, and existing offtake agreements. Use our valuation sensitivities to stress‑test acquisition targets against shifts in WACC and policy incentives.
-
For policymakers and development banks: targeted support—tax credits, loan guarantees, and conditional incentives tied to employment and domestic value capture—can catalyze localized capacity with outsized impact on energy security and industrial resilience.
-
For suppliers and OEMs: accelerate R&D on AR coatings and thinner glass solutions that enable module efficiency gains; prioritize operational excellence to reduce breakage and yield loss in roll‑to‑roll handling.
How to use this study in boardroom and commercial execution
The utility of the PW Consulting study is its dual rigor and operability: quantitative forecasts are directly linked to procurement templates, capex planning schedules, and legal language for offtake and supply contracts. Use the report to populate your 2026 capex approval package, to model the impact of regional content rules on project LCOE, or to structure earn‑outs in a strategic acquisition. For supply chain teams, the supplier scorecards and risk heatmaps provide immediate inputs for supplier rationalization and emergency sourcing plans.
Access to the full dataset
This briefing deliberately presents high‑confidence macro metrics and strategic interpretation while withholding granular segment allocations by region, thickness and application to preserve the commercial value of the underlying dataset and to encourage informed engagement. The full PW Consulting report contains the complete 2020–2032 time series, scenario toggles, and all segment‑level tables and charts required to execute procurement, investment, and policy strategies in 2026. For clients and prospective subscribers seeking the definitive dataset and executable templates, PW Consulting’s Ultra White Rolled Solar Glass Market report page provides secure access to downloads, models and bespoke advisory engagements.
For detailed analysis of this topic, please visit the official page: Ultra White Rolled Solar Glass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


