



PW Consulting: Cryoablation for Cancer Market to Reach USD 902.41M by 2032

Cryoablation for Cancer: A Strategic Preview for 2026 Decision-Making
As PW Consulting’s lead industry analyst, I present a focused market preview designed to orient executive teams, investors, and strategy leaders preparing for 2026. Cryoablation is moving from a niche interventional tool toward a clinically validated, reimbursable modality with clear commercial inflection points. Our full market study drills into the clinical, commercial, and regulatory vectors that will determine winners and losers over the 2026–2032 horizon. This introduction outlines the strategic value of those findings, highlights tactical implications for product, market access, and M&A strategy, and signals where the report hides the granular segmentation data that matter for executable plans.
Cryoablation For Cancer Market
Why 2026 is a Strategic Inflection Point
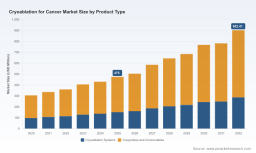
The cryoablation market has demonstrated sustained expansion through the early 2020s, accelerating into the mid-decade as clinical acceptance and reimbursement pathways matured. After a multi-year growth phase, the market reached a meaningful scale by our 2025 base year and is forecast to maintain a high-single-digit compound annual growth rate (CAGR) across the 2026–2032 forecast window. By 2032 the market is projected to approach roughly double its 2025 size, reflecting a confluence of drivers: guideline evolution, regulatory clearances for new indications, better device ergonomics and imaging integration, and growing adoption by outpatient and community hospital settings.
Cryoablation For Cancer Market
For corporate leadership teams, 2026 is the year to translate proof points into commercial scale. Clinical evidence and coding momentum are creating windows for premium pricing and higher penetration of capital equipment and per-case consumables. But those opportunities come with execution risk: capital intensity for hospital purchasers, uneven global reimbursement environments, and a concentrated competitor set that elevates the importance of differentiated clinical claims and channel strategy.
Cryoablation For Cancer Market
What the PW Consulting Report Delivers (Practical, Executable Content)
- Market sizing and trend architecture: a transparent methodological appendix explains how historical performance (2020–2025) and structural assumptions inform our baseline and forecast through 2032, including sensitivity scenarios tied to reimbursement and guideline adoption.
- Go-to-market playbooks: playbooks for incumbents, scale-up challengers, and niche innovators. Each playbook provides prioritized commercial tactics—key opinion leader (KOL) engagement plans, trial designs that close critical evidence gaps, bundling strategies for capital + disposables, and channel mix recommendations.
- Reimbursement and coding roadmap: pragmatic guidance for engaging payors and national coding bodies, including timing for CPT/HCPCS strategies and how to construct hospital economic models that justify capital purchase under current depreciation and CapEx pressures.
- Clinical and regulatory sequencing: an evidence matrix mapping indication expansion, trial endpoints, and regulatory pathways (e.g., De Novo, PMA equivalents), delineating which investments maximize probability of approval in key markets.
- Transaction playbook and valuation levers: an M&A checklist highlighting what matters to buyers—installed base, service revenue, consumable margins, regulatory clearances, and proprietary probe technologies—alongside model templates for accretive acquisition scenarios.
- Competitive positioning and product gap analysis: a comparative framework that evaluates device systems, probe technologies, imaging integration, multi-needle capability, disposables economics, and manufacturing scale—plus prioritized product development investments.
Market Dynamics: The Forces Shaping 2026 Decisions
Several dynamics will determine the pace and shape of adoption in 2026:
- Clinical validation and guidelines: Recent guideline updates have begun to recognize cryoablation as an option for selected low-risk patients in certain tumor types. These shifts lower the barrier to adoption in community settings and support payer discussions.
- Regulatory momentum: The pathway from single-site feasibility to broad label expansion is shortening for some technologies. Notably, post-marketing study designs and multi-site enrollment commitments will increasingly accompany market authorizations, changing commercialization timelines and investment profiles.
- Reimbursement crystallization: Where explicit facility and device coding exists, per-procedure economics become predictable—enabling hospitals to model throughput and ROI. This predictability fuels device and consumable uptake—but only where codes and coverage decisions align.
- Hospital capital constraints: While hospitals face elevated CapEx pressures—driving selectivity in new capital purchases—there is also pent-up demand to modernize aging interventional suites. Large cryotherapy units are a material capital investment; manufacturers who align financing, service, and utilization guarantees will unlock faster uptake.
- Consolidated supplier structure: Market concentration among established device leaders creates both entry barriers and partnership opportunities. Challengers can win by focusing on niche indications, lower-cost disposables, or differentiated clinical workflows that reduce procedure time and staffing burden.
Competitive Landscape: Strategic Implications for Core Players
The market is anchored by a mix of multinational medtech leaders, specialty cryotech firms, and regional device manufacturers. Across this set, competitive advantage accrues to firms that combine regulatory clarity, broad clinical evidence, and service-enabled consumable revenue models.
- Medtronic —Scale and cross-platform leverage: As a global medtech leader, the company can bundle cryo capabilities with broader surgical and imaging portfolios. Strategy implications: defend installed base through service contracts, expand multi-disciplinary sales targeting urology and interventional radiology, and accelerate label expansions via focused registries.
- Boston Scientific (including Galil technologies) —Imaging integration and multi-needle capability: Strengths include MRI-visible systems and percutaneous multi-needle approaches that address larger or irregular lesions. Strategy implications: exploit imaging visibility claims to pursue higher-acuity centers and partner with imaging OEMs to co-promote integrated solutions.
- IceCure Medical —Regulatory and guideline breakthroughs: Recent successful market authorization and guideline updates have created a first-mover advantage in select breast cancer indications. Strategy implications: convert regulatory momentum into reimbursement and site adoption through a well-resourced post-marketing trial program and robust KOL network; consider licensing or distribution partnerships to scale U.S. adoption rapidly.
- CooperSurgical, AtriCure, Erbe, Sanarus and regional providers —Niche specialization and channel reach: These players have strategic options to extend reach via partnerships, OEM supply, or focusing on gynecologic and soft-tissue niches; they can also compete on cost and service in price-sensitive markets.
- Smaller innovators (METRUM CRYOFLEX, CPSI Biotech, HealthTronics, BVM) —Agility and localized advantage: These firms can win in regional and outpatient markets by offering lower total-cost-of-ownership systems or by targeting indications with under-served clinical needs.
Our full report contains an annotated competitor matrix and decision-tree analysis mapping each company’s probable moves and vulnerabilities. For confidentiality and competitive sensitivity, we do not reproduce proprietary share estimates here; instead, the report provides scenario-based concentration analytics to guide M&A and partnership strategies.
Recent Events that Reframe 2026 Strategy
- Regulatory and guideline progress: Recent approvals and guideline updates have begun to legitimize cryoablation for selected early-stage tumors—events that materially change the adoption calculus for hospital administrators and oncologic surgeons.
- Post-market evidence commitments: For some newly cleared indications, manufacturers will need to deliver confirmatory evidence through multi-site trials; this creates timing pressure and opportunities for competitors to close evidence gaps more quickly.
- Reimbursement clarity for discrete scenarios: Where facility-level billing codes or existing HCPCS descriptors apply, providers can model procedure economics—supporting targeted launches in centers of excellence.
- CapEx and consumables economics: Advanced units require meaningful capital outlay, but the recurring disposables model creates an annuity-like revenue stream. Manufacturers who provide innovative financing or utilization guarantees will secure share faster in the constrained hospital CapEx environment.
Actionable Recommendations for 2026 Planning
- Prioritize indications where clinical evidence and payor recognition intersect. Use focused registries to accelerate label expansions and payor coverage decisions rather than broad uncontrolled trials.
- Bundle capital and disposables with outcome-based contracting for high-volume centers. Offer financing and service plans that reduce the hospital’s adoption hurdle.
- Leverage imaging integration as a discriminator: co-develop or co-market with imaging OEMs to position systems for high-acuity cases and to secure preferred status in tertiary centers.
- Strengthen KOL networks and surgical society engagement to translate guideline shifts into procedural volume. Rapidly operationalize post-market study designs to capture real-world evidence and economic endpoints.
- For investors and M&A teams: prioritize targets with high consumable margins, defensible IP in probe geometry or freezing profiles, and established clinical registries. Beware of carve-outs that lack service infrastructures—these require additional investment to scale.
Conclusion — What PW Consulting Recommends You Do Next
Cryoablation is no longer a purely investigational technology; it is entering a phase where regulatory milestones, reimbursement clarity, and hospital purchasing dynamics converge to create real commercial opportunity. Our market forecast and strategic playbooks are structured to help you convert clinical momentum into sustainable revenue streams while avoiding common execution pitfalls.
This preview intentionally omits the granular regional and application-level splits, competitor share percentages, and certain proprietary financials that are included in the full PW Consulting Cryoablation For Cancer Market report. If your 2026 strategy requires transaction-level insight, competitor share scenarios, or downloadable models and playbooks, please refer to the full report and accompanying data package on our website.
For detailed analysis of this topic, please visit the official page: Cryoablation For Cancer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


