



PW Consulting: Acute Care Telemedicine Market USD 27,450.5M (2025), 14.82% CAGR

Acute Care Telemedicine Services Market: Strategic Insights for 2026 Decision-Making
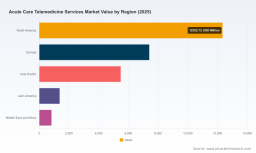
As healthcare systems, payers, and technology vendors confront accelerating demand for remote acute care, the Acute Care Telemedicine Services market is transitioning from a disruptive experiment to an operational imperative. Our latest PW Consulting market research frames this evolution with a clear, investment-grade narrative: the market expanded from roughly USD 20.85 billion in 2023 to an estimated USD 27.45 billion in 2025, and is on a trajectory—driven by clinical adoption, platform maturation, and shifting reimbursement—to exceed USD 72.13 billion by 2032 at a compound annual growth rate (CAGR) of 14.82% (USD, revenue in Million). For executives making 2026 strategy choices, this study is designed to convert that trajectory into near-term advantage while protecting the confidential tactical data that drive competitive differentiation.
Acute Care Telemedicine Services Market
Why 2026 Is a Pivotal Inflection Point
-
Policy and payment clarity will shape capital allocation. Temporary reimbursement policies and state-level licensure reforms are converging toward a new baseline in many markets; decisions made in 2026 will lock in network architectures and contract structures for multiple years.
Acute Care Telemedicine Services Market -
Service model experimentation gives way to scale economics. Early adopters who invested behind proof-of-concept programs in 2022–2024 are now facing operational choices—centralized command centers, hybrid hub-and-spoke architectures, or on-demand staffing—that determine margin capture.
Acute Care Telemedicine Services Market -
Talent and technology constraints are now visible operational risks. Physician shortages and specialist sourcing have already elevated staffing costs and will meaningfully affect unit economics unless mitigated by automation, novel contracting, or cross-state licensing strategies.
Market Trajectory – What the Numbers Tell Us
The reported growth path is not academic: rising from approximately USD 20.85B (2023) to USD 27.45B (2025) signals solid commercial validation across multiple acute-care specialties and hospital settings. The forecast CAGR of 14.82% to 2032 encapsulates sustained demand for tele-ICU, tele-stroke, emergency telemedicine, and other acute modalities as hospitals prioritize throughput, specialist access, and cost avoidance. By 2026 the market is projected to accelerate further—an indicator that 2026 investments will be the fulcrum for capturing scale-related benefits.
Strategic Imperatives for 2026
-
Design for interoperability, not lock-in. Buyers should insist on open APIs, standards-aligned streaming and data exchange, and modular contracting to preserve optionality as clinical workflows adapt.
-
Prioritize clinical ROI over tech novelty. Procurement decisions must be driven by measurable improvements in time-to-treatment, transfer avoidance, and length-of-stay deflection rather than feature checklists alone.
-
Build hybrid operational models. A blend of hub-and-spoke command centers for high-acuity coverage plus localized on-demand services for episodic surges balances cost and responsiveness.
-
Lock down workforce strategies now. Given documented staffing pressures and attendant 15–20% increases in clinician cost in certain settings, organizations should pursue a mix of domestic centralized staffing, locum models, and targeted international partnerships where regulatory and quality frameworks permit.
Competitive Landscape — Who Matters and Why
The sector’s commercial dynamics are shaped by a mix of specialist acute-care providers, digital platform vendors, and integrated health systems. Market concentration is moderate: the top three providers account for a meaningful share of supply while the top five control a majority, indicating room for both scale players and focused specialists.
-
Access TeleCare (Dallas, TX; https://accesstelecare.com) has repositioned itself as a multi-specialty acute telemedicine provider and now emphasizes 24/7 coverage across neurology, psychiatry, critical care and ED support—an approach that favors health systems seeking a single-vendor clinical stack.
-
Eagle Telemedicine (Leawood, KS; https://eagletelemedicine.com) focuses on hospitalist and intensivist services for rural and critical-access hospitals, a profile that aligns with providers prioritizing continuity and local integration over broad platform features.
-
Avera eCare (Sioux Falls, SD; https://www.avera.org/ecare) operates one of the largest acute telemedicine networks, offering command-center models and extensive inpatient coordination—an attractive partner for regional systems scaling clinical oversight.
-
Teladoc Health (Purchase, NY; https://www.teladoc.com) and Amwell (Boston, MA; https://business.amwell.com) have leveraged platform capabilities to serve enterprise hospital customers with tele-stroke, tele-ICU, and ED physician support; their strengths lie in technology depth and integration potential.
-
Sound Physicians (Tacoma, WA; https://soundphysicians.com) integrates tele-hospitalist services into broader acute care management programs, offering a blend of clinical management and on-site services that appeals to system-level purchasers.
Recent moves—rebranding, geographic expansion, and partnerships—signal competitive jockeying for scale and specialty depth. Examples include Access TeleCare’s rebrand to emphasize broader capabilities (Nov 2023), Eagle Telemedicine’s regional expansion (Jan 2024), and Avera eCare’s partnership to bolster rural ED coverage (Jun 2024). These maneuvers are early indicators of the consolidation and alliance strategies likely to intensify through 2026.
What This Report Contains — Actionable Frameworks (Not Just Charts)
-
Commercial models and financial templates calibrated to acute care use cases, enabling CFOs to build 36–60 month P&L scenarios tied to utilization, staffing, and reimbursement sensitivity.
-
Buyer’s playbook for technology selection, including an interoperability checklist, security and latency thresholds, and a vendor scorecard tailored to acute workflows.
-
Regulatory and reimbursement maps that translate federal guidance, state licensure nuances, and accreditation requirements into executable compliance steps for 2026 deployments.
-
Operational blueprints for hub-and-spoke and hybrid delivery models, with staffing templates, escalation protocols, and KPI dashboards designed to shorten time-to-value.
-
Vendor landscape analysis with strategic options (partner, build, acquire) and decision trees for hospital systems, payers and technology vendors.
-
Practical risk matrices covering cybersecurity, clinical governance, and workforce fragility—and mitigation playbooks aligned to senior leadership priorities.
Regulatory, Reimbursement and Standards Dynamics
-
Reimbursement momentum has been supportive—but not permanent. For example, Medicare Part B parity for certain acute telemedicine modalities was extended through the end of 2024; future determinations will influence hospital contracting and capital planning.
-
Cross-state licensure remains a gating factor. Compliance options include state licensure, participation in the Interstate Medical Licensure Compact, and targeted MARs—each with implications for speed to scale.
-
Clinical standards matter. Platforms must meet minimum bandwidth and video-resolution standards as defined by clinical societies to be safe and defensible in high-acuity scenarios.
-
Accreditation expectations are rising: The Joint Commission now expects telehealth programs delivering acute care to adhere to validated safety and quality standards—an operational requirement that influences vendor selection and program governance.
Scenarios and Use Cases—How to Translate Insight into Decisions
-
Scenario A—Rapid Scale: For systems aiming to centralize acute coverage, the study provides phased investment schedules, vendor interoperability requirements, and staffing roadmaps that deliver break-even timelines tied to transfer-avoidance and reduced ICU LOS.
-
Scenario B—Targeted Specialty Rollout: For organizations prioritizing tele-stroke and tele-ICU, the research prescribes technology minimums, partner selection criteria, and outcome-linked contracts for specialty groups.
-
Scenario C—Rural Safety Net: For rural hospitals and health systems, the report identifies partnership archetypes and shared-service models that offset specialist scarcity while preserving local governance.
How Senior Leaders Should Use This Research in 2026
-
C-Suite: Use the strategic options and financial templates to set five-year capital and operating budgets that reflect realistic adoption curves and regulatory scenarios.
-
Procurement & IT: Apply the vendor scorecard and interoperability checklist to upcoming RFPs to avoid costly lock-in and to ensure clinical-grade performance.
-
Clinical Leaders: Leverage the KPI dashboards, accreditation playbook and staffing templates to operationalize quality metrics and control clinical risk.
-
Investors & M&A Teams: Use the competitive landscaping and concentration indicators to prioritize targets and bid strategies that capture consolidation upside or defend against it.
Next Steps and Where to Find the Full Intelligence
This introduction outlines the strategic contours that matter most for 2026 planning—market scale, growth dynamics, competitive moves, and the policy landscape. PW Consulting’s full report contains the proprietary segment models, vendor level scorecards, and executable financial templates that operational teams and boards need to move from intent to execution. To access the complete dataset, scenario models, and implementation-ready tools, please refer to the report landing page linked in our release notes.
In 2026, the winners will be those who convert macro momentum into predictable operations—balancing clinician capacity, regulatory certainty, and interoperable technology while preserving the clinical governance that acute care demands. PW Consulting’s Acute Care Telemedicine Services market research is built to accelerate that transition without exposing the granular segmentation that differentiates proprietary strategies.
For detailed analysis of this topic, please visit the official page: Acute Care Telemedicine Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


