



PW Consulting: Press Hardening Machine Market to Reach USD 1,021.32M in 2025; 7.32% CAGR to 2032

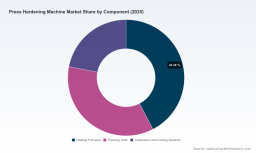
Press Hardening Machine Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As the automotive value chain accelerates its shift toward electrification, stringent safety standards, and heavier integration of ultra-high-strength steels (UHSS), press hardening equipment has moved from a niche production technology to a strategic capital asset. This preview distills the strategic relevance of PW Consulting’s full Press Hardening Machine Market study for 2026 decision-makers. It highlights the macro trajectory, competitive dynamics, operational stress points, and the pragmatic levers executives should consider this year — while deliberately reserving the granular segment and regional tables for subscribers to the full report.
Press Hardening Machine Market
Macro snapshot: a market in growth and industrial transition
The press hardening machine market has demonstrated a resilient recovery and structurally positive outlook. After a cyclical trough in early 2020, the market scaled back to pre-pandemic volumes and has continued to expand, reaching a global market size of approximately USD 1,021.3 Million in the base year (2025). Our forecast model projects continued expansion into the late 2020s, with a compound annual growth rate (CAGR) of around 7.32% through the forecast horizon. By the early 2030s the market is expected to be materially larger than today’s baseline, reflecting persistent demand for lightweight, safety-critical automotive structures, higher throughput automation investments, and energy efficiency-driven retrofits of legacy lines.
Press Hardening Machine Market
Why 2026 is a pivot year for corporate strategy
- Demand signal clarity: OEM specifications for occupant safety and EV platform architectures are cementing the role of press-hardened parts in vehicle bodies. Press hardening enables production of UHSS components with tensile properties up to c. 2000 MPa, and in some modern architectures press-hardened content can account for a material share of the vehicle body measured in double-digit percentages — making the technology a non-negotiable design choice for many platforms.
- CapEx timing and scale: With the market growth trajectory and continuing OEM sourcing commitments, capital allocation decisions made in 2026 will determine equipment vintage for the next decade. Delays or under-investment risk capacity bottlenecks and strategic dependence on third-party suppliers; conversely, oversized early commitments risk underutilization if platform designs evolve.
- Operational transformation: Energy efficiency, inline process monitoring, and automation are no longer optional performance enhancements. Solutions such as servo-driven presses and multi-layer furnace systems can materially lower energy consumption, directly affecting operating margins and environmental footprint.
Dynamics shaping near-term returns and operational risk
- Materials cost volatility: Steel remains the dominant input for press hardening processes. Industry analysis indicates raw-materials represent a dominant share of primary steel production costs, implying that variations in steel pricing and alloy premiums can swing process economics substantially. This underlines the need for procurement flexibility, material-efficiency engineering, and hedging or vertical integration strategies.
- Energy and process efficiency: Field data from leading OEM suppliers shows that servo-driven press solutions can reduce energy consumption of forming operations substantially; combined with multi-layer furnace architectures, firms can realize double-digit reductions in line energy intensity. These gains translate directly to operating cost reductions and improved sustainability metrics — increasingly important for OEMs under regulatory and investor scrutiny.
- Quality and compliance: The adoption of inline process monitoring (pyrometers, IR cameras, closed-loop control) has become a practical necessity for meeting heat-treatment standards and auditability (e.g., CQI-9 equivalents). Process monitoring is also a key enabler for reducing scrap, improving repeatability, and shortening ramp-up cycles for new parts.
- Modularity vs. turnkey trade-offs: Buyers face a choice between highly integrated turnkey lines and modular, upgradable cells. Turnkey suppliers reduce integration risk but can involve longer lead times and higher upfront CAPEX; modular cells can accelerate time-to-market and spread CAPEX over multiple program phases but require stronger in-house systems integration capability.
Competitive landscape — concentration, capability vectors, and tactical moves
The supplier ecosystem is moderately concentrated. The top three vendors account for a clear majority share of the installed base, with the top five capturing a significant portion of global revenues — a structure that favors established turnkey providers but leaves room for niche engineering specialists and custom-equipment manufacturers to capture specialized opportunities.
Press Hardening Machine Market
Key vendor capabilities and implications for buyers:
- AP&T (Ulricehamn, Sweden): A pioneer in the press hardening domain with substantial installed experience. AP&T’s turnkey approach — including servo presses, multi-layer furnaces, SkyLines concepts for large complex components, and embedded inline monitoring — positions it strongly for OEMs seeking integrated, energy-efficient solutions. Their recent SkyLines presentations emphasize multi-part integration and energy optimization for EV manufacturing, a strategic theme for long-cycle platform programs.
- Fagor Arrasate (Arrasate, Spain): Noted for end-to-end automated press hardening systems, including servo-hydraulic hybrid presses and multilevel furnaces. Their strength lies in scale and full-line engineering for high-volume programs where predictable throughput and low-touch operation are priorities.
- Schuler Group (Göppingen, Germany): Focused on high-precision, high-output systems. Technologies that prioritize flexible production (e.g., multi-part per cycle architectures) make them attractive where production mix flexibility and takt variability are required.
- Macrodyne Technologies Inc. (Canada): A vendor for bespoke hydraulic and servo hot stamping presses with deep experience around complex parts. Their approach suits engineering-led OEMs and tier-1 suppliers producing non-standard or evolving part geometries.
- Loire Gestamp (AFM) (Hernani, Spain): Specializes in hydraulic hot stamping and integrated line components. Their practical experience on automotive applications and furnace/transfer systems makes them a choice for projects emphasizing robustness and simplicity.
Recent vendor activity reinforces these themes. AP&T’s mid-2025 SkyLines showcase clarified the energy and sustainability advantages of integrated multi-layer furnace concepts for EV component manufacture, while Macrodyne’s participation at MACH 2026 highlighted continued demand for custom hydraulic press solutions. Buyers should treat vendor roadmaps and demonstrated energy metrics as procurement differentiators, not just price levers.
What PW Consulting’s full study delivers to a decision-maker in 2026
Our full report is built as an operator’s playbook and a board-level briefing in one package. It synthesizes market sizing, supplier benchmarking, economics, operational diagnostics, and executable tactics across a set of deliverables designed for immediate use in 2026 planning cycles:
- Proprietary demand model and sensitivity scenarios that translate vehicle program schedules into equipment demand and utilization profiles across the planning horizon.
- Vendor scoring matrices across technical, delivery, service, energy, and TCO dimensions — with blind-spot checks for retrofit vs new-build economics.
- Practical CAPEX/OPEX models and lifecycle cost calculators to compare technology pathways (hydraulic vs servo-mechanical vs hybrid) and furnace architectures.
- Procurement checklists, sample RFP language, and contractual clauses to mitigate lead-time, warranty, and intellectual property risks.
- Operational playbooks for commissioning, inline process monitoring implementation (pyrometry/IR camera integration), and CQI-equivalent compliance workflows.
- M&A and partnership maps identifying potential tuck-in targets, strategic JV profiles, and integration risk assessments.
- Case studies and plant-layout exemplars that show how to sequence investments to preserve optionality for later platform changes.
To avoid compromising the tactical value of these tools, the preview intentionally omits the granular regional and application splits, vendor revenue tables, and certain price-sensitive unit economics — these are available in the complete report.
Priority moves for 2026 — a practical checklist
- Align CapEx timelines with validated OEM program commitments, using scenario-based gating to preserve optionality.
- Prioritize energy-efficiency investments (servo presses, multi-layer furnaces) where payback matches corporate sustainability targets and regulatory timelines.
- Mandate inline process monitoring for new lines to secure quality, auditability, and reduced ramp-up waste.
- Adopt a layered vendor strategy: partner with turnkey providers for high-volume, mission-critical lines and engage specialist suppliers for complex or low-volume parts.
- Hedge raw-material exposure through procurement contracts, alternative material choices, or process yield improvements that lower material intensity.
- Accelerate workforce upskilling in automation, process control, and furnace metallurgy to reduce reliance on external integrators over time.
- Incorporate supplier energy metrics into procurement scoring to capture life-cycle cost advantages, not only upfront price.
Conclusion — positioning for advantage
For 2026, the press hardening equipment decision is both tactical and strategic. It touches procurement, manufacturing strategy, sustainability targets, and product engineering. The market’s growth profile and the technology-led differentiation across suppliers mean that well-timed decisions will compound into durable competitive advantage. PW Consulting’s full Press Hardening Machine Market study equips executives with models, vendor diagnostics, and executable playbooks to make those decisions with confidence.
For organizations preparing board presentations, supplier negotiations, or industrial transformation roadmaps this year, the complete report contains the underlying tables, vendor scorecards, regional demand splits, and downloadable financial models referenced here. Access to that detailed intelligence will materially shorten decision cycles and sharpen negotiation positions — and it is available on the PW Consulting report page.
For detailed analysis of this topic, please visit the official page: Press Hardening Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


