



PW Consulting: Automated Side Load Trucks to hit USD 3,168.95M by 2032 at 6.42% CAGR

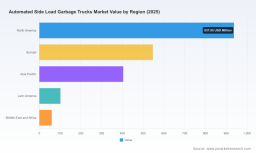
Automated Side Load Garbage Trucks Market — Strategic Outlook for 2026 Decision-Makers (PW Consulting)
Executive snapshot
PW Consulting’s latest market study on Automated Side Load Garbage Trucks provides a compact, decision-oriented briefing for executives, fleet operators, OEMs, and capital allocators preparing plans for 2026. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the analysis shows a market growing at a compound annual growth rate (CAGR) of 6.42%. The industry-wide revenue base reaches approximately USD 2.05 billion in 2025, and our scenarios project material expansion through 2032 as municipalities and private haulers accelerate replacement cycles, electrification pilots, and safety retrofits.
Automated Side Load Garbage Trucks Market
Why this study matters for 2026 strategic choices
- 2026 will be a hinge year: short-term budget cycles collide with longer-term regulatory timetables on emissions and equipment safety. Decisions taken this year will lock in fleet profiles for 7–12 years.
- Capital allocation is shifting from pure vehicle purchases to integrated vehicle-plus-energy and digital-service investments that change total cost of ownership (TCO) profiles.
- Supply-side consolidation has already begun: the top three vendors account for a meaningful plurality of market revenue and the top five approach a clear majority, creating both scale advantages and white-space opportunities for specialist suppliers.
- Operational priorities—route productivity, operator safety, maintenance predictability—are increasingly as important as vehicle acquisition price when evaluating automated side loaders.
Core market dynamics shaping 2026 strategies
Three structural forces dominate near-term strategy:
Automated Side Load Garbage Trucks Market
- Regulatory acceleration: North American and European environmental mandates are tightening emissions and incentivizing low- or zero-emission collection vehicles. At the same time, safety standards require anti-collision sensing, operator presence detection, and emergency override systems—raising the technical bar for next-generation side loaders.
- Technology bifurcation: The market is polarizing between traditional diesel platforms with optimized hydraulics and compaction systems, and electric or gas-adapted platforms that incorporate dedicated energy systems for collection duties. Some manufacturers deploy independent battery systems to power collection functions while remaining chassis-agnostic, which reduces integration risk for municipalities testing electric drive lines.
- Service and retrofit economics: Improved arm design, compaction efficiency, and modular electronics are shifting value to body manufacturers and telematics providers. For many operators, retrofit and aftermarket solutions that extend life and improve safety are becoming higher-return investments than full unit replacement.
Technical realities operators must weigh
Decisions about chassis, body, and control systems are technical decisions with strategic impact. Typical design features to consider in procurement and retrofit planning include:
Automated Side Load Garbage Trucks Market
- Hydraulic systems and lift mechanisms rated for typical residential container ranges and reach envelopes up to industry-standard distances; robustness in compaction (e.g., design compaction loads) is a gating factor for route productivity.
- Independent electric collection systems that allow bodies to function on diesel or electric chassis, simplifying pilots of battery-electric powertrains and reducing vehicle obsolescence risk.
- Mandated safety systems (sensors, operator presence detection, emergency overrides) which alter cab ergonomics and training requirements and can materially change downtime and liability exposure.
Competitive landscape — what the vendor field means for buyers and investors
The automated side loader vendor landscape has a mix of long-established body specialists and nimble niche players. The market exhibits moderate concentration (top three players capture a meaningful plurality; top five approach clear majority), which creates distinct strategic implications:
- Heil Environmental (Chattanooga, TN) — Strengths: full-line automated side loaders with established continuous-pack and electric body variants. Strategic edge in integrated electric body solutions and extended reach arms; ideal partner for fleets seeking turnkey electrified collection bodies while testing chassis electrification. Watch for productization of battery-backed collection modules.
- McNeilus Truck and Manufacturing (Dodge Center, MN) — Strengths: versatile arm designs and modularity across diesel and electric chassis, emphasis on tight-space operation. Competitive posture attractive to large haulers that value route-level flexibility and multiple body-chassis combinations.
- Labrie Enviroquip Group (Quebec) — Strengths: adaptability across manual, semi-automated and fully automated modes. Offers a lower-integration risk path for municipalities wanting staged automation adoption and fallback manual operation during transition windows.
- New Way Trucks (Scottdale, IA) — Strengths: robust lift capacity and under-CDL options; strong appeal to operators focused on payload and compaction performance rather than electrification alone.
- Amrep (California) — Strengths: heavy-gauge wear-plate construction (e.g., Hardox usage) and durability focus; differentiated value proposition where abrasive wear and high cycle applications dominate costs.
- Curbtender Inc. (USA) — Strengths: historical innovator with focused portfolio exclusively on automated side loaders; deep operational know-how and product pedigree dating to the 1970s. Attractive for fleets prioritizing proven designs and field-tested reliability.
- KANN Manufacturing (USA) — Strengths: high-compaction bodies and flexible eject/tip configurations; well positioned where heavy-compaction or specialized disposal workflows are critical.
For suppliers and investors, the market structure favors players who can scale manufacturing efficiencies while adding high-margin services (telematics, maintenance contracts, retrofit kits). For buyers, the vendor set requires a formal scorecard that ranks integration risk, future-proofing (battery compatibility), safety compliance, and aftermarket support.
Strategic playbook for 2026 — recommended actions
Our research translates into a prioritized, actionable playbook for 2026. Below are the top initiatives to operationalize within 90–180 days and the metrics to track.
- Pilot to scale electrification deliberately: Run 12–24 month pilots using body-mounted battery systems before committing to full electric chassis procurements. Track pilot KPIs: route completion rates, duty-cycle energy consumption, and battery availability.
- Adopt a modular procurement standard: Insist on body-chassis decoupling options in RFPs so future chassis swaps are possible without full vehicle replacement. Include clauses for battery interoperability and telematics API access.
- Prioritize safety retrofits: Budget for anti-collision sensors and operator-presence systems as mandatory retrofit items; these reduce liability and are increasingly non-negotiable for compliance.
- Expand aftermarket and retrofit offerings: For OEMs, build higher-margin service contracts around diagnostics, predictive maintenance, and arm-system refresh kits. For investors, target companies offering these recurring revenue streams.
- Use scenarios for CapEx planning: Model TCO under three scenarios (status-quo diesel, hybrid-electric transition, full electrification) to stress-test replacement timing and grant funding impacts.
- Prepare supply continuity playbooks: Given growing demand and moderate concentration at the top, secure long-lead components (hydraulic valves, wear-plate steel, battery modules) via multi-year supply agreements or dual-sourcing strategies.
- Evaluate M&A selectively: Targets that bring telematics, battery-integration IP, or specialized compaction/eject systems offer the fastest path to margin expansion and defensible differentiation.
What the full PW Consulting report delivers (practical contents)
The full study is designed to be immediately actionable for procurement, fleet planning, and corporate strategy teams. Key deliverables include:
- Scenario-based financial models (TCO, CapEx/Opex sensitivity) calibrated to multiple duty cycles and electrification pathways.
- Supplier scorecards and RFP templates that encode safety and interoperability requirements.
- Retrofit economics and break-even analyses for extending vehicle life vs. replacement with electrified units.
- Regulatory compliance checklists tied to OSHA, EU Machinery Directive, and regional emissions rules—mapped to product and retrofit requirements.
- Case studies of pilot deployments and a playbook for scaling from proof-of-concept to fleet-wide rollouts.
- Deal-level guidance on partnerships, JV structures, and M&A targets informed by market concentration and service adjacencies.
In keeping with our “trailer” principle, the full report includes detailed segment-level figures, regional allocation, and proprietary unit economics that are reserved for subscribers and the primary report download. High-level macro metrics (base year, forecast period, CAGR, and consolidated concentration indicators) are summarized above to support immediate strategic planning.
How to use this intelligence in three planning horizons
- 90 days: Finalize pilots with two vendor partners (one legacy body specialist, one electric-capable innovator). Implement mandatory safety retrofit policy for priority routes.
- 6 months: Run consolidated TCO scenarios for FY27 CapEx and adopt a modular procurement template. Begin supplier qualification for battery modules and telematics providers.
- 18 months: Scale successful pilots across high-value routes, execute on aftermarket service rollouts, and consider M&A to acquire technical gaps in battery integration or telematics.
Conclusion — the strategic value for 2026
For 2026 decision-makers, the automated side load garbage truck market presents a clear set of opportunities—and pitfalls. The sector is growing at an annualized pace in the mid-single digits, driven by emissions policy, safety mandates, and a shift to lifecycle-focused procurement. Success will not come from choosing the lowest-cost body or chassis in isolation; it will come from orchestrating chassis, body, energy systems, and services into an interoperable, safety-compliant, and financially defensible fleet strategy.
PW Consulting’s full report supplies the segment-level numbers, supplier comparisons, and executable templates organizations need to move from strategy to execution. Access the full study to obtain the detailed segment breakdowns, regional allocations, and proprietary models that inform precise CapEx budgeting and vendor selection.
For detailed analysis of this topic, please visit the official page: Automated Side Load Garbage Trucks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


