



PW Consulting: Off‑Road Fuel Tank Market to hit USD 3,191.34M by 2032 at 5.48% CAGR

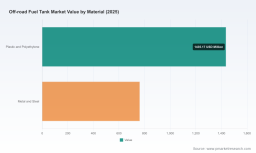
Off-Road Fuel Tank Market — Strategic Outlook for 2026 Decision Makers
As PW Consulting’s senior industry analyst, this briefing frames how the Off-Road Fuel Tank market will matter to executive choices in 2026. It is structured as a strategic “trailer”: enough analytical depth to validate the study’s rigor and to orient decisions, while intentionally withholding granular segment tables and competitive share grids so stakeholders must consult the full report for transaction-level intelligence.
Off Road Fuel Tank Market
Market snapshot: scale, trajectory, and what it means for 2026
The off-road fuel tank market has moved from a recovery phase into a steady expansion. After recovering from pandemic-related distortions, the industry reached an estimated USD 2,196.8 Million in 2025 and is modeled to grow at a compound annual growth rate (CAGR) of 5.48% through the forecast window. By 2032 the market is projected to approach roughly USD 3.19 Billion. That trajectory reflects a combination of sturdy underlying demand from construction, agriculture and mining equipment fleets, plus structurally higher content per vehicle driven by emissions rules and durability requirements.
Off Road Fuel Tank Market
For 2026 decisions, the headline is simple: the market is large enough to justify strategic moves (capex, supply-chain reconfiguration, M&A) but remains dispersed enough that choice of partner and technology will materially affect margin and growth outcomes.
Off Road Fuel Tank Market
Key forces that will shape winners and losers in 2026
- Raw material volatility and cost pass-through: Metal prices spiked into 2026—aluminum mill shapes surged and steel mill products registered double-digit increases—adding pressure to manufacturers with metal-heavy bill-of-materials. Plastic producers saw elevated HDPE prices in 2025, and near-term resin availability will be a determinative cost lever for plastic tank makers. Companies that can flex material mix, optimize gauge, or secure long-term resin and metal contracts will gain a competitiveness edge.
- Regulatory tightening on evaporative emissions and heavy-duty GHG: Ongoing EPA and CARB enforcement for small off-road equipment (SORE) is accelerating adoption of multi-layer and low-permeation plastic designs. Simultaneously, heavy-duty GHG rules (Phase 3) are raising systems-level scrutiny of fuel systems in off-highway contexts. Compliance is now a product differentiator—suppliers that can demonstrate certified permeation performance and traceable compliance documentation are becoming preferred OEM partners.
- Material and manufacturing technology divergence: The market is bifurcated between traditional metal fabrication and high-volume plastic processing (blow molding, co-extrusion). Cross-linked and military-grade polymers are carving out niches in high-capacity and aftermarket applications. Suppliers with capabilities across multiple material platforms (or nimble outsourcing strategies) can capture more content per machine or vehicle platform.
- Aftermarket and lifecycle services growing in strategic value: Auxiliary and replacement tanks, long-range refueling systems, and field-service fuel trucks (for mining/construction) are margin-rich channels. Players that pair product with service—installation, certification, localized spares—can expand total addressable margin even where new-equipment growth is moderate.
Competitive landscape — what the leading players signal about strategic priorities
The industry structure is moderately concentrated: a handful of established manufacturers anchor supply while a long tail of specialized fabricators and blow-molders address niche and aftermarket needs. Key company positions in the competitive map illustrate three enduring strategic plays:
- Full-spectrum metal fabrication and heavy-capacity suppliers: Firms with deep sheet-metal and hydraulics expertise, such as IFH Group and Standard Technologies, continue to win OEM programs that demand large volumes, welded solutions, and integrated reservoirs. Their strengths are customization, large-lot capabilities, and long-standing OEM approvals.
- High-volume polymer specialists: Blow-molders like Agri-Industrial Plastics and European plastic tank makers have invested in multi-layer co-extrusion and EPA/CARB-compliant low-permeation designs. Their advantages are high throughput, lower per-unit weight, and regulatory compliance that especially resonates in SORE and small off-road segments.
- Aftermarket and specialty system providers: Transfer Flow, TITAN Fuel Tanks, Harmon Racing Cells and Extreme Tanks focus on auxiliary, replacement, and high-performance niches—areas where product differentiation (range, ruggedness, certification) allows premium pricing and quick time-to-market. Niece Equipment illustrates the adjacent service-led model for very large-capacity refueling fleets used in mining and heavy civil works.
Implication for 2026: market movers will either strengthen one of these plays by vertical integration and capacity locking, or juxtapose them—pair plastic molding capability with metal fabrication and a services arm—to offer platform-agnostic solutions to OEMs and fleet operators.
What the PW Consulting report delivers — practically actionable components
- Market-sizing model with scenario toggles for raw-material price shocks, regulatory tightening, and fleet replacement cycles—enabling “what-if” budget planning for 2026 procurement and capex.
- Supplier scorecards and bench-learning covering manufacturing footprint, material expertise, lead times, certification status, and cost-to-serve profiles—built to accelerate sourcing decisions without full RFQs.
- Regulatory compliance mapping (EPA, CARB, international standards) tied to product design levers and testing paths—so engineering teams can prioritize product roadmaps to meet 2026 requirements.
- Go-to-market playbooks for OEM vs aftermarket approaches, including pricing sensitivities, channel economics, and service-bundling strategies designed to enhance lifetime value.
- M&A and investment thesis section identifying where scale, technology, or geographic presence delivers the biggest strategic payoff—and an integration checklist for target diligence in this sector.
Practical recommendations for decision-makers in 2026
- OEM procurement and product chiefs: Prioritize partners with multi-layer plastic capability and certified permeation data; negotiate flexible contracts that include indexation or hedging clauses for aluminum/steel and HDPE; pilot modular tank platforms to reduce SKUs and improve assembly commonality across equipment families.
- Material producers and blow-molders: Invest in barrier-layer technologies and co-extrusion tooling; secure offtake agreements with tier-1 OEMs; consider backward integration into certification testing to shorten OEM qualification cycles.
- Aftermarket and specialty vendors: Double down on high-margin service bundles (installation, testing, local spares); exploit long-range and auxiliary tank demand among exploration and large-site contractors; use digital channels to certify compatibility and to capture direct-to-operator sales.
- Private equity and corporate M&A teams: Target bolt-ons that fill material-technology gaps (e.g., polymer barrier tech for a metal fabricator) or add differentiated aftermarket service capability. Look for targets with defensible OEM relationships and traceable compliance records.
Risk signals to watch closely through 2026
- Raw-material price indices (aluminum and steel spot prices, HDPE contract movements) and announced capacity additions for PE.
- EPA/CARB rulemaking notices and the implementation timeline for heavy-duty GHG phases affecting off-highway fuel systems.
- OEM orderbooks and fleet capex plans in construction, agriculture and mining—these act as leading indicators for demand cycles.
- Supply-chain disruptions, particularly in regions with high freight volatility or concentration of tooling capacity.
- Signals of accelerated electrification or alternative-fuel adoption in specific off-road subsegments that could compress fuel-tank demand in the mid-term.
In short, 2026 is a pivot year: cost pressures and regulatory compliance will stratify suppliers, while service and aftermarket models will create attractive margin pools. The right combination of material strategy, supplier partnerships, and regulatory foresight will determine which companies capture the upside of the projected 5.48% CAGR.
Next steps
This briefing is a curated preview. The full PW Consulting Off Road Fuel Tank Market study contains the quantitative models, supplier scorecards, regulatory compliance matrices, and M&A screening tools required to operationalize the recommendations above. For program-level briefings, custom scenario runs, or a confidential supplier scouting workshop tailored to your 2026 capital and sourcing calendar, contact PW Consulting to access the complete report and advisory services.
For detailed analysis of this topic, please visit the official page: Off Road Fuel Tank Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


