



PW Consulting: Reverse Osmosis Market to Hit USD 29,004.46 Million by 2032 at 8.24% CAGR

Reverse Osmosis Water Purification Unit Market — Strategic Briefing for 2026 Decisions
Executive trailer: why this analysis matters for boardrooms and strategy teams
As corporate leaders prepare capex, procurement, and M&A priorities for 2026, the reverse osmosis (RO) water purification unit market has shifted from a mature product-market into a dynamic, policy-driven arena that links materials supply chains, regulatory timelines, and circular-economy pressures. Our PW Consulting market research frames these forces into actionable intelligence: a validated market-sizing model with scenario-driven forecasts, competitive scorecards for OEMs and membrane suppliers, and pragmatic playbooks for entering, defending, or reconfiguring RO-related revenue streams.
Reverse Osmosis Water Purification Unit Market Research
Market snapshot (macro-only, strategic signal)
Using 2025 as the analytical base year, the global RO water purification unit market demonstrates a sustained, above-market growth trajectory. Between the historical window and our forecast horizon (2026–2032), the model projects a compound annual growth rate (CAGR) of 8.24% driven by a confluence of residential upgrades, industrial compliance demand, and municipal desalination/pretreatment projects. In monetary terms, the market expands materially from the base year through 2032 under our central scenario, with alternate downside and upside scenarios reflecting regulatory pace and raw-material volatility.
Reverse Osmosis Water Purification Unit Market Research
- Base-year anchoring: 2025 is used as the calibration point for demand, pricing trends, and installed-base rollouts.
- Forecast horizon: 2026–2032 delivers both point forecasts and probabilistic ranges to support budgeting and option-value calculations.
- Market concentration: the competitive landscape is moderately concentrated; the combined share of the top three and top five suppliers provides meaningful scale advantages to incumbents but leaves space for focused challengers.
What this report gives you — practically
PW Consulting’s report is built as an operator’s toolkit rather than a purely academic exercise. It is organized to support decision cycles at the 30,000‑ft level and down to procurement negotiations:
Reverse Osmosis Water Purification Unit Market Research
- Methodology appendix: transparent demand-model logic, source matrix, and sensitivity knobs (price elasticity, replacement rates, water-quality-driven adoption) so you can re-run scenarios with your assumptions.
- Interactive forecasting engine: downloadable spreadsheet models and pre-calibrated scenario tabs (base, regulatory-accelerated, raw-material-stress, and circular-economy adoption).
- Commercial playbooks: go-to-market options for OEMs, distributors, and service providers including pricing levers, margin waterfalls, and lifecycle-service monetization templates.
- Procurement & supplier-risk toolkit: supplier scorecards, contract clause templates for material volatility, and hedging approaches for energy- and resin-exposed components.
- Technical-economic modules: cost-builds for residential, commercial, and industrial RO units, including energy, membrane replacement cadence, and service labor assumptions to calculate total cost of ownership (TCO) and levelized cost of purified water.
- Sustainability and end-of-life playbook: pathways to reduce disposal liabilities and capture value from module remanufacture, NF/UF conversion, or polymer recovery streams.
- Executive one-pagers and investor brief: succinct slide-ready summaries for board discussions and investor Q&A.
Key dynamics shaping 2026 strategy
Four force-multipliers are shaping near-term strategy and should be central to corporate planning for 2026:
- Regulatory recalibration: The U.S. EPA’s reconsideration of wastewater-effluent guidelines and extensions on PFAS drinking-water provisions introduces timing risk but also near-term upside for compliant treatment solutions. Firms that align product development and certification roadmaps to anticipated revisions will capture accelerated procurement windows.
- Raw-material volatility: Precursors used in membrane polymers (notably key bisphenol and sulfone precursors) have exhibited high annual price volatility. This impacts unit economics and supplier risk; cost-transparency clauses and alternative-material R&D are now strategic priorities.
- Circularity and end-of-life flows: By 2025 the installed base generates a significant volume of end-of-life RO modules annually. That creates both regulatory exposure and recycling opportunity; vertically-integrated players and partnerships with recyclers can convert disposal-cost liabilities into feedstock advantages.
- Service-as-revenue and digital monitoring: Remote monitoring and predictive-replacement services are increasing aftermarket revenue capture while enabling higher installed-system uptime—making service networks as important as OEM product specs in commercial negotiations.
Competitive landscape — what to watch
The competitive map combines traditional membrane-material specialists, integrated systems providers, and appliance/OEM players. Our report provides qualitative and quantitative assessments of market positioning, technology moat, vertical integration, and go-to-market reach for each primary competitor. Representative strategic observations include:
- FilmTec and membrane-technology leaders: Established membrane innovators maintain a technology edge through high-rejection thin-film composites and design tools that reduce system-level CAPEX by improving recovery and reducing energy. Look for strategic licensing and co-development agreements where membrane suppliers partner with system integrators.
- Global materials manufacturers: Large diversified chemical and membrane firms remain critical because they control advanced element manufacturing and scale. Their investments in pilot-testing and integrated simulation tools reduce adoption friction for large municipal and industrial buyers.
- Systems and service integrators: Companies offering turnkey systems plus extensive service networks command pricing power in the residential and commercial service segments—especially where full-life maintenance contracts are standard practice.
- Specialists in industrial and boiler-feed applications: Niche suppliers that optimize for high-purity or boiler-feedwater markets can command premium margins but are sensitive to project-cycle risk and commodity-cycle exposure.
We also track near-term strategic moves: product-tool enhancements that accelerate OEM design cycles, new industrial RO models aimed at boiler-feed applications, consumer certification campaigns for market access, and whole-house product introductions that broaden channel footprints. Each of these can materially reshape competitive positioning depending on execution speed and channel partnerships.
Recent developments with strategic implications
- Design-tool integration: Enhancements to membrane-system modeling tools now include integrated RO/NF capabilities and broader element libraries, shortening engineering cycles for complex projects and enabling higher first-pass success rates on bid proposals.
- Industrial product launches: New industrial RO platforms optimized for boiler-feed and high-purity streams reduce integration costs (e.g., built-in softening interfaces and monitoring stacks), lowering adoption barriers for energy-intensive customers.
- Certification and consumer-market activations: Brands securing international standards and showcasing R&D at high-profile exhibitions increase channel trust and accelerate retail/installer adoption.
- Whole-house and countertop innovations: New multi-stage and appliance-integrated systems extend RO beyond point-of-use, expanding TAM but also increasing aftermarket-service expectations.
How executives should use this brief to act in 2026
Translate market intelligence into three operational moves this year:
- De-risk supply chains now: Implement supplier diversification, incorporate material-price escalation clauses, and accelerate trials of alternative polymer chemistries to blunt input-price spikes.
- Monetize service: Design bundled maintenance contracts and predictive-replacement pricing that capture service revenue while optimizing membrane replacement intervals and reducing total customer TCO.
- Prepare for regulatory acceleration: Scenario-plan for earlier-than-expected stricter wastewater and PFAS-related requirements; pre-qualify technologies and pursue joint pilot projects with municipalities and large industrial buyers to secure pipeline advantage.
What you will not find in this briefing — and why
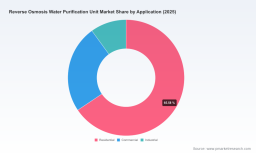
To preserve the strategic value of the primary research and to respect client confidentiality, this trailer deliberately omits granular regional, type- and application-level revenue percentages and specific segment dollar figures. The full report contains those tables, time-series segmentations, and downloadable datasets, along with a supplier-level market-share matrix and the modelling workbooks that corporate strategy, M&A, and procurement teams need to finalize 2026 plans.
Next steps — converting insights into decisions
- Executive briefing call: Schedule a 90-minute workshop with our industry leads to map these findings onto your P&L and capital-planning calendar.
- Customized scenario run: Commission a tailored forecast run using your company’s price, mix, and channel assumptions to quantify upside and downside to EBITDA across 2026–2032.
- Due-diligence support: Engage our M&A team for target-screening, valuation stress-testing, and post-deal integration playbooks that focus on membrane sourcing, aftermarket service capture, and circularity economics.
PW Consulting’s full Reverse Osmosis Water Purification Unit Market Research combines robust macro sizing, granular supplier assessment, and practical implementation tools to move from insight to action. For access to the complete dataset, segmentation matrices, and downloadable modelling assets, please refer to the published report page and contact our advisory team to arrange a tailored briefing.
For detailed analysis of this topic, please visit the official page: Reverse Osmosis Water Purification Unit Market Research
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


