



PW Consulting: Fertility ELISA Kits Market to Top USD 1,021.3M in 2026 at 6.12% CAGR

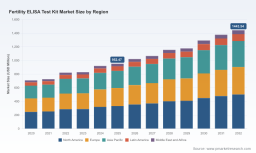
Fertility ELISA Test Kit Market — Strategic Preview for 2026 Decision-Making
As PW Consulting’s lead industry analyst, I present a focused, decision-oriented preview of our forthcoming Fertility ELISA Test Kit Market report. This briefing translates the report’s core macro findings into actionable strategic levers for executives planning investments, product strategies, regulatory programs, and go‑to‑market moves in 2026. It demonstrates the depth of our analysis while intentionally withholding the granular segment tables and model outputs that subscribers will access on the report page.
Fertility Elisa Test Kit Market
Headline market trajectory — what matters to 2026 planning
The global fertility ELISA test kit market has exhibited steady expansion through the 2020–2025 period and reached a definitive base in 2025. Our model indicates a compound annual growth rate (CAGR) of 6.12% across the 2026–2032 forecast window. Concretely, the market expanded meaningfully during the historical window and is projected to approach roughly USD 1.44 billion by 2032 — a trajectory that creates a predictable runway for mid‑sized investments, selective product launches, and consolidation plays.
Fertility Elisa Test Kit Market
Why this trajectory is strategically relevant in 2026:
Fertility Elisa Test Kit Market
- Predictability at the macro level enables multi‑year regulatory and manufacturing investments with a reasonable ROI horizon.
- Moderate growth rather than hypergrowth favors disciplined, differentiated product strategies (e.g., premium assays, service bundles, automation) rather than aggressive volume plays only.
- Stability in the base market size supports M&A transactions aimed at capability certainty (assay panels, manufacturing scale, or distribution reach) rather than pure market share capture.
Market structure and competitive intensity — concentration and opportunity
The market exhibits a mid‑level concentration: the top three players account for just under two‑fifths of market share, while the top five collectively control a little over half. This constellation creates a mixed competitive environment: established incumbents command important clinical and distribution footprints, but meaningful share remains available to specialized entrants and regional players.
Strategic implications:
- Incumbent players can leverage scale and regulatory dossiers to defend pricing and channel access; challengers must therefore rely on superior clinical differentiation, lower total cost of ownership, or targeted clinical partnerships to accelerate adoption.
- Private equity and corporate M&A strategies can be value‑accretive by acquiring niche assay portfolios or localized manufacturing to plug capability gaps for larger players seeking near‑term growth.
Competitive landscape: capabilities that determine winners
Our competitive assessment focuses on firms that demonstrate distinct assay portfolios, regulatory positioning, and commercial breadth across fertility and endocrine testing:
- Ansh Labs (Webster, TX) — Notable for immunoassay specialization and monoclonal antibody platforms applied to AMH testing. Their mix of RUO and CE‑marked products illustrates a staged regulatory commercialization approach and a clinically respected assay lineage relevant to ovarian reserve and IVF outcome assessment.
- DRG International (Springfield, NJ) — A producer of classic competitive binding and immunoassays such as estradiol and other steroid hormone tests. Their product set and assay formats make them a logical partner for labs and clinics that require validated hormone monitoring during ovulation induction and menstrual dysfunction management.
- Monobind Inc. (Lake Forest, CA) — Offers broad IVD ELISA menus including FSH, LH, prolactin, and beta‑hCG, enabling lab consolidation of assay workflows. Monobind’s IVD breadth is a strategic asset where buyers prefer a single‑vendor test menu for endocrine and reproductive panels.
- Sure Bio‑Tech (USA) — Export‑oriented supplier with compliance to GMP/ISO 13485 and CE marking; positions itself as a cost‑competitive source for routine fertility assays while emphasizing manufacturing compliance and international distribution.
Each profile above reflects technology choice (e.g., monoclonal antibody specificity vs. competitive binding formats), regulatory footprints (RUO, CE, pathways to FDA clearance), and commercial focus (specialist assay developer vs. broad IVD supplier). Our full report maps these dimensions against adoption vectors in clinics, hospitals, and diagnostic laboratories to identify realistic near‑term champions and acquisition targets.
Regulatory, quality, and reimbursement environment — constraints and accelerants
Three non‑negotiable externalities will shape winners and losers in 2026:
- Regulatory pathways: Fertility ELISA kits — especially those intended to inform clinical decisions like menopausal status or ovarian reserve — are subject to formal regulatory review (e.g., FDA clearance or de novo authorization for specified claims) and CE marking for European commercialization. The intended use claim is often the gating factor for both clinical adoption and commercial reimbursement potential.
- Quality systems: ISO 13485 compliance and GMP practice are baseline requirements for market access and large‑scale distribution; suppliers that can demonstrate robust manufacturing traceability and lot consistency command higher trust with laboratory buyers and institutional procurement teams.
- Reimbursement and coding: Fertility hormone assays typically flow through established clinical laboratory coding structures rather than a dedicated fertility ELISA code. That creates both simplicity (standard lab reimbursement processes) and complexity (lack of fertility‑specific reimbursement premiums), requiring suppliers to make compelling health‑economic and workflow arguments to justify premium pricing.
Where the practical value lies — what the full report delivers
PW Consulting’s full report is engineered as a practitioner’s toolkit for 2026 strategy execution. Subscribers will receive:
- Market sizing and validated forecast model (2020–2032) with driver‑level sensitivity and scenario outputs that allow executives to stress‑test investment cases.
- Competitive benchmarking matrix linking assay technology, regulatory status, manufacturing capacity, and commercial channels to identify defensible niches and M&A targets.
- Regulatory pathway playbooks (FDA, CE, and selected APAC pathways), including typical timelines, documentation checklists, and cost‑rate assumptions for product launches and intended‑use expansions.
- Go‑to‑market frameworks for three archetypal players — incumbent large IVD, specialty assay developer, and a scaled distributor — with tailored pricing, channel, and partnership strategies to maximize adoption in clinics and labs.
- Operational readiness assessments for scaling manufacturing (capacity planning, QC automation, raw material sourcing) and supply chain risk matrices addressing critical reagent and antibody supplier concentration.
- Investment and M&A decision tools: valuation comparables, synergy templates, and integration checklists focused on assay portfolio consolidation and cross‑selling opportunities.
To honor the “trailer” approach of this preview, we are intentionally omitting the granular segment breakdowns (by region, product type, and end‑user) and the underlying financial model that supports our forecasts. These are available with subscription to the complete report and come with an interactive model file.
Action agenda for 90 days and 12 months — prioritized moves
For executives looking to translate insight into action in 2026, prioritize the following:
- 90‑day moves: finalize regulatory gap analyses for any pipeline assays with clinical claims; initiate targeted partnership discussions with IVF clinic networks for pilot validations; perform a quick win supply‑chain audit focused on critical antibody sources.
- 12‑month initiatives: allocate budget for regulatory submissions aligned with prioritized intended uses, execute at least one channel partnership (e.g., national distributor or reference lab), and evaluate acquisition targets that deliver either complementary assay panels or manufacturing scale to compress time‑to‑market.
Concluding counsel — the competitive posture for 2026
The fertility ELISA kit market in 2026 is neither a winner‑take‑all battlefield nor a stagnant commodity patch. It is a growth market with moderate concentration, technical entry barriers, and clear regulatory gating. Firms that combine clinical differentiation (assay specificity/precision), credible regulatory strategy, and disciplined commercial execution will capture disproportionate value. Companies that treat this market as a simple volume play will face margin pressure and payer scrutiny.
PW Consulting’s complete Fertility ELISA Test Kit Market report equips leaders with the granular segmentation, model files, and execution playbooks needed to make high‑confidence decisions. For the full dataset, regional and product splits, and downloadable financial model, visit our report page — the granular intelligence there is designed to immediately inform board‑level investment deliberations and commercial operating plans for 2026.
For detailed analysis of this topic, please visit the official page: Fertility Elisa Test Kit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


