



PW Consulting: Oil & Gas Drones Market to Reach USD 103.8B by 2032 at 19.12% CAGR

Oil & Gas Drones Market — Strategic Outlook for 2026 Decision-Makers
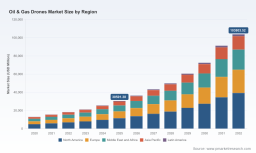
As energy companies accelerate digital transformation of field operations, unmanned aerial systems (UAS) have moved from niche pilots to enterprise-grade inspection, monitoring, and emergency-response platforms. Our latest PW Consulting market study provides the strategic intelligence executives need to make defensible investments in 2026 and beyond. At a macro level, the oil & gas drones market has transitioned from a fragmented, project-driven spend to a predictable, high-growth market: global revenue reached USD 30,501.38 Million in the report base year (2025) and is forecast to exceed USD 103,803.52 Million by 2032, reflecting a compound annual growth rate (CAGR) of 19.12% over the forecast period. Market concentration remains modest (CR3 ~22.15%, CR5 ~34.20%), underlining continued room for new entrants and differentiation.
Oil Gas Drones Market
Why this research matters for 2026 strategic choices
-
Timing is decisive: 2026 is a pivot year where regulatory clarity, maturing sensor stacks, and demonstrated ROI from early adopters converge — creating a narrow window to lock in advantageous commercial terms and operational baselines.
Oil Gas Drones Market -
Capital allocation decisions hinge on credible scenario modeling. Our study translates the market’s high-level growth path into investment scenarios tailored to asset-heavy operators, mid-tier service providers, and technology vendors.
Oil Gas Drones Market -
Procurement and vendor strategy must balance performance, supply-chain resilience, and regulatory compliance; the report gives procurement teams the framework they need to avoid “platform lock” while securing service-level guarantees.
Market trajectory and executive takeaways
The historical growth trend from 2020 through 2025 shows rapid adoption across pipeline patrols, offshore asset monitoring, leak detection, and emergency response workflows. The market scaled from documented levels in 2020 to USD 30,501.38 Million in 2025. Under our central forecast, the market expands to USD 36,361.66 Million in 2026 and accelerates through the late 2020s to cross USD 100 billion by 2032. This magnitude and speed of expansion justify treating UAS as core operational infrastructure rather than optional field technology.
From a decision-making perspective, three macro implications are immediate:
-
Shift from CapEx experiments to recurring, integrated Opex models (managed services, data subscriptions, and SLA-backed inspection contracts).
-
Prioritize platforms and sensors that enable multi-mission use; flexibility drives utilization rates and shortens payback.
-
Embed regulatory and security risk into procurement criteria — compliance capabilities materially affect deployable scope and timelines.
What the report contains — practical, operational, and commercial tools
This research is intentionally tactical. Rather than high-level forecasts alone, the report is a playbook for implementation teams and C-suite sponsors. Key deliverables include:
-
Operational playbooks for safe, compliant UAS deployment covering flight authorization, BVLOS enablement strategies, and hazardous-material handling under new guidance.
-
Procurement templates and vendor evaluation matrices that score platforms by mission fit (e.g., thermal, LiDAR, chemical/gas sensing), endure requirements, and supply-chain risks.
-
Data architecture and analytics blueprints for integrating aerial data into existing asset integrity and SCADA systems, including recommended formats, retention policies, and ML-ready pipelines.
-
Financial models (CapEx/Opex scenarios) with sensitivity analyses for utilization rates, service vs. buy decisions, and accelerated ROI pathways for scale deployments.
-
Regulatory compliance checklists and suggested lobby/engagement strategies for jurisdictions with evolving UAS rules and critical-infrastructure restrictions.
-
Actionable case studies and “lessons learned” from early enterprise rollouts — highlighting what reduced operational downtime, lowered inspection costs, and improved safety outcomes.
Competitive landscape — how vendors are positioning and what it means for buyers
The vendor ecosystem blends established UAV OEMs, specialist analytics firms, and service integrators. Each archetype brings distinct strengths and constraints that matter to 2026 buyers:
-
Platform-centric incumbents (e.g., DJI Enterprise) deliver mature multirotor systems with expansive payload ecosystems. Their advantage is end-to-end hardware availability and large install bases — attractive for rapid scaling but sensitive to supply-chain and jurisdictional restrictions.
-
Specialist manufacturers and sensor integrators (e.g., Flyability, Acecore Technologies, Microdrones) differentiate on mission-specific capabilities such as confined-space inspection robustness, modular LiDAR integration, and high-performance airframes for harsh environments.
-
Service-first players (e.g., Terra Drone, Cyberhawk Innovations) offer managed inspection programs and analytics-as-a-service, reducing up-front CapEx for operators that prefer outcome-based contracts.
-
Autonomy and software leaders (e.g., Skydio, PrecisionHawk) compete on flight autonomy, obstacle avoidance, and data-processing platforms that accelerate actionable insight generation.
-
Tactical UAS suppliers and long-endurance vendors (e.g., AeroVironment, Insitu/Boeing) are focused on remote, persistent surveillance use-cases where range and endurance trump short-range agility.
For buyers, the recommendation is to adopt a “best-of-breed assembly” approach: lock down the mission-critical payload and analytics stack, while keeping airframe selection flexible where possible. Given the current concentration ratios, partnerships and regional ecosystems will determine long-term total-cost and service quality.
Regulatory context and industry dynamics — the 2026 reality
Regulatory shifts in late 2024–2026 materially change program design and procurement windows. Notable context for 2026 planning includes:
-
PHMSA’s recent integration guidance (published April 2026) explicitly recognizes UAS for pipeline right-of-way patrols — creating operational pathways for wide-area patrol programs backed by a compliance framework.
-
FAA and PHMSA’s November 2025 guidance clarifies risk-based transport of hazardous materials by UAS, enabling new logistics and emergency-response use cases previously constrained by ambiguity.
-
U.S. contractors face restrictions (effective December 22, 2025, guidance) on using covered foreign entities on federally funded projects — an important procurement constraint that affects sourcing, warranty, and support expectations.
-
State-level rules, such as Florida’s statute restricting drone operations near critical infrastructure (2025 updates), create patchwork governance that requires tailored operational playbooks per region.
These regulatory changes are both an accelerant and a filter: they increase addressable use-cases while raising the bar for compliance, documentation, and vendor traceability. Companies that move early with compliant, auditable programs will secure competitive advantage and regulatory goodwill.
Strategic implications and five immediate actions for 2026
-
Establish a cross-functional “UAS Center of Excellence” that unites operations, HSE, legal, and procurement to standardize policies and scale capability.
-
Run a 12-month pilot portfolio that includes at least two mission archetypes (e.g., pipeline ROW patrol and offshore platform thermography) to validate operational workflows and data handoffs.
-
Implement dual-sourcing and vendor contingency clauses focused on firmware provenance, parts availability, and export/compliance constraints to mitigate supply and regulatory risk.
-
Adopt a data-first approach: require vendors to deliver ML-ready datasets and open APIs to avoid vendor lock-in and accelerate analytics maturity.
-
Translate regulatory developments into executable flight-authority maps and compliance playbooks by jurisdiction — keep these updated and use them as procurement pass/fail gates.
How to use PW Consulting’s full report
The executive brief you are reading is a strategic primer. The full PW Consulting Oil & Gas Drones Market study supplies the granular tools operational teams require to execute. Subscribers will receive:
-
Detailed segmentation across use-cases and airframe types, with proprietary scenario-based demand curves and sensitivity to sensor adoption rates (note: detailed segment tables are held in the full report to preserve proprietary modeling).
-
Vendor assessment scorecards with methodical scoring across performance, regulatory compliance, support footprint, and total cost of ownership.
-
Ready-to-use flight operations templates, procurement RFP language, and contractual clauses for warranties, data ownership, and cybersecurity obligations.
-
Customized roadmap workshops and executive briefings to convert market intelligence into a 12–36 month implementation plan aligned with your asset and regulatory footprint.
Closing — why act now
2026 represents an operational inflection point for oil & gas companies and their service ecosystems. The convergence of favorable regulation for specific applications, rapid capability advances in autonomy and sensing, and a multi-billion-dollar growth trajectory means that early, well-governed deployments yield outsized returns — operational resilience, safety improvements, and measurable cost reductions. PW Consulting’s study is designed to be immediately actionable for teams that must move from pilot to program with confidence.
For the full market segmentation, vendor scorecards, and hands-on templates that operationalize these insights, refer to the complete PW Consulting Oil & Gas Drones Market report.
For detailed analysis of this topic, please visit the official page: Oil Gas Drones Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


