



PW Consulting: Multi-Junction GaAs Solar Cells Market — 13.01% CAGR (2026–2032)

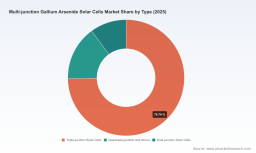
Multi-Junction Gallium Arsenide (GaAs) Solar Cells: Strategic Imperatives for 2026
Executive snapshot
As the GaAs multi-junction solar cell market accelerates toward broader commercial and space-driven adoption, 2026 becomes a defining inflection point for industrial players, investors, and satellite integrators. Our PW Consulting market model shows a robust compound annual growth rate of 13.01% across the forecast horizon, with global industry revenues expanding from a base-year level in 2025 to a materially larger market by 2032. The sector’s dynamics are shaped by technology maturation (higher cell conversion efficiencies and lightweight form-factors), concentrated supply chains, and an evolving geopolitical and trade policy environment — all of which demand decisive strategic responses this year.
Multi Junction Gallium Arsenide Solar Cells Market
Why 2026 matters: five strategic implications
-
Acceleration from niche to scale: The market has moved beyond early-adopter space projects into scaled deployments tied to LEO constellations, high-performance UAVs, and renewed interest in concentrated PV systems. This is driving predictable revenue expansion and creating new commercial structures where power-to-mass and radiation performance are premium decision variables.
Multi Junction Gallium Arsenide Solar Cells Market -
Technology is a differentiator — but so is supply security: Breakthroughs in triple- and quadruple-junction architectures, epitaxial lift‑off, and inverted metamorphic processes are improving on-orbit productivity. At the same time, primary feedstock concentration and periodic export controls are amplifying the value of procurement strategies and long-term material agreements.
Multi Junction Gallium Arsenide Solar Cells Market -
Higher market concentration creates winner-takes-most dynamics: The top-tier suppliers command a meaningful share of industry revenues, resulting in strong bargaining power for suppliers who can demonstrate flight heritage, radiation hardening, and mass-optimized solutions. This drives premium pricing for validated product lines and creates barriers for new entrants.
-
Policy and trade interventions will shape near-term sourcing decisions: National R&D programs aimed at reducing III‑V costs, combined with episodic tariff activity and short-term export policy shifts, introduce both opportunity (subsidized innovation) and risk (supply interruptions) that must be modeled into 2026 capex and procurement plans.
-
Investment timing is critical: With a clear path for multi-year revenue growth backed by a double-digit CAGR, 2026 is the year for targeted capital deployment — but only when paired with disciplined due diligence on technology roadmaps, supply continuity, and regulatory exposure.
Data-driven context you can act on
PW Consulting’s bottom-up market build reconciles historical performance (2020–2025) with scenario-based forecasts for 2026–2032. The 2025 base year anchors our model, and the outlook projects meaningful expansion through 2032 under a central scenario that reflects continued demand from satellite constellations, incremental CPV deployment, and aerospace platforms that prize power‑density improvements. Our market concentration metrics underline competitive dynamics: the three largest firms together control a significant majority of the market, and the top five firms capture an even larger share — a structural reality that shapes contracting, pricing, and partnership strategies.
Competitive landscape: profiles and strategic takeaways
-
Spectrolab Inc. (Boeing subsidiary) — With extensive flight heritage and proven high-efficiency multi-junction products for space missions, Spectrolab remains a go-to supplier for prime integrators. Strategic implication: firms seeking immediate low-technical-risk adoption should evaluate partnership and qualification pathways with legacy suppliers, while monitoring potential price premiums tied to heritage products.
-
AZUR SPACE Solar Power GmbH — A European specialist that spans space and terrestrial CPV markets and supplies major primes. Strategic implication: European OEMs and integrators will continue to favor suppliers with local certification and established relationships; non‑EU players should assess compliance and localization strategies when targeting European programs.
-
EMCORE Corporation — Recent announcements of efficiency milestones underscore the company’s technology-led position. Strategic implication: buyers and investors should track efficiency-vs-cost tradeoffs and consider staged procurement that exploits early access to higher-efficiency cells while protecting against integration risk.
-
MicroLink Devices — Focuses on lightweight, flexible cells via ELO and IMM processes. Strategic implication: platforms where mass is the binding constraint (small sats, high-end UAVs) should prioritize engagement with innovators that can demonstrate manufacturability at scale.
-
SolAero Technologies (now under Rocket Lab ownership) — Emphasizes power-to-mass performance for satellite constellations. Strategic implication: vertical integration trends (supplier-owned launches/platforms) warrant careful competitive benchmarking for both customers and investors.
-
Sharp, Alta Devices, CESI and others — These firms present varied capabilities spanning high-efficiency space cells, thin-film approaches, and qualification services. Strategic implication: a layered sourcing and qualification strategy, combining incumbents and specialists, reduces technological and supply risk.
Supply chain and raw-material risk
GaAs device economics are sensitive to III‑V feedstock availability, gallium sourcing dynamics, and specialized manufacturing equipment. China’s dominant role in primary gallium production and episodic trade policy changes can create near-term volatility that propagates through procurement and inventory strategies. Public sector initiatives (notably in the U.S.) to subsidize III‑V research and manufacturability aim to lower cost curves over time, but they do not negate the need for near-term risk mitigation.
Regulatory and geopolitical context
Policy interventions — including tariff adjustments, export control measures, and targeted R&D funding — will affect short- and medium-term decisions on where to build capacity, how to structure supply agreements, and which regions to prioritize for qualification and certification. For 2026 planning, the most actionable steps are those that combine scenario planning with contractual levers to protect continuity while preserving optionality to capture upside if trade conditions ease.
Practical 2026 playbook: where to focus capital and management attention
-
Secure material and equipment continuity: Negotiate multi-year gallium supply agreements, evaluate diversified secondary sourcing, and pre‑order long‑lead epitaxy and metallization capital equipment where strategic. Stress-test procurement against adverse trade scenarios.
-
Segmented product strategy: Define clear go-to-market paths for (a) heritage, flight‑qualified cells targeting primes; (b) high‑efficiency offerings aimed at performance‑constrained missions; and (c) lightweight/versatile cells for next‑gen smallsat and UAV programs.
-
Partner and qualify early: For integrators, start parallel qualification tracks with incumbents and innovators to avoid single‑source risk while accelerating time-to-deploy.
-
Commercial innovation: Evaluate outcome‑linked contracting (performance-per-kilogram or launched‑power-based pricing) and bundled service models (cells + panel integration + on-orbit performance guarantees) to capture premium value.
-
M&A and investment posture: Target asset-level acquisitions that add unique process IP (ELO, IMM), raw-material access, or flight-qualification records. Use staged earnouts tied to efficiency and reliability milestones.
-
Operational readiness: Invest in accelerated qualification frames, test‑laboratory expansion, and cross‑functional teams that can turn prototype efficiencies into manufactured yields without long qualification tails.
What PW Consulting’s full study delivers (high-level)
Our comprehensive report — anchored to a 2025 base and forecasting through 2032 — combines quantitative rigor with practical, transaction-ready insights. Key deliverables include:
-
A detailed market model with scenario toggles (policy, raw material shocks, adoption curves) and transparent assumptions for revenues and unit economics.
-
Supplier benchmarking and scorecards covering technology readiness, flight heritage, manufacturing capacity, and supply‑chain exposure.
-
Technology roadmaps showing achievable efficiency, mass, and cost trajectories for triple- and quadruple-junction approaches and thin‑film variants.
-
Procurement and contracting playbooks tailored to manufacturers, systems integrators, and investors, including negotiation templates for long-term feedstock contracts and manufacturing equipment procurement.
-
Risk matrices and stress-tests covering raw-material concentration, tariff scenarios, export controls, and geopolitical shocks.
-
An M&A shortlist and integration checklist calibrated for 2026‑specific opportunities, plus a 100‑day implementation plan for acquirers or strategic partners.
Final counsel for decision-makers in 2026
With a structurally growing market, demonstrable technology advances, and concentrated supply power centered among a few established vendors, 2026 will reward organizations that combine disciplined capital allocation with proactive supply-chain strategies and accelerated product qualification. Short-term protection against raw-material and trade volatility must be balanced with strategic investments that secure differentiated product performance. Whether you are a systems integrator preparing to scale a constellation, a supplier deciding on capacity expansion, or an investor sizing acquisition targets, the right mix of tactical procurement and strategic partnerships this year will materially influence market position across the forecast horizon.
Next steps
PW Consulting’s full Multi-Junction GaAs Solar Cells Market report provides the granular segmentation, supplier-level benchmarking, and scenario models needed to operationalize the recommendations above. To access the complete dataset and bespoke advisory options, contact PW Consulting’s Industry Team for a briefing and tailored engagement plan.
For detailed analysis of this topic, please visit the official page: Multi Junction Gallium Arsenide Solar Cells Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


