



PW Consulting: Integral Total Station Market Reaches USD 1,956.6M in 2025 (2020–2025)

Integral Total Station Historic Market: Strategic Briefing for 2026 Decision-Makers
Executive snapshot
Between 2020 and 2025 the integral total station market expanded from a lower‑mid single‑billion scale to an estimated USD 1.96 billion (base year 2025), reflecting steady demand across surveying, construction, mining and related infrastructure sectors. Our forward view anticipates continued expansion through the 2026–2032 forecast window at a compound annual growth rate of 6.75%, bringing the market to roughly USD 3.09 billion by 2032. These headline figures signal a maturing market where product differentiation, workflow integration and service economics will increasingly determine winners and losers.
Integral Total Station Historic Market
Why this study matters for 2026 strategy
For executives planning capital allocation, product roadmaps, M&A, or go‑to‑market pivoting in 2026, the arithmetic above is only the starting point. What matters is how that growth is being captured—and by whom. Our Integral Total Station Historic Market research turns the macro trajectory into operational levers: which technology shifts compress total cost of ownership, where aftermarket and software monetization deliver margin uplift, how supply‑chain pinch points erode delivery certainty, and what competitive moves compress incumbent advantage. In short, the study translates a market growth rate into actionable scenarios that inform 12–36 month decisions.
Integral Total Station Historic Market
Scope and practical outputs of the report
- Validated historical time series (2020–2025) and a transparent forecast model (2026–2032) with sensitivity scenarios for low/high capital‑spend and supply‑chain stress.
- Competitive benchmarking across product categories and business models: feature parity tables, pricing band analysis, and aftermarket revenue estimates.
- Service and deployment playbooks for OEMs, system integrators and large users—covering field service, theft/security economics, software subscription design, and training/enablement.
- Supply‑chain risk map: critical component sourcing, single‑supplier exposures, and mitigation options including alternative sourcing, component redesign and buffer inventories.
- Regulatory and standards checklist to align product calibration, certification and project compliance with ISO and ALTA/NSPS requirements.
- M&A and partnership scorecards highlighting integration risk, revenue capture potential and estimated payback timelines under multiple synergies assumptions.
Competitive landscape: structure and strategic implications
The market reveals a clear oligopolistic tendency: the top three vendors account for a dominant share, and the top five consolidate an even greater portion of market value. Measured concentration (CR3 and CR5) indicates that leadership is not marginal; it is structural. This concentration creates both barriers and vulnerabilities—barriers to new entrants at scale, but vulnerabilities for incumbents exposed to rapid technological shifts or service disruptions.
Integral Total Station Historic Market
Leading incumbents combine hardware excellence with adjacent software and services. Examples of recent strategic activity illustrate the evolution:
- Leica Geosystems (Hexagon) has doubled down on device security and cloud services—introducing an integrated theft‑deterrence/security offering for high‑value robotic stations and rolling out a cloud‑based data management platform for real‑time access and analysis. These moves are defensive (protect high‑value assets) and offensive (monetize data flows).
- Trimble has continued product innovation on robotic stations, prioritizing automation and improved on‑device processing to shrink field workflows and cut post‑processing effort.
- Topcon’s collaboration with construction contractors points to a channel strategy that embeds instruments into project delivery rather than treating them as one‑off capital buys.
From a strategic lens, these behaviors highlight two winning axes: (1) verticalization—expanding from instruments to workflow/platform offerings that lock customers into recurring revenue, and (2) integration—with construction and engineering firms to secure volume through project‑level partnerships.
Technology, supply chain and standards dynamics
Three technical and operational trends are shaping near‑term competitive advantage:
- Sensor and component dynamics: critical sensors (optical, image and pressure sensors used in EDM and angle measurement) experienced moderate price pressure and episodic tight supply in 2025. For OEMs this translated into either margin compression or delayed deliveries—depending on inventory and procurement agility.
- Software and data services: cloud‑enabled device management, security functions (asset locating/theft deterrence) and integrated analytics are moving from premium differentiators to expected features for professional users. Firms that convert device telemetry into actionable project insights can extract higher aftermarket value.
- Standards and compliance: adherence to ISO calibration protocols and project accuracy frameworks (including ALTA/NSPS requirements) is increasingly non‑negotiable for large infrastructure customers. Compliance becomes a commercial enabler when embedded into sales and warranty offerings.
Strategic playbook for 2026
Below are pragmatic options for different player types—each aligned to the market backdrop and near‑term operational realities:
- For OEMs with scale: accelerate platformization—bundle device, cloud management and security into subscription tiers; prioritize aftermarket service networks to increase lifetime value; shore up component sourcing via strategic supplier agreements and dual‑sourcing for critical sensors.
- For mid‑tier and niche vendors: find white‑space in vertical workflows (e.g., mining, utilities) by co‑developing process‑specific modules; pursue cost‑leadership in manual station segments with focused field‑durability claims and local service partnerships.
- For large contractors and surveyors: shift procurement strategy from CAPEX to blended CAPEX/OPEX—leverage managed‑service contracts to gain predictable refresh cycles and faster access to advanced features; insist on cloud‑enabled device telemetry to measure productivity gains.
- For private equity and corporate development teams: prioritize roll‑up targets that strengthen aftermarket service capability or add software monetization, and stress‑test valuation assumptions against scenarios where component scarcity adds 6–12 month lead times for new product ramps.
Decision frameworks and KPIs to track in 2026
We recommend four KPIs to convert market insight into measurable outcomes:
- Installed base monetization rate: percentage of devices on active cloud/service subscriptions.
- Aftermarket revenue per installed device—leading indicator of service economics and customer stickiness.
- Time‑to‑fulfilment for new device orders—sensitive to sensor supply and critical for time‑bound infrastructure contracts.
- Compliance readiness score—measure of organizational alignment to ISO/ALTA calibration and reporting obligations.
Use cases: how clients have applied this research
Recent applications of our analysis include:
- An OEM reworked its pricing architecture and introduced a three‑tier subscription model anchored to device telemetry—expected to raise recurring revenue share by mid‑2027.
- A construction conglomerate redesigned procurement to prefer managed instrument fleets, reducing on‑site instrument loss and improving field productivity—supporting faster project close‑outs.
- An investor adjusted acquisition timing for a target firm after modelling lead‑time exposure for critical sensors, avoiding an overpay in a stressed supply scenario.
What this briefing does not disclose—and why that matters
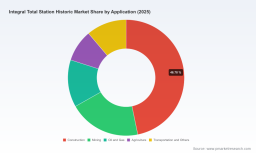
To preserve actionable advantage for clients and to respect the commercial sensitivity of primary‑level segmentation, this preview intentionally omits granular subsegment breakdowns (regional/application splits and product‑level revenues). These are central to tactical decisions—pricing by region, SKU rationalization, and M&A valuation—and are available in the full Integral Total Station Historic Market report. The objective here is to demonstrate analytical depth and to show how headline growth translates into strategic choices, while directing practitioners to the full dataset and modelling toolbox for execution.
Immediate next steps for executives (90‑day plan)
- Run a short‑form stress test of your supply chain for critical sensors—identify single points of failure and evaluate buffer or dual‑sourcing options.
- Audit installed devices for telemetry capability and design a pilot subscription offer—measure uptake and churn after a single project cycle.
- Map competitive moves in your served geographies—prioritize defensive feature development (security, cloud sync) where incumbents are scaling platform offers.
- Engage with PW Consulting for the full dataset and scenario model to quantify the revenue and margin impact of each action above.
Concluding perspective
The integral total station market is no longer just a hardware business; it is becoming a workflow and data business with hardware as the anchor. Growth is solid, predictable and visible at the macro level, but the real value accrues to organizations that can convert instrument sales into sustained service streams, manage supplier risk effectively, and align with customers’ project delivery models. Our full market study equips leaders with the granular segmentation, scenario models and commercial playbooks needed to convert the 6.75% CAGR and the roughly USD 3.09 billion terminal market opportunity into concrete, defensible revenue and margin outcomes.
For access to the complete data tables, segment‑level forecasts, company scorecards and the full strategic toolkit, consult the Integral Total Station Historic Market report on PW Consulting’s publication portal.
For detailed analysis of this topic, please visit the official page: Integral Total Station Historic Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


