



PW Consulting: Acquired Immunodeficiency Syndrome Market — 5.42% CAGR to 2032

Acquired Immunodeficiency Syndrome Market — 2026 Strategic Preview
Executive snapshot
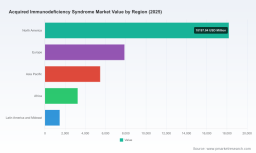
PW Consulting’s latest market study uses a 2025 base year and spans historical analysis (2020–2025) with detailed forecasts through 2032. At the macro level, the global AIDS market stands at approximately USD 36,250 Million in 2025 and is projected to expand to roughly USD 38,946 Million in 2026, continuing to grow to an anticipated market size in excess of USD 52 Billion by 2032. This trajectory represents a mid-single-digit compound annual growth rate (CAGR) across the forecast window — a rate that underpins both steady baseline demand for antiretrovirals and material upside from structural shifts in product modality, pricing and access.
Acquired Immunodeficiency Syndrome Market
Why 2026 matters for corporate decision‑makers
-
Inflection of treatment modalities: 2024–2026 is the period when long-acting injectables and novel combination regimens move from early adoption to mainstream commercialization in high-income and middle-income markets. Several regulatory approvals and late‑stage clinical reads in early 2026 materially change choice architecture for physicians, payers and procurement agencies.
Acquired Immunodeficiency Syndrome Market -
Rapid movement on access and pricing: public‑private partnerships and voluntary licensing agreements announced in 2025–2026 create clear roadmaps for generic supply into low‑ and middle‑income countries, changing demand timing and pricing elasticity across procurement cohorts.
Acquired Immunodeficiency Syndrome Market -
Policy and coverage consolidation: near‑universal adoption of “treat all” policies and expanding viral suppression targets are shifting procurement volumes and the unit economics of novel prevention products, making 2026 the year strategic investments in market access and supply chain scale either pay off or materially underperform.
What this report delivers — practical, transaction‑ready intelligence
The study is built to inform boardroom decisions and commercial execution plans in 2026. Key deliverables include:
-
Top‑down market sizing and forecast model (2026–2032) with scenario‑switching capability for alternate adoption, price and access assumptions.
-
Clinical pipeline and modality impact analysis — assessing likely uptake curves for long‑acting injectables, novel oral regimens, and once‑weekly/bi‑annual prevention approaches.
-
Payer and procurement playbooks covering tender dynamics, price‑volume thresholds, and contractual structures that optimize realization in public and private channels.
-
Commercial go‑to‑market roadmaps for innovators and generics, including segmentation of revenue pools by channel, optimized salesforce deployment, and digital distribution strategies.
-
Supply‑chain and manufacturing readiness assessment with COGS levers, scale‑up timelines, and contingency plans for API constraints and regulatory releases.
-
Regulatory and policy risk matrix, including likely approval timelines, compulsory licensing exposure, and donor funding sensitivity analysis.
-
Deal and M&A playbook: valuation benchmarks, partnership structures, and integration priorities tailored to both originators and generic manufacturers.
-
Interactive appendices: country‑level forecasts, pricing sensitivity tables, and downloadable financial models for scenario work by commercial teams.
Competitive landscape — who matters and why
The industry environment is bifurcating: a small set of originator companies continue to command premium positioning through differentiated single‑tablet regimens and long‑acting modalities, while a broad base of generics concentrates on volume supply and low‑cost procurement channels. Competitive dynamics in 2026 are driven by product modality leadership, licensing partnerships, and the ability to stitch commercial and public health strategies together at scale.
-
Gilead Sciences — continues to anchor commercial leadership through established single‑tablet regimens and first‑mover positioning in twice‑yearly injectable PrEP. Their late‑stage clinical data and access partnerships with generics materially shape price and availability timelines globally. Strategic watchers should track Gilead’s combination programs and their sequencing strategy for innovative regimens versus discounting to public channels.
-
ViiV Healthcare — remains the specialist HIV player with a depth of long‑acting clinical know‑how; its portfolio of injectables and INSTI‑based regimens provides a compelling alternative for both treatment and prevention. ViiV’s advantage is focused product stack and strong relationships with HIV treatment programs.
-
Merck & Co. — the regulatory approval of new oral regimens in 2026 expands the competitive set for switch strategies in virologically suppressed patients. Collaborations with other innovators on once‑weekly approaches make the company an important alliance partner and potential disruptor in regimen economics.
-
Large pharma (J&J/Janssen, BMS, AbbVie, Boehringer, Roche) — these incumbents maintain niche clinical assets (notably protease and NNRTI classes) and diagnostic linkages that are strategically valuable in integrated care pathways and differentiated reimbursement negotiations.
-
Generics and specialty producers (Cipla, Viatris, Teva, Aurobindo, Dr. Reddy’s, Hetero, Emcure) — the generics cohort is executing on both procurement supply and technology transfer deals that will accelerate price erosion in public tenders. Their role in manufacturing scalable, low‑cost versions — and in some cases, generic launches of novel molecules on agreed licensing terms — will be decisive for market share in LMICs.
Recent developments that alter competitive calculus
-
Regulatory and clinical milestones in early 2026 have expanded the set of commercially viable regimens, reducing single‑product dependency for payers and raising the bar for differentiated clinical value.
-
Access partnerships announced in 2025–2026 — including voluntary licensing and low‑price arrangements for prevention products — materially change procurement cost curves for public buyers beginning in 2027, forcing originators to refine dual‑track commercial models.
-
Public‑health adoption of WHO‑preferred regimens and widespread “treat all” policies have stabilized baseline demand, while unmet prevention needs keep upside open for high‑efficacy, low‑touch products.
Strategic Imperatives for 2026 — a prioritized to‑do list
-
Reassess portfolio mix against modality risk: prioritize investment in modalities expected to reach scale in the next 24 months (e.g., long‑acting injectables) while rationalizing marginal line extensions.
-
Lock in supply and licensing partnerships early: secure API capacity and voluntary licensing agreements to protect margins against accelerated generic entry in LMIC tenders.
-
Design differentiated reimbursement value propositions: develop outcome‑and‑adherence based contracting pilots with major payers and donors.
-
Stress‑test commercial models with procurement scenarios: model price thresholds, tender timing and mix shifts between hospital, retail and online channels to quantify revenue risk.
-
Operationalize a rapid regulatory playbook: align global regulatory filings with country rollout plans to avoid mismatches between label availability and distribution contracts.
-
Prioritize M&A and alliance targets that fill short‑term capability gaps — e.g., manufacturing scale, long‑acting formulation expertise, or country distribution networks.
-
Invest in demand generation and provider education for new modalities to accelerate uptake and justify premium pricing where clinical differentiation exists.
Risks to monitor (the 18‑month watchlist)
-
Accelerated generic entry and aggressive public procurement pricing in LMICs that compress margins for originators.
-
Regulatory delays or unexpected safety signals for novel modalities that could slow adoption.
-
Donor funding volatility and shifting priorities within major buyers that reallocate volumes between prevention and treatment programs.
-
Manufacturing or API bottlenecks that impede scale‑up for injectable programs tied to inflexible dosing schedules.
Why PW Consulting’s 2026 market study is uniquely valuable
This research is constructed to move beyond descriptive market commentary and into immediately usable strategy. It combines a transparent top‑down forecast (with a 2025 base and 2026–2032 scenarios), granular commercial playbooks, and an interactive model that allows teams to stress‑test pricing, access, and uptake assumptions. The study integrates clinical milestone timelines, supplier readiness assessments, and procurement dynamics so that commercial, access and R&D leaders can prioritize investments with confidence.
Next steps — the trailer
We have presented the strategic contours and highlighted the disruptors, but the full decision‑grade intelligence — including country‑level forecasts, price‑volume matrices, channel revenue splits, and the downloadable scenario model — is intentionally reserved for the complete report and accompanying data pack. For teams preparing budgets, alliance strategies or M&A diligence in 2026, securing the full dataset and model will materially shorten time‑to‑decision and improve outcome predictability.
Contact PW Consulting to access the complete Acquired Immunodeficiency Syndrome Market study, the interactive forecast model, and a tailored briefing that prioritizes the actions your executive team must take before the close of 2026.
For detailed analysis of this topic, please visit the official page: Acquired Immunodeficiency Syndrome Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


