



Si OLED Microdisplay Market Poised for 29.85% CAGR Through 2032 — PW Consulting

Si‑OLED Microdisplay Market — Strategic Imperatives for 2026
Executive snapshot
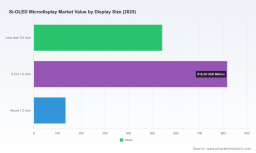
The silicon‑backed OLED (Si‑OLED or OLEDoS) microdisplay market has moved from a niche specialist domain into a verified commercial growth story. Our analysis shows the market expanding from roughly USD 345.5 million in 2020 to about USD 1,492.5 million in 2025, with an accelerated trajectory at the start of the forecast window. PW Consulting projects the market to reach approximately USD 1,930.6 million in 2026 and to exceed USD 9.2 billion by 2032, reflecting an aggressive compound annual growth rate of roughly 29.85% across the 2026–2032 forecast period. For leadership teams planning 2026 strategy, this combination of rapid revenue expansion and concentrated supplier capabilities creates a narrow window for decisive action: scale when clarity exists, but hedge while the value chain reconfigures.
Si Oled Microdisplay Market
Why this research matters for 2026 decision-makers
- Timing of capacity commitments: With demand forecasts steepening in 2026, capital decisions made this year will determine who benefits from the next wave of AR/VR, enterprise, and defense contracts. Mistimed investment risks either costly idle capacity or missed market share.
- Product differentiation strategy: Resolution, brightness, contrast, power efficiency and silicon backplane expertise are the primary levers. Prioritizing one axis (e.g., ultra‑high resolution for enterprise AR) over another (e.g., extreme brightness for head‑mounted optics in defense) will shape design-in success.
- Supply chain resilience: Si‑OLED blends semiconductor CMOS processes with OLED materials and optics. Firms that map and secure critical upstream inputs and partner for optical engines will reduce time‑to‑market and failure risk.
- Commercial route options: The market rewards OEM partnerships, module integrators, vertical integration and licensing — simultaneously. Choosing which route to scale in 2026 will influence margins and exit options by 2028.
Demand and technology dynamics shaping 2026 choices
Si‑OLED microdisplays are winning design cycles because they deliver pixel densities and compact footprints that incumbent panel technologies struggle to match. The convergence of high‑resolution silicon backplanes (fabricated with standard CMOS processes) and OLED emissive layers enables near‑eye systems that meet the twin constraints of optical throughput and device ergonomics. Two tangible technology vectors accelerating adoption are peak luminance (to enable bright outdoor or high-dynamic-range near‑eye experiences) and energy efficiency (to extend untethered battery life). Recent R&D milestones from research institutions attest to both extremes: prototypes pushing multi‑megacandela luminance in monochrome microdisplays for specialized optics, and alternative driving schemes that update only required pixels for significantly reduced power draw.
Si Oled Microdisplay Market
On the demand side, the classic consumer AR/VR use case is now complemented by robust enterprise, industrial and defense pull. Near‑term procurement cycles and public sector programs are increasing the addressable market for high‑performance Si‑OLED modules, while consumer AR roadmaps are beginning to incorporate silicon‑backed solutions where pixel density and compact optics are decisive.
Si Oled Microdisplay Market
Competitive landscape — players and strategic postures
The competitive field combines established semiconductor and display incumbents, defense‑oriented specialists, and fast‑scaling pure‑plays. Each cohort presents different advantages and trade‑offs for partners, customers and investors:
- Sony Semiconductor Solutions Corporation: Leverages deep CMOS and imaging expertise to offer high‑resolution, high‑brightness Si‑OLED SKUs and scale manufacturing. Their product releases have set benchmarks in pixel density and luminance for AR/VR optical engines.
- eMagin Corporation: U.S.‑based, with cleanroom production and a history of delivering rugged, high‑brightness microdisplays for defense and industrial customers. Their compliance posture and defense pedigree make them a preferred partner where export controls and certifications are decisive.
- SeeYA Technology (Seeya Technology): A pure‑play OLEDoS manufacturer that has moved from development to mass production and public financing, indicating capital to expand silicon‑OLED capacity and R&D. Their growth trajectory exemplifies how focused players can scale rapidly with the right financing and domestic market support.
- Kopin Corporation: A diversified microdisplay supplier with a long trail of fielded defense solutions and customizable offerings for enterprise and healthcare applications.
- BOE, Seiko Epson, MICROOLED, OLiGHTEK, OLEDWorks: These firms represent a mix of large panel manufacturers, optics‑engineers and niche specialists that can serve both module‑level integration and OEM partnerships. Their combined presence increases options for buyers but also raises the bar on performance and integration capabilities.
Across the competitive field, leadership currently concentrates among a few suppliers with the manufacturing scale, IP breadth and customer access to influence component pricing and qualification timelines. New entrants with strong IP or a focused go‑to‑market strategy can still displace incumbent positions, particularly where they solve a specific optical or thermal constraint.
Recent industry signals that matter for 2026 planning
- Market entrants leveraging public capital to accelerate fabs and R&D highlight the importance of watching financing cycles and capacity additions in 2026.
- Prototype breakthroughs from research institutes that demonstrate high pixel density and novel low‑power driving schemes suggest potential step changes in product architectures over the next 12–24 months.
- Large program awards and defense procurements for OLED‑based head‑mounted displays (including fighter jet programs) indicate a growing, defense‑grade addressable market that will be subject to export controls, certification timelines and long lead procurement cycles.
What the PW Consulting Si‑OLED Microdisplay report delivers (operationally actionable)
Our full study is structured for executives who need to convert market intelligence into executable plans. Highlights include:
- A validated demand model with base‑year calibration (2020–2025) and scenario forecasts to 2032 that isolate near‑term (2026–2028) inflection points and long‑run market sizing.
- Supplier and capability maps that align manufacturing process risks (CMOS fab dependencies, OLED materials sourcing, optics assembly) with typical qualification timelines.
- Decision frameworks for CapEx vs. outsourcing, including a timing matrix that shows break‑even windows for greenfield fabs, capacity leases and strategic JV models.
- Commercial playbooks for OEMs: preferred procurement models, price/volume negotiation levers, and channel strategies (module integrator vs. direct supply).
- Technology roadmaps and R&D investment prioritization guides that link pixel architecture choices to end‑use P&L outcomes (e.g., AR enterprise adoption rates or defense specifications).
- Regulatory and export control impact analysis, plus practical mitigation strategies for defense‑sensitive supply chains.
Note: To preserve client value, the report summarizes segmentation outcomes and competitive positioning in high resolution. This article intentionally omits the granular regional, application and size‑band splits that are available in the gated report and data annex.
Immediate recommendations for 2026 (concise playbook)
- Prioritize flexible capacity commitments: favor scalable production lines or partnerships that allow output to step up as design wins convert into orders.
- Lock critical upstream inputs (CMOS wafer access, OLED materials, specialized optics) with multi‑year contracts or dual‑sourced suppliers to minimize single‑point failures.
- Invest in one clear product differentiator early — either resolution/pixel technology or ultralow‑power driving schemes — and position marketing and BD resources around that capability.
- Engage defense procurement teams early if pursuing military opportunities: build ITAR/compliance capabilities and plan for extended qualification cycles and lifecycle support commitments.
- Consider targeted M&A or JV activity for gaps in optics, packaging or silicon expertise rather than broad vertical integration unless a clear ROI case exists.
- Enable modular designs in product roadmaps to work across multiple optical engines and to accelerate design wins across enterprise and consumer variants.
How PW Consulting’s research de‑risks executive choices in 2026
Our methodology combines primary interviews with OEMs, tier‑1 integrators, and fab partners, triangulated with transaction and financing data, product roadmaps from leading suppliers, and bottom‑up engineering cost models. The result is a defensible, scenario‑based guide that translates market size and growth into concrete operational decisions: who to partner with, when to invest in capacity, and what performance metrics to prioritize to capture the most valuable design‑in opportunities.
Next steps
For executives preparing 2026 strategic plans — whether your focus is manufacturing scale, product roadmaps, channel strategy, or M&A — our Si‑OLED Microdisplay Market report provides the templates and data required to choose with conviction. The full report contains the detailed regional, application and display‑size splits, supplier scorecards, and downloadable model files referenced here. To obtain the comprehensive dataset, methodology appendix and executive workshops, please visit our report page or contact PW Consulting’s microdisplay practice for a briefing.
For detailed analysis of this topic, please visit the official page: Si Oled Microdisplay Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


