



PW Consulting: Corn Germ Meal Market Poised for 4.52% CAGR (2026–2032)

Corn Germ Meal Market: Strategic Imperatives for 2026
Executive snapshot
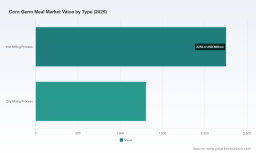
The corn germ meal market has entered a phase of steady, investment-grade expansion. Our PW Consulting analysis finds the global market reached approximately USD 3,558 million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of roughly 4.52% through the 2026–2032 forecast period. By the end of that horizon the market is expected to approach the mid-single‑billion mark, reflecting a combination of demand-side diversification in livestock nutrition, incremental capacity additions at wet‑milling complexes, and ongoing regulatory and quality assurance investments across feed value chains.
Corn Germ Meal Market
Why this matters for 2026 decision cycles
-
Timing: 2026 is a pivotal year for capital allocation and contract strategy. With measured growth rather than explosive expansion, corporates can choose between capacity-led plays (brownfield expansions or debottlenecking) and higher-margin product innovation without fear of immediate overcapacity.
Corn Germ Meal Market -
Margin pressure management: Feed manufacturers and integrated processors will need to balance feedstock price volatility with premiumization opportunities tied to certified, traceable germ meal products.
Corn Germ Meal Market -
Regulatory and quality risk: Ongoing certification regimes and monthly production transparency (as captured by public agencies) raise the bar on traceability and testing—factors that materially affect commercial terms in 2026 sourcing contracts.
Market trajectory and structural takeaways
The market’s steady CAGR masks a set of structural dynamics worth noting. Growth is being driven by evolving inclusion strategies in ruminant, swine and poultry diets—where corn germ meal functions as a medium‑protein, higher‑energy co‑product—and by modest but strategic capacity investments from established wet‑milling operators. At the same time, market concentration remains moderate: the sector is not controlled by a handful of dominant players to the degree seen in some agricultural inputs, but scale and integration advantages do accrue to large processors, creating attractive entry points for midsized specialists and contract suppliers.
Demand drivers and nutritional dynamics
-
Nutritional role: Corn germ meal’s profile—valued fat content from the germ and useful protein levels—enables feed formulators to substitute portions of conventional protein sources under certain feeding programs. This creates cost‑management options for integrators, especially where soybean meal and other proteins face price or availability stress.
-
Ration engineering: Practical inclusion rates and performance outcomes vary by species and growth stage. For example, ruminant formulations capitalize on the energy contribution of germ meal, while swine diets can push inclusion in growing‑finishing rations to capture the germ’s fat advantage. In broilers, substitution strategies have been demonstrated that maintain average daily gain and feed conversion ratios within competitive bands when germ meal replaces a modest share of soybean meal.
-
Product segmentation: Manufacturers that can offer differentiated, certified germ meal—low mycotoxin, pesticide‑screened, GMP+ verified and traceable—command premiums and preferential placement in quality‑sensitive supply chains (e.g., large integrators, export channels, and high‑value aquaculture feeders).
Supply side: capacity, logistics and feedstock policy
Wet‑milling operators remain the backbone of corn germ meal supply. Recent capacity moves—such as announced increases in germ extraction and meal output at major wet‑milling facilities—signal deliberate capacity scaling rather than speculative build‑outs. These targeted expansions improve extraction yields and offer procurement stability, but they also require logistics and storage upgrades to capture margins on higher‑fat co‑products.
On the policy front, long‑standing agricultural supports and biofuel mandates that underpin corn economics continue to influence raw material dynamics. Firms that model procurement with explicit scenarios for policy shifts (e.g., changes to renewable fuel standards or subsidy structures) will have an advantage in negotiating multi‑year contracts and hedging feedstock exposure.
Quality, safety and certification as commercial levers
Market participants increasingly treat feed safety certifications not as compliance overhead but as commercial differentiators. GMP+ certification and rigorous monitoring for mycotoxins, heavy metals and pesticide residues have moved from “nice to have” to “commercial must‑have” for suppliers targeting institutional buyers. Suppliers that invest in rapid testing, third‑party certification and digital traceability unlock premium channels and reduce buyer due‑diligence friction.
Competitive landscape: who matters and why
The industry mix includes global agribusiness integrators, regional wet‑milling specialists, and a cadre of processors focused on ingredient portfolios. Key players maintain different strategic postures:
-
Archer Daniels Midland Company (ADM): A major wet‑milling operator with integrated facilities and a focus on capturing co‑product value through scale and downstream marketing. Recent capacity uplift at its mid‑west facility underscores a disciplined approach to expanding extraction efficiency.
-
Cargill, Incorporated: Leverages global origination and logistics to serve both commodity and value‑added feed segments, using integration to offer stable supply agreements to large livestock integrators.
-
Bunge Limited: Focuses on integrated processing economics, delivering germ meal alongside oil extraction streams—its strategic focus is on capturing margin across extraction and co‑product channels.
-
Ingredion Incorporated and Tate & Lyle PLC: These firms exploit ingredient R&D and application knowledge to position germ meal within broader ingredient solutions, serving food and feed markets with differentiated product claims.
-
Roquette Frères, Grain Processing Corporation and AGRANA: Regional specialists that blend local market intimacy with wet‑milling know‑how, often providing tailored solutions for nearby feed industries.
-
Jungbunzlauer Suisse AG and select Asian players (including major Chinese processors and Indian producers): Focus on certified, GMP+ supply and regional feed demand—their role is crucial in quality‑sensitive and fast‑growing regional markets.
Collectively, these players demonstrate a mix of scale, certification focus, and regional specialization—creating a landscape in which partnerships, tolling arrangements and offtake contracts are common strategic responses.
Recent developments and what they signal for buyers and investors
-
Capacity adjustments by large wet‑mill operators suggest measured supply growth that preserves near‑term pricing discipline while improving feedstock utilization.
-
Monthly tracking of production by public agencies increases transparency for buyers and enables more accurate short‑term procurement planning and inventory optimization.
-
Certification maintenance by producers highlights the market premium for secure, tested supply—an important consideration for enterprises prioritizing product safety and export compliance.
Strategic imperatives for 2026
-
Secure flexible supply through a mix of short‑term and multi‑year contracts. Use indexing clauses that incorporate feedstock cost drivers and quality thresholds to share risk sensibly with suppliers.
-
Prioritize certified suppliers and invest in inbound testing and traceability. A relatively small CAPEX for rapid on‑site testing and digital supply chain provenance can unlock pricing premiums and reduce disruption risk.
-
Explore product premiumization: develop germ‑meal blends or treated co‑products that target performance improvements in key species; partner with ingredient specialists for formulation R&D.
-
Consider strategic partnerships with wet‑milling operators for tolling or offtake to secure volumes without full asset exposure—particularly attractive where processors are expanding extraction capacity in measured increments.
-
Model policy risk explicitly. Scenario planning for shifts in renewable fuel policy or subsidy regimes will improve procurement resilience and capex prioritization.
-
Scan for consolidation targets. Moderate market concentration creates windows for bolt‑on acquisitions that can rapidly improve geographic reach or certified supply capacity.
What PW Consulting’s full report delivers
Our full Corn Germ Meal Market study provides a hands‑on toolkit for executives making 2026 decisions: detailed demand modeling, supplier scorecards, unit economics for extraction and blending, procurement contract templates, certification and testing checklists, scenario‑based price sensitivity analyses, and an actionable M&A playbook targeted at both strategic and financial buyers. The report combines quantitative forecasts with qualitative supplier interviews and supply‑chain stress tests designed to translate market intelligence into executable initiatives in the coming 12–24 months.
How to use this analysis today
-
Feed manufacturers: prioritize supplier audits and integrate germ meal testing into inbound QC protocols.
-
Processors: evaluate debottleneck projects that lift extraction yields and fit within mid‑cycle demand increases; consider commercial pilots for value‑added germ meal streams.
-
Investors and acquirers: use concentration metrics and regional capacity moves to identify consolidation targets and partnership opportunities that enhance certified supply footprints.
Next steps
This overview is designed as a strategic preview—showing the contours and choices that will matter most in 2026. For the detailed datasets, regional and application breakdowns, supplier benchmarking, and the full suite of practical templates, please consult the complete PW Consulting report and accompanying data dashboards. The full package contains the granular insights and segment‑level intelligence that operational teams need to convert strategy into measurable outcomes.
For detailed analysis of this topic, please visit the official page: Corn Germ Meal Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


