



PW Consulting: Environmental Risk Management Market Set for 8.52% CAGR (2026–2032)

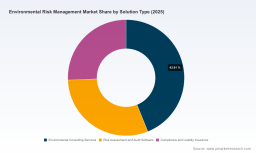
Environmental Risk Management Market: Strategic Imperatives for 2026
As companies enter 2026, environmental risk management (ENRM) has moved from a compliance checkbox to a board-level strategic agenda item. Our latest PW Consulting market study synthesizes five years of historical dynamics (2020–2025) and a forward-looking forecast (2026–2032) to give executives the evidence base they need to make high-consequence decisions. The market has expanded materially—from roughly USD 3,650 million in 2020 to about USD 5,440 million in 2025—and our modeling projects continued expansion to nearly USD 9,641 million by 2032, implying a robust compound annual growth rate (CAGR) of 8.52% through the forecast horizon. This trajectory signals persistent demand for services and technologies that can identify, quantify, mitigate, and transfer environmental risk across value chains.
Environmental Risk Management Market
Why this study matters for 2026 decisions
Three pragmatic realities make the timing critical:
Environmental Risk Management Market
- Regulatory acceleration: The publication of ISO 14001:2026 reframes environmental risk management to include explicit requirements on climate change, biodiversity, and supply chain oversight. With a transition window extending through 2029, organizations must act now to avoid scramble and reputational risk in the final certification phase.
- Investor and governance pressure: Market intelligence and investor surveys indicate overwhelming adoption of formal ENRM governance by asset managers and institutional investors. C-suite teams are being asked to demonstrate not only policy alignment but measurable risk-reduction and value-protection outcomes.
- Market dynamism and fragmentation: Despite the presence of global leaders, concentration metrics remain low (CR3 ~21.9%; CR5 ~34.1%), signifying a market that is both competitive and ripe for strategic consolidation, vertical integration, and specialization.
Strategic implications for corporate leaders
Executives who treat ENRM as a cross-functional strategic program—as opposed to an episodic compliance exercise—will gain advantage in operational resilience, access to capital, and long-term cost avoidance. Practical implications include:
Environmental Risk Management Market
- Board oversight: Elevate ENRM into board-level risk registers and audit cycles. ISO 14001:2026 embeds this expectation; auditors and stakeholders will scrutinize governance, not just technical remediation plans.
- Supply chain scrutiny: The new standard requires a broader contextual assessment. Companies must expand supplier due diligence and embed environmental clauses into procurement and contracting strategies.
- Insurance and liability: Environmental insurance markets are evolving. Decision-makers should use integrated models to balance capital expenditure on mitigation versus premiums and indemnity strategies informed by current insurance forecasts.
- Data and digitalification: Investment in risk-assessment and audit software, remote sensing, and AI-enabled analytics will accelerate value capture—both by reducing incident response time and by enabling proactive scenario stress-testing.
What the PW Consulting study delivers
Our report is designed as an operational toolkit for leaders, combining strategic context with executable deliverables. Key components include:
- Market sizing and high-resolution forecasting: A transparent model covering historical (2020–2025) and forecast (2026–2032) trajectories, including sensitivity scenarios for regulatory shock, accelerated climate impacts, and technology adoption.
- Regulatory dynamics and compliance roadmaps: A practical transition framework for ISO 14001:2026, plus checklists for aligning corporate policy, audit cycles, and supplier oversight within the three-year transition window.
- Risk heatmaps and scenario playbooks: Operationally focused scenario modeling (acute pollution events, chronic biodiversity loss, supply chain shocks) with prescribed mitigation pathways and KPIs for follow-up.
- Vendor and capability due diligence: A repeatable vendor-selection playbook and a procurement scorecard (technical, operational, and commercial criteria) for selecting consulting partners, remediation contractors, software vendors, and insurers.
- Commercial and M&A guidance: Playbooks for inorganic growth (bolt-on acquisitions, joint ventures) and partner ecosystems—timing, valuation lenses, and integration risk checklists.
- Case studies and implementation templates: Real-world examples across high-risk verticals, procurement terms, sample governance charters, and implementation roadmaps to compress time-to-value.
- Proprietary tools: Scenario calculators, ROI matrices for mitigation investments, and a regulatory impact dashboard—designed to be integrated into enterprise risk management suites.
Competitive landscape — how to read it
The ENRM ecosystem comprises global engineering and consulting majors, operational service providers, specialized remediation firms, and emerging software players. Household names in the space—AECOM, Jacobs, Tetra Tech, WSP, Arcadis, ERM, Ramboll, Stantec, Veolia, and Clean Harbors—exhibit different competitive logics:
- Integrated engineering-consulting firms (e.g., AECOM, Jacobs, Arcadis, WSP) leverage scale, multidisciplinary delivery, and deep client relationships in infrastructure and large industrial projects. Their strength is bundled advisory-plus-execution offers across design, permitting, and remediation.
- Specialist environmental consultancies (e.g., ERM, Ramboll, Tetra Tech) often capture higher-margin advisory work—risk assessments, ESG integration, climate risk analytics, and remediation strategy—particularly for clients needing subject-matter depth.
- Operational operators (e.g., Veolia, Clean Harbors) combine advisory insights with hands-on operational capabilities—waste management, water treatment, and large-scale cleanups—creating defensible positions where execution matters most.
- New entrants and technology vendors are focused on software-enabled risk assessment, audit automation, remote sensing, and AI-driven analytics—areas that are rapidly being integrated into advisory offerings by incumbents.
For corporate buyers this means three strategic sourcing options: 1) One-stop integrated suppliers for scale and simplified contracting; 2) Boutique specialists for high-complexity advisory work; 3) Partnerships that pair software innovators with operational contractors for end-to-end risk reduction. Our study includes vendor archetypes and a procurement decision matrix to help choose the optimal approach for each risk profile.
Regulatory and market catalysts to watch in 2026
Three recent developments underline urgent planning needs:
- ISO 14001:2026—published April 2026—raises minimum expectations for climate, biodiversity, and supply chain oversight. The standard’s three-year transition window creates a near-term programmatic milestone for certifications and supplier alignment.
- ERM’s 2026 trends report signals rapid maturation of AI applications in sustainability reporting and emissions management—tools that materially change how risk is quantified, monitored, and reported to stakeholders.
- Market signals from insurance market forecasts highlight evolving capacity and new approaches to multinational environmental risk indemnity—pressuring firms to rethink capital allocation for residual risk.
Recommended 2026 action plan for executives
Translate insight into action with a staged program we recommend for 2026:
- Immediate (0–6 months): Conduct a rapid ISO 14001:2026 gap assessment; prioritize critical suppliers for enhanced due diligence; adopt a minimum viable digital audit trail for environmental incidents.
- Medium (6–18 months): Implement prioritized remediation and mitigation projects; deploy risk-assessment software pilots; re-negotiate key supplier contracts to include ENRM obligations and data access clauses.
- Longer-term (18–36 months): Integrate ENRM data into enterprise risk and financial planning systems; consider strategic acquisitions or partnerships to fill capability gaps; embed environmental KPIs into executive incentive structures.
Investment and M&A playbook
Low market concentration means there are transactional opportunities for acquirers that can bundle scale with niche capability. Target profiles include specialized remediation firms, software vendors with defensible data assets, and regional operators with strong local compliance expertise. Our annex provides a valuation framework and integration checklist oriented to the unique liabilities of environmental businesses.
Final note — what we deliberately withhold
This article presents the strategic frame and the most consequential managerial implications derived from our PW Consulting Environmental Risk Management Market study. To preserve the value of our proprietary segmentation, vendor scorecards, and quantitative annexes, we have deliberately withheld granular split figures by geography, solution type, and industry vertical within this summary. Those specific breakdowns—and the accompanying vendor-level benchmarking data—are available in the full report and the online client portal.
If you are preparing board materials, capital allocation proposals, or an acquisition target list for 2026, our study provides the essential models and templates to move from insight to action. Access the full report to unlock the segmentation matrices, vendor scoring sheets, regulatory transition timelines, and the scenario calculators that drive executable decisions.
For detailed analysis of this topic, please visit the official page: Environmental Risk Management Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


