



PW Consulting: ACM Market to Reach USD 1.31B by 2032 at 5.1% CAGR

Polyacrylate Rubber (ACM) Market: Strategic Outlook for 2026 Decision-Making
As senior industry advisors at PW Consulting, we present a high-confidence strategic primer on the Polyacrylate Rubber (ACM) market designed for executive teams preparing decisive actions in 2026. This preview synthesizes the most consequential market signals—historic performance, near-term forecasts, supply-chain shocks, raw-material cost dynamics, and competitive positioning—framed to support procurement, product, and M&A choices. To preserve the value of the underlying primary research and detailed segment matrices, core split tables and granular regional/application figures have been intentionally withheld from this preview; the full intelligence package is available on the official report page.
Polyacrylate Rubber Acm Market
Market trajectory at a glance
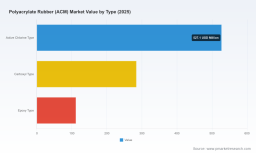
ACM has moved from niche elastomer status to a strategically important material for heat- and oil-resistant sealing and component applications. Between 2020 and 2025 the market expanded steadily—reflecting resilient end-demand in automotive and industrial markets—and reached roughly USD 922.45 Million in 2025. Our forecast models, incorporating scenario and sensitivity analyses, project the market to exceed approximately USD 1.03 Billion in 2026 and to grow to about USD 1.31 Billion by 2032, representing a compound annual growth rate (CAGR) of roughly 5.1% across the 2026–2032 forecast window.
Polyacrylate Rubber Acm Market
Why this matters for 2026 decisions
-
Procurement and margin management: Raw-material moves and regional supply disruptions in late 2025–early 2026 have materially altered cost pass-through dynamics. Recent upstream pricing actions (notably a $0.12/lb adjustment announced for key acrylic monomers) and regional availability constraints have tightened short-term availability and bargaining power.
Polyacrylate Rubber Acm Market -
Product strategy: As vehicle platforms evolve—thermal loads shift with electrified powertrains and service intervals extend—ACM grades that balance high-temperature oil resistance and improved low-temperature flexibility are becoming decisive product differentiators.
-
M&A and partnership timing: Market concentration is pronounced; the top three players control a dominant share and the top five an even larger portion of supply. This creates windows for bolt-on acquisitions and supply agreements but also elevates barriers for new entrants and late movers.
-
Regional footprint and trade-off analysis: Manufacturing and logistics choices made in 2026 will determine exposure to future regional regulatory inspections, energy-control events, and supply interruptions—factors already observed in early-2026 activity in key producing provinces.
What the PW Consulting report delivers (practical outputs)
-
High-resolution market sizing and forecasting framework (2020–2032) with integrated scenario runs (base, downside, upside) and a probabilistic outlook calibrated to raw-material price shocks and demand permutations.
-
Segment-level strategic playbooks (by product type, application family, and region) that translate demand forecasts into SKU-level revenue and margin implications. Note: the detailed segment tables and percentage splits are included in the full report only.
-
Supply-chain stress tests and a three-tier procurement playbook—covering hedging, contract structures, and dual-sourcing strategies for ethyl and butyl acrylate exposures.
-
Competitor heat maps, capability assessments, and prioritized partnership targets built from primary interviews and plant-level benchmarking.
-
Regulatory and operations risk matrix (including environmental inspections and power control events) and recommended mitigation steps for manufacturing continuity planning.
-
Actionable M&A screening criteria and a short-list of targets aligned to capability gaps such as low-temperature ACM grades, compounding scale, and regional fill-rate optimization.
Competitive landscape — executive summary
The supply base is concentrated and technology-driven. The leading global producers remain focused on application-specific grade portfolios, with a mix of upstream integration, compounding capabilities, and close OEM relationships shaping competitive advantage.
-
ZEON Corporation (Tokyo) – A long-standing global ACM producer with a portfolio emphasizing heat and oil resistance and engineered low-temperature variants targeted at demanding automotive sealing applications. Its R&D and grade breadth make it a natural partner for OEMs seeking high-performance, validated materials.
-
NOK Corporation (Tokyo) – A major supplier of ACM compounds, with deep integration into automotive sealing and gasket supply chains. Its strength is in component-level systems and Tier-1 relationships.
-
HEXPOL Rubber Compounding (Malmö) – Focuses on compounding and formulated ACM solutions for powertrain-related exposures, optimizing resistance to engine and transmission fluids—an important niche as fluid chemistries evolve.
-
RADO Gummi GmbH (Germany) – Specialist monomer-to-rubber manufacturers producing acrylic polymers from a range of acrylate monomers for specialized elastomer applications.
-
Sundow Polymers (China) – A domestic producer positioning its grades on cost-performance and aging resistance, important for regional OEM sourcing strategies.
-
Clwyd Compounders (UK) – High-performance compounder serving safety-critical and Tier-1 automotive segments, known for quality and traceability.
-
Mitsui Plastics (Distribution) – Distributor of performance ACM lines (e.g., RACRESTER™) serving markets where rapid supply and technical support are critical.
Market concentration metrics underline the strategic dynamics: the top three producers control a substantial proportion of supply, and the top five an even larger share—conditions that support premium pricing for differentiated grades and raise strategic value for targeted acquisitions.
Recent market signals to act on in 2026
-
Upstream pricing pressure: A notable monomer pricing action was implemented in early 2026, increasing costs for key acrylic monomers. Procurement teams should re-run margin models with these adjustments and evaluate indexation clauses in supplier contracts.
-
Regional supply interruptions: Environmental inspections and staggered power-control policies in key producing provinces reduced spot availability in early 2026—heightening the premium for readily available inventory and just-in-case strategies.
-
Capacity movements: Capacity investment announcements in adjacent polymer and additive markets indicate evolving competition for key feedstocks and catalyst markets; these are second-order effects that can alter lead times and contract dynamics.
-
Price volatility in China: Spot prices experienced double-digit month-on-month moves in March 2026 driven by local enforcement actions—an important reminder that regional supply volatility can drive global ripple effects through traded intermediate markets.
Practical recommendations for 2026 strategy
-
Immediate: Initiate a 90–120 day commodity reforecast and stress-test customer pricing mechanisms to absorb at least a portion of upstream shocks; prioritize contractual flexibility with key suppliers.
-
Quarter 2–3: Open negotiations for strategic long-term supply agreements with capacity guarantees and optionality clauses; evaluate small bolt-on acquisitions that secure proprietary grades or compounding capacity.
-
Medium-term: Accelerate product roadmaps that address the two-directional demand pressures—improved low-temperature performance for electric vehicle seals and enhanced thermal/oil resistance for higher-temperature ICE and hybrid applications.
-
Operational: Reassess regional footprint exposure to regulatory and energy-control risks; run a manufacturing continuity playbook that includes dual-sourcing and inventory buffers sized to key product families.
-
Commercial: Re-segment customer portfolios by margin-to-risk profile; prioritize OEM partnerships where differentiated material specs create higher switching costs and stronger margin capture.
How to get the full operational playbook
This briefing is designed to prioritize the high-leverage signals you need for near-term decisions while preserving the full granularity that supports deal execution and plant-level planning. The complete PW Consulting Polyacrylate Rubber (ACM) Market report includes the full segmentation tables, regional and application splits, supplier and customer payoff matrices, SKU-level margin bridges, and executable M&A target lists. For access to the full datasets and bespoke scenario runs tailored to your portfolio, please visit the report page referenced at the beginning of this release.
PW Consulting stands ready to convert these insights into tailored roadmaps—procurement hedges, business unit playbooks, and acquisition diligence—that convert market foresight into measurable outcomes during 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Polyacrylate Rubber Acm Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


